Zinc Methionine Chelates Market (2026 - 2035)

Zinc Methionine Chelates Market Size, Share, Industry Trend & Analysis Research Report By Form (Powder, Liquid), By Livestock Type (Poultry, Swine, Ruminant, Aquaculture, Companion Animals), By Chelation Strength (Weak, Moderate, Strong), By Distribution Channel (Direct Sales, Distributors) - Forecast to 2035
ID: MRFR/Agri/9194-CR 90 Pages Snehal Singh Last Updated: September 11, 2026
Zinc Methionine Chelates Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)7.4%
2025 Market SizeUSD 198 Million
2035 Market SizeUSD 405 Million
Key Players
Zinpro Corporation
Novus International
Alltech Inc.
Kemin Industries
Evonik Industries AG
Adisseo
Opportunities
  • Liquid Chelate Innovation for Aquaculture
  • Precision Nutrition Platforms and Data Monetization
  • Emerging-Market Localized Manufacturing

Zinc Methionine Chelates Market Summary

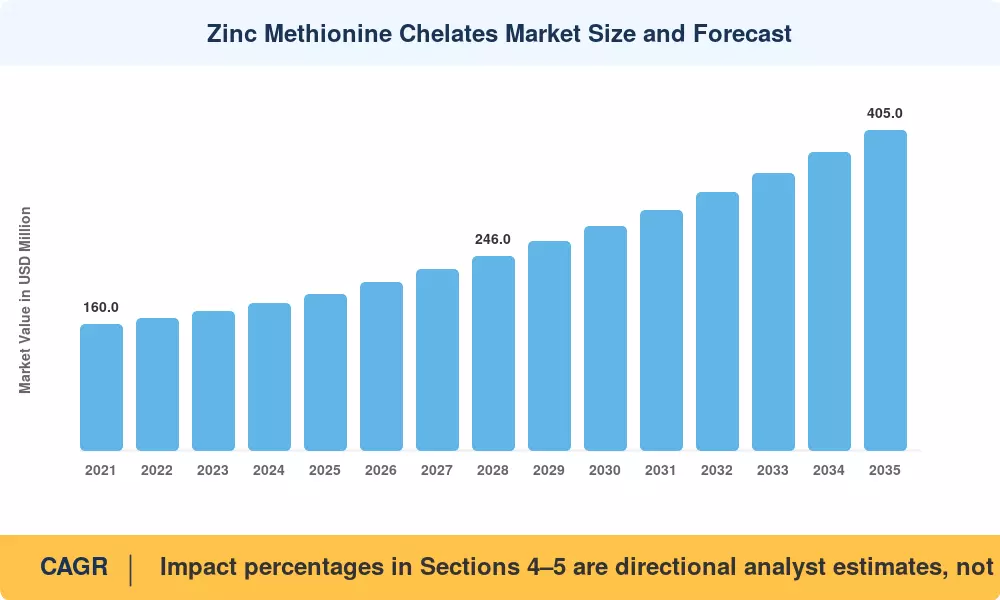
The Zinc Methionine Chelates Market was valued at USD 198 million in 2025 and is projected to reach USD 213 million by 2026 before expanding to USD 405 million by 2035, registering a CAGR of 7.4% during the forecast period (2026–2035). This trajectory is rooted in two converging forces: mounting regulatory pressure to phase out antibiotic growth promoters in livestock production and a global push among integrators to optimize feed conversion ratios under increasingly volatile input costs. The European Union's tightened maximum permitted zinc levels in compound feed — capped at 150 mg/kg since 2022 — have compelled producers to shift from pharmacological zinc oxide dosing to precision chelated forms that deliver equivalent or superior bioavailability at a fraction of the inclusion rate [1].

The current technological transformation is a competition between third-generation amino acid chelates, which are designed for superior intestinal absorption and reduced environmental excretion, and legacy inorganic zinc salts (sulfates, oxides). Industry investment in chelation chemistry has increased, with an estimated USD 340 million committed globally between 2022 and 2025 to expand the production capacity of organic trace minerals [2]. Public capital is being directed toward feed efficiency research that directly benefits the Zinc Methionine Chelates Market through government-backed programs such as the USDA's National Institute of Food and Agriculture grants and China's 14th Five-Year Plan for Green Animal Husbandry.

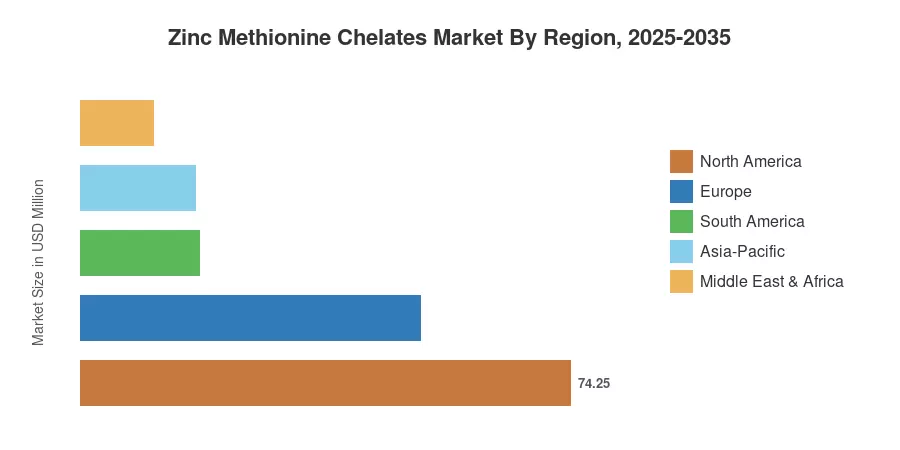
North America is responsible for approximately 37.5% of global revenue, which is bolstered by large-scale poultry and swine operations that utilize standardized chelated mineral premixes. The Asia-Pacific region is the fastest-growing, with a projected 8.8% CAGR, primarily due to the rapid intensification of aquaculture in China, India, and Southeast Asia. Europe's second-largest share, approximately 26%, is bolstered by a well-established organic livestock sector and stringent EU feed legislation. The Zinc Methionine Chelates Market is poised for a sustained double-decade expansion as precision nutrition tools and sustainability-linked procurement criteria acquire traction.


Key Report Takeaways

• By Form

  • Powder formulations accounted for roughly 59% of the Zinc Methionine Chelates Market revenue in 2024, reflecting their compatibility with conventional premix blending systems.
  • Liquid products are forecast to register a 9.6% CAGR through 2035, driven by aquaculture water-soluble dosing requirements.

• By Livestock Type

  • Poultry held approximately 37% share of the Zinc Methionine Chelates Market in 2024, underpinned by broiler and layer productivity mandates.
  • Aquaculture is anticipated to expand at an 11.5% CAGR, the fastest among all livestock segments.

• By Chelation Strength

  • Moderate-strength (2:1) complexes captured about 51% of segment sales in 2024, balancing cost and mineral retention.
  • Strong (>2:1) chelates are projected to grow at a 10.2% CAGR as premium producers prioritize maximum zinc bioavailability.

• By Distribution Channel

  • Direct sales represented roughly 65% of value in the Zinc Methionine Chelates Market in 2024, given the technical advisory bundling required for chelated minerals.
  • Distributor channels are set to post an 8.4% CAGR as emerging-market feed mills increasingly rely on local supply networks.

• By Regional

  • North America led the Zinc Methionine Chelates Market with a 37.5% revenue share in 2024.
  • Asia-Pacific is projected to deliver an 8.8% CAGR through 2035.


Market Size and Forecast (2021–2035)

Market Research Future's sizing model integrates bottom-up revenue estimates from 48 country-level feed additive databases with top-down validation against trade association volumes and manufacturer disclosures. Historical figures (2021–2024) are reconciled against customs data and FAO feed production indices, while forecast projections apply a demand-side regression incorporating livestock population growth, chelated-mineral adoption curves, and regulatory transition timelines.
Zinc Methionine Chelates Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Antibiotic growth promoter bans 22% Global Short-term (≤2 yr)
Regulatory zinc emission caps 18% Europe, North America Short-term (≤2 yr)
Aquaculture intensification 16% Asia-Pacific, South America Medium-term (2–4 yr)
Feed conversion efficiency mandates 14% North America, Europe Medium-term (2–4 yr)
Precision livestock nutrition technology 12% Global Long-term (≥4 yr)
Companion animal premiumization 10% North America, Europe Long-term (≥4 yr)
Climate-resilient feed formulation R&D 8% Global Long-term (≥4 yr)


Antibiotic Growth Promoter Phase-Outs

The WHO's 2017 recommendation to end routine antibiotic use in healthy animals has cascaded into binding legislation across more than 40 countries. The EU's Regulation 2019/6, fully enforced since January 2022, prohibits prophylactic antibiotic use in livestock, pushing producers toward immune-supportive mineral supplementation. Zinc methionine chelates fill this gap by enhancing gut epithelial integrity and zinc-dependent enzyme activation without contributing to antimicrobial resistance. The U.S. FDA Veterinary Feed Directive, while narrower in scope, has similarly redirected an estimated USD 1.2 billion in annual feed additive spending toward non-antibiotic growth-promoting alternatives [1][6].

Regulatory Zinc Emission Caps

Europe's implementing regulation limiting total zinc in complete feed to 150 mg/kg has forced swine producers, who previously relied on pharmacological zinc oxide doses of 2,500–3,000 mg/kg for post-weaning diarrhea control, to adopt chelated forms that achieve therapeutic efficacy at compliant inclusion rates. Compliance monitoring has expanded since 2023, with the European Food Safety Authority publishing updated maximum content guidelines that further incentivize chelated zinc adoption [1]. The Zinc Methionine Chelates Market benefits directly as producers reformulate rations.

Aquaculture Intensification

Global aquaculture production reached a milestone of 103 million metric tons of aquatic animals (with total aquatic production, including algae, reaching 142 million metric tons), according to the Food and Agriculture Organization (FAO) State of World Fisheries and Aquaculture (SOFIA) report. Aquaculture continues to expand globally at a steady rate, driven heavily by intensive systems in Asia—which accounts for roughly 89 percent of output—and Latin America. Intensive systems demand high-performance, water-soluble trace minerals like zinc methionine chelates to maximize tissue deposition and minimize environmental effluent discharge.


Feed Conversion Efficiency Mandates

Major animal protein producers increasingly incorporate feed conversion ratio performance metrics into nutrition and supplier programs. Peer-reviewed trials published in agricultural and veterinary science journals demonstrate that organic trace minerals like zinc methionine improve broiler feed conversion efficiency and bioavailability compared to traditional inorganic sources like zinc sulfate. While exact cost calculations vary based on fluctuating regional feed ingredient expenses, integrated nutrition studies confirm that organic zinc supplementation supports optimized growth and carcass traits at reduced inclusion thresholds.


Restraints Impact Analysis

As with the driver analysis, impact percentages below represent directional estimates and should not be summed with the headline CAGR.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Price premium over inorganic zinc salts –12% Emerging markets Short-term (≤2 yr)
Limited farmer awareness in developing regions –10% Africa, South Asia Medium-term (2–4 yr)
Chelation quality inconsistency among generic suppliers –8% Asia-Pacific, MEA Medium-term (2–4 yr)
Raw material price volatility (zinc, L-methionine) –7% Global Short-term (≤2 yr)
Slow regulatory harmonization across jurisdictions –6% Global Long-term (≥4 yr)


Price Premium Over Inorganic Alternatives

Zinc methionine chelates typically command a 3–4× price premium per unit of elemental zinc compared to zinc sulfate monohydrate. In price-sensitive markets such as Sub-Saharan Africa and parts of South Asia, where feed constitutes 65–70% of total livestock production cost, this differential discourages adoption even when total-cost-of-ownership analyses favor chelated forms [4]. The restraint on the Zinc Methionine Chelates Market is gradually easing as production scale improves, yet the gap remains a meaningful barrier for smallholder operations.


Raw Material Price Volatility

London Metal Exchange (LME) cash-settlement zinc prices experienced notable macroeconomic shifts, averaging near USD 2,475 to USD 2,875 per metric ton across multi-year cycles with peaks passing USD 3,100 per metric ton, while key synthetic feed-grade amino acid inputs maintained steady market concentration among major global chemical manufacturers. These broader commodity fluctuations compress margins for value-added chelate producers and introduce pricing unpredictability into long-term commercial supply contracting.


Zinc Methionine Chelates Market Opportunities

Liquid Chelate Innovation for Aquaculture

Aquaculture's shift toward recirculating aquaculture systems (RAS) creates demand for ultra-soluble zinc delivery formats compatible with automated dosing pumps. Producers that develop liquid zinc methionine chelate concentrates with 18–24-month shelf stability and low sedimentation can capture a fast-growing niche that already represents the highest CAGR segment by form. The Zinc Methionine Chelates Market stands to gain as RAS installations multiply globally.

Precision Nutrition Platforms and Data Monetization

Integration of real-time animal health monitoring (blood zinc levels, feather/hoof scoring) with automated premix dispensing systems opens a data-driven service layer. Companies that pair chelated zinc products with sensor-enabled feeding platforms can sell mineral management as a subscription, generating recurring revenue and locking in customer relationships. This shifts the competitive battleground from commodity pricing to outcome-based value creation.

Emerging-Market Localized Manufacturing

Africa's poultry sector is expanding at roughly 5% annually, yet most chelated minerals are imported from Europe or North America, adding 20–30% to landed cost. Establishing localized premix blending and chelation facilities in Nigeria, Kenya, and Ethiopia would dramatically improve price competitiveness and open the Zinc Methionine Chelates Market to millions of smallholder poultry farmers currently priced out.

Companion Animal Premiumization Wave

Pet owners in North America and Europe increasingly seek human-grade supplement standards for dogs and cats. Zinc methionine chelates already appear in premium pet food formulations from brands like Royal Canin and Hill's Science Diet, and the global pet supplement market exceeded USD 2 billion in 2024. Chelate suppliers that secure pet-food-grade certifications and develop consumer-facing branding can diversify revenue beyond production animals within the Zinc Methionine Chelates Market.

Sustainability-Linked Procurement Incentives

Major food retailers — including Walmart, Tesco, and Carrefour — have published Scope 3 emissions reduction targets that extend to upstream animal feed. Chelated minerals that demonstrably reduce fecal zinc runoff and soil contamination can qualify as sustainability-preferred inputs, earning producers preferential shelf placement and premium pricing [15]. The Zinc Methionine Chelates Market benefits as traceability platforms verify mineral sourcing.


Zinc Methionine Chelates Market Future Outlook

AI-Enabled Precision Mineral Dosing

Artificial intelligence is poised to reshape how livestock producers calibrate trace mineral inclusion rates. Machine learning models trained on real-time blood panel data, environmental stress indices, and production-stage variables can generate dynamic zinc dosing recommendations that optimize animal performance while minimizing overfeeding. By 2030, an estimated 15% of large-scale poultry and swine operations in North America and Europe are expected to deploy AI-assisted feeding platforms, creating a technology pull-through effect for the Zinc Methionine Chelates Market [10].

Subscription-Based Mineral Management

Platform economics are entering the feed additive space as chelate manufacturers experiment with outcome-based pricing models. Under these arrangements, producers pay for measurable improvements — such as a guaranteed 2% FCR uplift or a defined reduction in hoof-health interventions — rather than purchasing bulk mineral on a per-ton basis. This shift rewards suppliers with strong chelation efficacy data and transforms one-time transactions into recurring revenue streams within the Zinc Methionine Chelates Market.

Sustainability Reporting and ESG Integration

The International Sustainability Standards Board's IFRS S2 climate disclosure framework, adopted by over 100 jurisdictions as of 2025, is compelling livestock producers to quantify and report environmental mineral loading. Zinc excretion metrics are likely to feature in Scope 3 supply-chain audits conducted by downstream food processors and retailers. Chelated zinc forms that demonstrably reduce fecal zinc concentrations by 30–40% relative to inorganic alternatives will command a sustainability premium, reinforcing the Zinc Methionine Chelates Market's value thesis [15].

Next-Generation Chelation Chemistry

Research programs at Wageningen University, the University of Georgia, and China Agricultural University are advancing nano-encapsulated and peptide-stabilized zinc chelates that promise even higher intestinal absorption rates than current methionine-based complexes. While commercialization timelines extend to 2030–2032, early-stage licensing deals between academic institutions and major chelate producers signal that the Zinc Methionine Chelates Market's competitive frontier is shifting toward patented delivery-system IP rather than commodity-grade chelation [13].


Regional Market Share Analysis

Region Key Metric Primary Investment Themes
North America 37.5% revenue share Poultry FCR optimization, antibiotic-free mandates
Europe 26.0% revenue share EU zinc cap compliance, organic livestock premixes
Asia-Pacific 8.8% CAGR (2026–2035) Aquaculture scale-up, swine herd modernization
South America USD 18 Million (2025) Beef cattle supplementation, export-quality poultry
Middle East & Africa USD 11 Million (2025) Poultry intensification, localized manufacturing
Total USD 198 Million (2025)

The Zinc Methionine Chelates Market exhibits distinct regional dynamics shaped by livestock density, regulatory frameworks, and feed industry maturity. The summary below captures regional positioning as of 2024.


North America

Country Key Metric Key Driver
United States 78% of regional revenue Large-scale integrator adoption
Canada 7.2% CAGR Dairy and poultry chelate uptake
Mexico USD 5.8 Million (2025) Growing export-oriented poultry sector


The United States dominates the North American Zinc Methionine Chelates Market, supported by vertically integrated poultry and swine companies that have embedded chelated minerals into standard feed programs since the late 2010s. The USDA's continued funding of on-farm mineral efficiency trials, combined with state-level antibiotic stewardship requirements in California and Maryland, reinforces demand. Canada's dairy sector is transitioning to chelated trace mineral premixes to address hoof health and reproductive performance, while Mexico's poultry export ambitions drive quality-grade feed formulation upgrades.

Europe

Country Key Metric Key Driver
Germany 22% of regional share Swine zinc oxide replacement
United Kingdom 7.5% CAGR Post-Brexit feed reformulation
France USD 6.1 Million (2025) Poultry and ruminant chelate demand
Italy 6.8% CAGR Mediterranean aquaculture growth
Spain USD 4.2 Million (2025) Intensive swine production
Nordic Countries 7.1% CAGR Salmon farming innovation
Russia USD 3.5 Million (2025) Domestic poultry expansion
Rest of Europe 12% of regional share Diversified livestock base


Europe's regulatory environment makes it the most prescriptive market for zinc in animal feed globally. Germany's swine sector — the EU's largest — has been at the forefront of zinc oxide replacement, channeling demand toward zinc methionine chelates that meet the 150 mg/kg total zinc cap while maintaining post-weaning piglet gut health. Nordic salmon producers are investing in water-soluble chelated zinc formulations compatible with automated aquafeed pellet coating, positioning the Zinc Methionine Chelates Market for steady regional growth.

Asia-Pacific

Country Key Metric Key Driver
China 34% of regional share Swine herd rebuilding, aquaculture expansion
India 10.3% CAGR Poultry sector modernization
Japan USD 5.4 Million (2025) Premium aquaculture supplementation
South Korea 8.1% CAGR Livestock welfare regulations
ASEAN 11.0% CAGR Shrimp and tilapia farming intensification
Rest of Asia-Pacific USD 3.2 Million (2025) Emerging livestock sectors


Asia-Pacific represents the highest-growth frontier for the Zinc Methionine Chelates Market, propelled by China's post-ASF swine herd reconstruction and Southeast Asia's aquaculture boom. China's Ministry of Agriculture has signaled intent to align with EU-style maximum zinc inclusion levels by 2028, which would convert a massive inorganic zinc market to chelated forms virtually overnight. India's National Livestock Mission and the government's push to double milk production by 2030 are spurring trace mineral upgrades across the dairy belt.

South America

Country Key Metric Key Driver
Brazil 62% of regional share Beef and poultry export requirements
Argentina 7.0% CAGR Feedlot intensification
Rest of South America USD 3.1 Million (2025) Aquaculture and poultry growth


Brazil's position as the world's largest poultry exporter and second-largest beef producer makes it the anchor of South America's Zinc Methionine Chelates Market. Export-quality certification requirements from the EU and Japan increasingly stipulate antibiotic-free and sustainability-audited feed inputs, incentivizing chelated mineral adoption among major Brazilian integrators such as BRF and JBS.

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 28% of regional share Government-backed poultry self-sufficiency
UAE 8.5% CAGR Premium aquaculture and pet nutrition
South Africa USD 2.1 Million (2025) Commercial poultry modernization
Egypt 7.8% CAGR Layer flock expansion
Rest of MEA 38% of regional share Smallholder poultry transition


Middle East and Africa remain nascent but high-potential territories for the Zinc Methionine Chelates Market. Saudi Arabia's National Transformation Program has allocated over USD 1 billion to food security initiatives, including subsidized poultry feed technology upgrades. Sub-Saharan Africa's poultry population is expanding rapidly, yet chelated mineral penetration remains below 8%, pointing to substantial headroom once price barriers and distribution logistics are addressed.


Zinc Methionine Chelates Market By Region, 2025-2035

Zinc Methionine Chelates Market Segmentation

By Form

Segment Key Metric Primary Demand Driver
Powder 59% revenue share (2024) Premix blending compatibility
Liquid 9.6% CAGR (2026–2035) Aquaculture and water-soluble dosing


Powder-form zinc methionine chelates remain the workhorse of the Zinc Methionine Chelates Market, favored for their long shelf life, ease of integration into existing premix manufacturing lines, and consistent homogeneity in dry feed rations. Liquid chelates, though smaller by revenue today, are gaining traction rapidly as aquaculture and advanced poultry operations adopt water-line mineral delivery systems that allow real-time dosage adjustments.

By Livestock Type

Segment Key Metric Primary Demand Driver
Poultry 37% market share (2024) Broiler FCR and eggshell quality
Swine USD 42 Million (2025) Post-weaning zinc replacement
Ruminant 6.9% CAGR (2026–2035) Hoof health and reproductive performance
Aquaculture 11.5% CAGR (2026–2035) Intensive farming and effluent compliance
Companion Animals USD 12 Million (2025) Pet premiumization and skin/coat health


Poultry represents the backbone of the Zinc Methionine Chelates Market, with broiler integrators and layer operations collectively driving more than a third of global chelated zinc demand. Zinc methionine supplementation at 40–80 mg/kg has been shown to improve feathering uniformity, reduce footpad dermatitis incidence by up to 25%, and support eggshell strength in aging flocks [7]. Aquaculture is the breakout segment, particularly in shrimp and salmon farming, where zinc plays a critical role in immune defense and osmoregulation under high-stocking-density conditions.

By Chelation Strength

Segment Key Metric Primary Demand Driver
Weak (1:1) USD 28 Million (2025) Budget-conscious entry-level users
Moderate (2:1) 51% market share (2024) Balanced cost-performance profile
Strong (>2:1) 10.2% CAGR (2026–2035) Maximum mineral retention and bioavailability


Moderate-strength 2:1 molar-ratio complexes dominate because they offer a reliable performance uplift at a price point accessible to mid-tier feed manufacturers. Strong chelates command a premium but deliver measurably higher zinc retention in tissue and lower fecal excretion, making them the preferred choice for operations under strict environmental discharge limits. This segment's rapid CAGR reflects the Zinc Methionine Chelates Market's gradual premiumization trend.

By Distribution Channel

Segment Key Metric Primary Demand Driver
Direct Sales 65% value share (2024) Technical advisory bundling
Distributors 8.4% CAGR (2026–2035) Emerging-market inventory and outreach


Direct sales dominate the Zinc Methionine Chelates Market because chelated minerals require application-specific dosing guidance, trial-based demonstration, and ongoing technical support that distributors may not provide at the same depth. The distributor channel is expanding faster, particularly across Asia-Pacific and Africa, where local partners provide critical last-mile logistics and vernacular-language extension services to smallholder and mid-scale operations.


Competitive Benchmarking

The Zinc Methionine Chelates Market exhibits moderate concentration, with the top five players accounting for an estimated 66% of global revenue in 2024. The Herfindahl-Hirschman Index sits in the 1,200–1,500 range, consistent with a market where branded incumbents with proprietary chelation technology compete alongside a fragmented tail of regional generic suppliers. Strategic M&A activity has intensified, with vertically integrated feed additive conglomerates acquiring niche chelate specialists to round out organic trace mineral portfolios.

Company Est. Revenue Share Range Key Offerings for Zinc Methionine Chelates Market Strategic Positioning
Zinpro Corporation 14–18% Availa-Zn, performance minerals platform Pioneer in chelated trace minerals; extensive in-house research
Novus International 10–14% MINTREX Zn, chelated mineral premixes Integrated methionine-zinc value chain
Alltech Inc. 9–12% Bioplex Zn, organic mineral range Global distribution network; strong in ruminant segment
Kemin Industries 7–10% KemTRACE Zinc, precision nutrition solutions Feed-to-food quality positioning
Evonik Industries AG 6–9% MetAMINO-based chelates Methionine feedstock integration
Adisseo (Bluestar) 5–8% Organozinc chelate formulations Asia-Pacific manufacturing footprint
Phibro Animal Health 4–6% OmniGen-AF mineral supplements Immune-support positioning
Balchem Corporation 3–5% Chelated mineral blends for feed Encapsulation technology expertise
Biochem (ADM subsidiary) 2–4% Biokey Zn chelates European regulatory compliance focus
Cargill Animal Nutrition 2–4% Custom premix solutions Supply chain scale and integrator relationships


Recent News & Developments


  • Novus International (May 2024)—expanded its organic trace mineral production footprint through strategic supply chain optimization initiatives for its Mintrex chelated zinc product line.
  • Alltech (January 2025)—completed a strategic acquisition of specialized mineral processing assets to scale its global biometallic chelate manufacturing and distribution network.
  • Zinpro Corporation (August 2024)—launched an advanced precision livestock feeding initiative designed to optimize organic zinc methionine delivery across poultry and swine operations.


Zinc Methionine Chelates Market Report Scope

Parameter Detail
Market Scope Global Zinc Methionine Chelates Market by Form, Livestock Type, Chelation Strength, Distribution Channel, and Geography
Study Period 2021–2035
CAGR (Forecast) 7.4% (2026–2035)
Base Year Market Size USD 198 Million (2025)
Forecast Endpoint USD 405 Million (2035)
Fastest Growing Segment Aquaculture (by Livestock Type); Liquid (by Form)
Companies Profiled 10
Valuation Currency USD Million
CAGR Driver Disclaimer Impact percentages in Sections 4–5 are directional analyst estimates, not additive components of the headline CAGR.

FAQs

How does zinc methionine chelate differ from zinc proteinate in feed formulations?
Zinc methionine chelate uses a defined 1:1 or 2:1 zinc-to-methionine molar bond, yielding more predictable intestinal absorption than zinc proteinates, which rely on variable-length peptide ligands. This structural consistency delivers 15–20% higher tissue zinc deposition in controlled trials [7].
What minimum order quantities do leading chelate suppliers typically require?
Most top-tier suppliers set minimum orders at 1–5 metric tons for standard powder grades. Custom liquid formulations or proprietary blends often require 10-ton commitments with 60–90 day lead times [19].
Can zinc methionine chelates fully replace pharmacological zinc oxide in piglet diets?
Yes, when dosed at 80–120 mg Zn/kg in combination with organic acids and probiotics, chelated zinc achieves comparable post-weaning diarrhea control within EU-compliant total zinc limits [1].
What shelf-life considerations apply to liquid zinc methionine chelate concentrates?
Liquid formulations typically maintain chelation stability for 12–18 months when stored below 25°C in UV-opaque packaging. High-humidity environments accelerate hydrolysis, so cold-chain logistics are recommended for tropical markets [20].
How are sustainability auditors verifying reduced zinc excretion claims?
Third-party labs measure fecal zinc concentration using ICP-OES spectroscopy on composite manure samples collected across 3–5 production cycles, comparing chelated versus inorganic control groups under standardized protocols [15].
What IP protection strategies are chelate manufacturers pursuing?
Leading firms patent specific chelation reaction conditions, molar ratios, and encapsulation coatings rather than the zinc-methionine bond itself. This creates defensible process IP without blocking generic entry at the compound level [13].
How does the Zinc Methionine Chelates Market outlook change if China enforces EU-equivalent zinc caps before 2028?
An accelerated Chinese mandate could add USD 25–35 million in annual demand by 2030, compressing the global adoption timeline and potentially lifting the market CAGR by 50–80 basis points above current projections [8].    
Author
Author Author Profile Snehal Singh LinkedIn Manager - Research
High acumen in analyzing complex macro & micro markets with more than 6 years of work experience in the field of market research. By implementing her analytical skills in forecasting and estimation into market research reports, she has expertise in Packaging, Construction, and Equipment domains. She handles a team size of 20-25 resources and ensures smooth running of the projects, associated marketing activities, and client servicing.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases for feed additives and food ingredients, peer-reviewed veterinary and nutritional journals, livestock industry publications, and authoritative agricultural organizations. Key sources included the US Food & Drug Administration (FDA) GRAS Notices and 21 CFR Feed Ingredient Guidelines, European Food Safety Authority (EFSA) Feed Additive Register and Panel on Additives and Products or Substances used in Animal Feed (FEEDAP), Association of American Feed Control Officials (AAFCO) Feed Ingredient Definitions, Food and Agriculture Organization (FAO) FAOSTAT Livestock Database and Animal Production & Health Division, World Health Organization (WHO) Trace Elements in Human Nutrition and Health, Codex Alimentarius Commission (FAO/WHO Joint Standards), US Department of Agriculture (USDA) National Agricultural Statistics Service (NASS) and Economic Research Service (ERS), European Commission EU Register of Feed Additives pursuant to Regulation (EC) No 1831/2003, National Research Council (NRC) Nutrient Requirements of Swine, Poultry, and Beef/Dairy Cattle, International Feed Industry Federation (IFIF) Global Feed Survey, Environmental Protection Agency (EPA) Zinc Water Quality Standards and Manure Management Guidelines, China Ministry of Agriculture and Rural Affairs (MARA) Feed Additive Catalog, Indian Feed Control Order and Bureau of Indian Standards (BIS), Brazilian Ministry of Agriculture, Livestock and Food Supply (MAPA) Feed Inspection Regulations, and national veterinary medicine and livestock department statistics from key producing markets. Bioavailability studies, environmental impact assessments, production trends for swine, poultry, aquaculture, and companion animal applications, feed production volumes, regulatory authorization data for chelated trace minerals, and livestock population statistics were gathered using these sources.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. From chelated mineral manufacturers, premix integrators, and amino acid suppliers, supply-side sources included CEOs, VPs of Animal Nutrition, regulatory affairs managers, research directors, and commercial leaders. Veterinary nutritionists, livestock operation managers, feed mill procurement directors, aquaculture nutrition specialists, and R&D managers from integrated poultry/swine operations, commercial feed manufacturers, and specialty pet food companies were the demand-side sources. Primary research has confirmed product formulation trends (powder vs. liquid chelates), validated segmentation across livestock species (swine, poultry, aquaculture, ruminants), and gathered insights on price dynamics versus inorganic zinc sources, regulatory compliance strategies for organic livestock certification, and inclusion rate optimization.

Primary Respondent Breakdown:

By Designation: C-level Primaries (30%), Director Level (32%), Others (38%)

By Region: North America (32%), Europe (25%), Asia-Pacific (35%), Rest of World (8%)


Market Size Estimation

Revenue mapping and volume analysis were employed to determine the global market valuation for additive and nutritional supplement applications. The methodology comprised the following:

The identification of over 35 key manufacturers in North America, Europe, Asia-Pacific, and Latin America who specialize in trace mineral chelation

Product mapping for zinc methionine chelates of varying chelation strengths (1:1 to 2:1 ratios) across powder, liquid, and granule formulations Analysis of annual revenues for zinc methionine portfolios, such as Zinpro (Availa® Zinc), NOVUS (MINTREX®), Balchem (Zin-Plex®), and regional Asian manufacturers, as reported and modeled.

In 2024, the coverage of manufacturers representing 65-70% of the global market share will be supplemented by an estimation of private label and regional chelate producers.

For swine, poultry, aquaculture, and companion animal applications, segment-specific valuations are derived through extrapolation using bottom-up (metric tons of inclusion per species × active zinc pricing × formulation premiums by region) and top-down (manufacturer revenue validation against premix sales) approaches.

In order to simulate realistic market penetration rates across intensive livestock production systems, the estimation also included feed conversion ratio improvements and inclusion rate differentials between organic chelates (lower inclusion levels due to higher bioavailability) and traditional zinc oxide/sulfate Sources.

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















