Well Intervention Market Summary
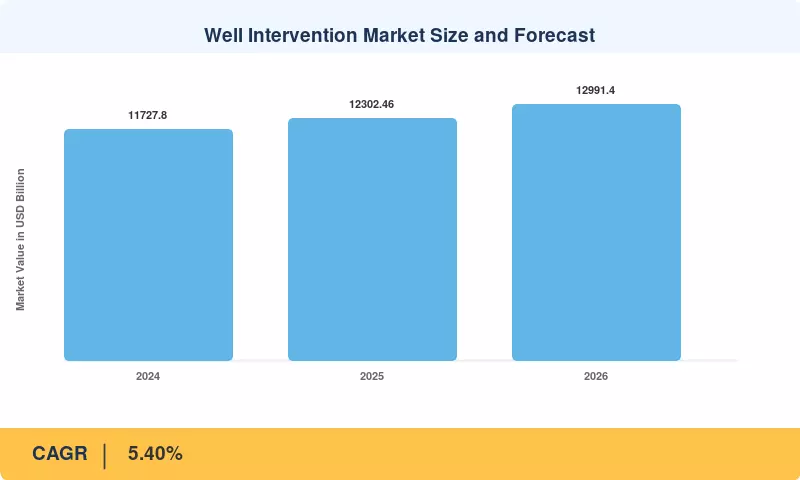
The global well intervention market is valued at USD 12,302.46 Million in 2025 and is forecast to reach USD 20,788.02 Million by 2035, expanding at a CAGR of 5.40% across the 2026–2035 window. The forecast period opens at USD 12,991.40 Million in 2026, implying a 5.60% step-up from the base year, followed by a 6.40% expansion to USD 13,822.85 Million in 2027 — the steepest single-year growth in the entire modelled series and a signal that operator capital is front-loading into brownfield work programmes rather than greenfield exploration. Two structural forces account for the majority of that trajectory. The first is the growing demand for mature field rejuvenation and production enhancement: the global producing asset base is ageing faster than it is being replaced, and intervention spend is the lowest-cost-per-incremental-barrel lever available to operators facing capital discipline mandates. The second is increasing oil and gas exploration activity globally, which lifts the installed well stock and, with a two-to-four-year lag, the addressable intervention population. Against these, high operational costs associated with well intervention processes — particularly offshore vessel day-rates, riser systems and specialist crew mobilisation — remain the principal drag on adoption intensity, especially for marginal onshore wells where intervention economics are thin.
The dominant technology transition inside the market is the migration of workscope from conventional rig-based intervention toward lighter, faster, cable- and tubing-conveyed methods. Wireline is the largest technology segment at USD 3,447.24 Million in 2025 (28.02% share), split between electric line cased-hole logging (USD 2,055.32 Million) and other wireline services (USD 1,391.92 Million); slickline follows at USD 2,856.45 Million. The fastest-growing technology, however, is coiled tubing at 5.90% CAGR, reflecting its expanding role in extended-reach horizontal cleanouts, nitrogen lifting and through-tubing stimulation — workscopes that a conventional rig cannot execute economically. On the service axis, well maintenance is the largest line item at USD 2,451.33 Million, ahead of artificial lift services at USD 2,140.22 Million and workover services at USD 2,040.13 Million, while stimulation services grow fastest at 6.00% CAGR. The materials layer beneath these services is being upgraded in parallel: Daikin Industries is building a new FFKM production facility at its Kashima Plant in Ibaraki, Japan, to lift perfluoroelastomer capacity more than threefold, and Arkema has started up a 15% PVDF capacity expansion at Calvert City, Kentucky, on a roughly USD 20 million investment — both feedstocks that govern the temperature and chemical-service envelope of downhole seals, packer elements and flexible-pipe liners used in high-pressure, high-temperature intervention.
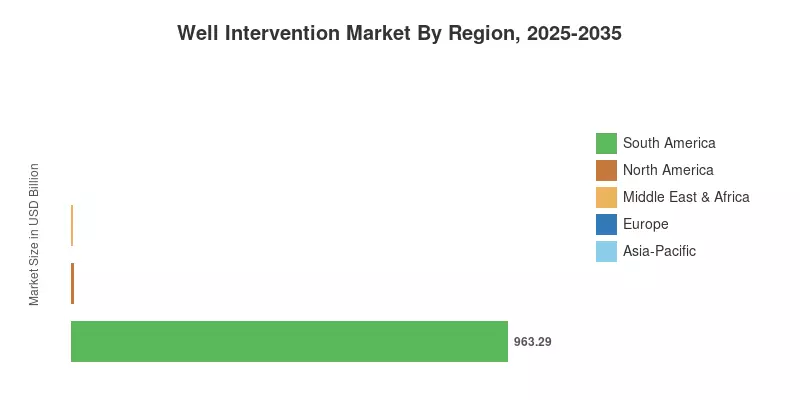
Regionally, the Middle East & Africa well intervention market is the dominant revenue block, underpinned by the world's largest population of high-productivity, long-life wells requiring continuous conformance and artificial-lift management, and by national oil company programmes that treat intervention as a production-assurance function rather than discretionary spend. North America well intervention market is designated the fastest-growing region in this report cycle, carrying USD 4,765.98 Million of 2025 revenue across the two countries modelled — the United States at USD 1,846.34 Million (4.90% CAGR) and Canada at USD 2,919.64 Million (4.00% CAGR). Asia-Pacific well intervention market is the third pillar at USD 1,798.61 Million with a computed 5.86% blended CAGR, led by China (USD 1,131.15 Million) and the fastest-growing single country in the model, India, at 6.30%. Europe contributes USD 1,359.43 Million, of which Norway alone accounts for USD 655.24 Million, and South America contributes USD 963.29 Million on the strongest regional growth profile in the country-level data (6.64% blended), driven by Brazil at 6.80% and Argentina at 7.10%. Through 2035, the market's centre of gravity shifts from volume-driven rig workover toward diagnostics-led, digitally scheduled intervention, with geothermal end-use — growing at 7.20% CAGR, the fastest of any segment in the study — emerging as the first genuinely non-hydrocarbon demand pool for conventional intervention fleets.
Key Report Takeaways
| Segment Dimension | Key Metric | Notes |
|---|---|---|
| Global Market | USD 12,302.46 Mn (2025) → USD 20,788.02 Mn (2035) | 5.40% CAGR over 2026–2035; 1.69× expansion over the forecast window |
| Service Type — Dominant | Well Maintenance, USD 2,451.33 Mn (19.93% share, 2025) | Recurring, non-discretionary scope; least exposed to oil-price cyclicality |
| Service Type — Fastest | Stimulation Services, 6.00% CAGR | Matrix acidising and re-frac demand from declining unconventional and carbonate assets |
| Service Type — Second Largest | Artificial Lift Services, USD 2,140.22 Mn (17.40% share) | Grows at 5.50%; directly tied to mature-field water-cut escalation |
| Application — Dominant | Onshore, USD 8,570.30 Mn (69.66% share, 2025) | Volume base; lower per-job value but very high job frequency |
| Application — Fastest | Offshore, 6.10% CAGR | Highest revenue-per-intervention; riserless light well intervention is the swing driver |
| Technology — Dominant | Wireline, USD 3,447.24 Mn (28.02% share, 2025) | Parent segment comprising electric line cased-hole logging and other wireline services |
| Technology — Fastest | Coiled Tubing, 5.90% CAGR | Extended-reach cleanout and through-tubing work displacing rig-based scope |
| Technology — Structural Laggard | Others, 3.60% CAGR | Slowest-growing technology line; legacy methods losing share to CT and slickline |
| End Use — Dominant | Oil & Gas, USD 12,115.64 Mn (98.48% share, 2025) | Effectively the entire revenue base in the base year |
| End Use — Fastest | Geothermal, 7.20% CAGR | Fastest-growing segment in the entire study; scale-up, re-completion, and scaling-mitigation work |
| Region — Dominant | Middle East & Africa | Largest 2025 revenue block; NOC-led production-assurance programmes |
| Region — Fastest | North America | Designated fastest-growing region for this report cycle |
| Country — Fastest | Argentina, 7.10% CAGR | Highest single-country growth rate in the model; Vaca Muerta re-entry and workover demand |
MARKET SIZE AND FORECAST (2019–2035)
MRFR sizes the well intervention market bottom-up, building from an installed-well census by basin, applying intervention-frequency factors differentiated by well type, completion vintage and drive mechanism, and pricing each workscope at prevailing regional day-rate and per-job benchmarks. Bottom-up output is then reconciled top-down against operator opex disclosures, service-company segment revenues, and regulatory well-activity filings, with variance above a tolerance band triggering a re-run of the frequency assumptions. 2025 is the base year; 2024 and earlier are historical; 2026 onward are forecast. The model is denominated in USD Million at constant prices, so nominal inflation and FX translation effects are excluded from the growth rates presented.




 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



