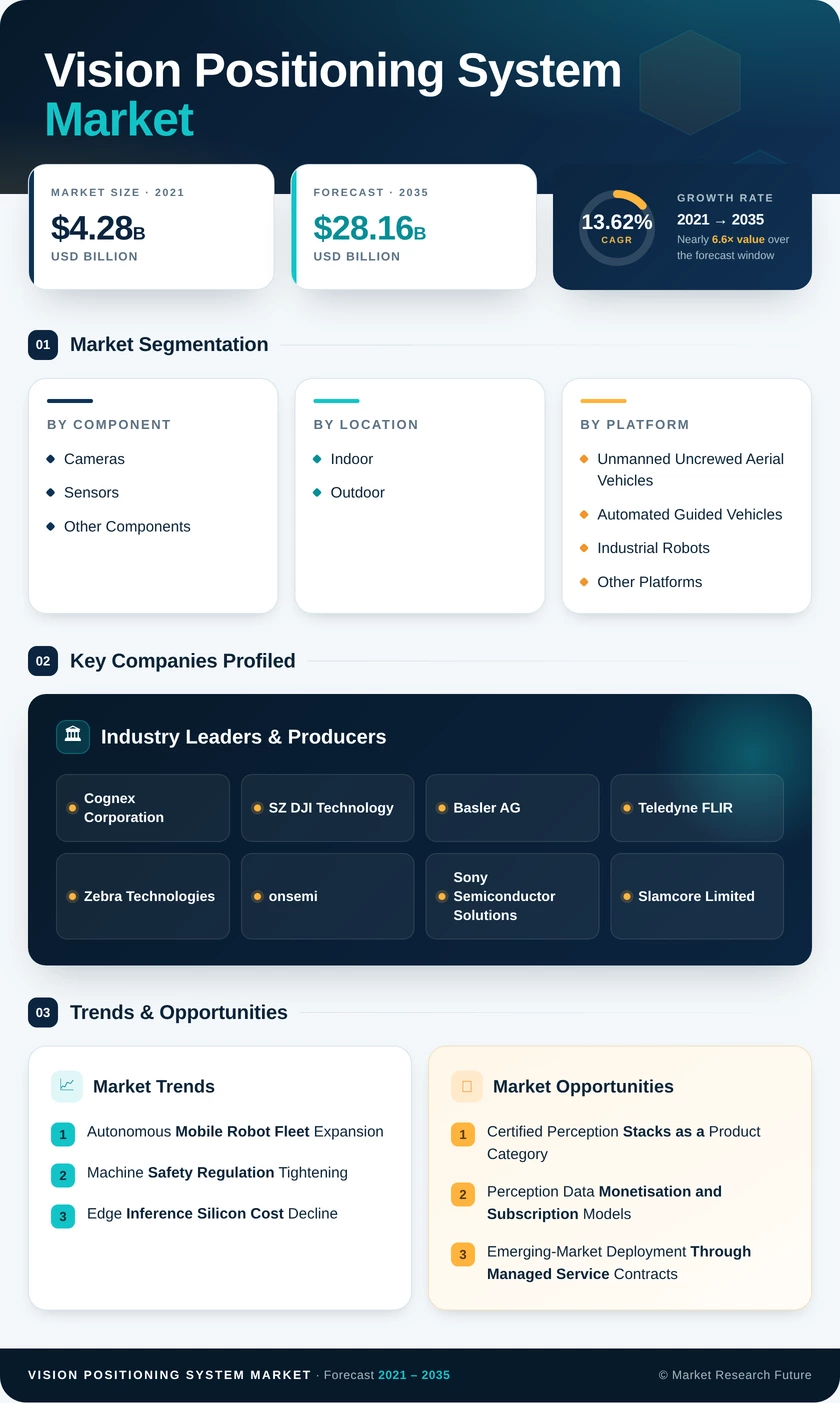
Vision Positioning System Market (2026 - 2035)

ID: MRFR/SEM/2313-HCR 200 Pages Aarti Dhapte Last Updated: September 15, 2026
Vision Positioning System Market Size, Share and Research Report By Component (Cameras, Sensors, Other Components), By Location (Indoor, Outdoor), By Platform (Unmanned Aerial Vehicles, Automated Guided Vehicles, Industrial Robots, Other Platforms), By End-User (Retail, Industrial and Manufacturing, Defense and Security, Transportation and Logistics, Healthcare, Other End-Users) And By Region (North America, Europe, Asia-Pacific, And Rest Of The World) – Industry Forecast Till 2035.
Vision Positioning System Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)13.62%
2025 Market SizeUSD 7.42 Billion
2035 Market SizeUSD 28.16 Billion
Key Players
Cognex Corporation
SZ DJI Technology
Basler AG
Teledyne FLIR
Zebra Technologies
onsemi
Opportunities
  • Certified Perception Stacks as a Product Category
  • Perception Data Monetisation and Subscription Models
  • Emerging-Market Deployment Through Managed Service Contracts
  1. 1 Market Summary | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Component | |
    2. 2.2 By Location | |
    3. 2.3 By Platform | |
    4. 2.4 By End-user | |
    5. 2.5 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2024) | |
    2. 3.2 Base Year Estimate (2025) | |
    3. 3.3 Forecast Market Size (2026–2035) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Autonomous Mobile Robot Fleet Expansion | |
    2. 4.2 Machine Safety Regulation Tightening | |
    3. 4.3 Edge Inference Silicon Cost Decline | |
    4. 4.4 Defense Demand for GNSS-Denied Navigation | |
    5. 4.5 E-commerce Fulfilment Density | |
    6. 4.6 Healthcare Asset and Workflow Tracking | |
    7. 4.7 Open-Source SLAM Toolchain Maturity | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Lighting and Environmental Variability | |
    2. 5.2 Calibration and Commissioning Labour Scarcity | |
    3. 5.3 Data Privacy Constraints on Continuous Imaging | |
    4. 5.4 Competing LiDAR Price Erosion | |
    5. 5.5 Legacy Brownfield Integration Complexity | |
  6. 6 Opportunities | |
    1. 6.1 Certified Perception Stacks as a Product Category | |
    2. 6.2 Perception Data Monetisation and Subscription Models | |
    3. 6.3 Emerging-Market Deployment Through Managed Service Contracts | |
    4. 6.4 Healthcare Workflow Localisation Beyond Asset Tracking | |
    5. 6.5 Outdoor Hybridisation for GNSS-Denied Commercial Fleets | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 United States | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 United Kingdom | | |
      2. 7.2.2 Germany | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordics | | |
      7. 7.2.7 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Australia | | |
      7. 7.3.7 New Zealand | | |
      8. 7.3.8 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East and Africa | | |
      1. 7.5.1 Middle East | | |
      2. 7.5.2 Saudi Arabia | | |
      3. 7.5.3 United Arab Emirates | | |
      4. 7.5.4 Turkey | | |
      5. 7.5.5 Rest of Middle East | | |
      6. 7.5.6 Africa | | |
      7. 7.5.7 South Africa | | |
      8. 7.5.8 Egypt | | |
      9. 7.5.9 Nigeria | | |
      10. 7.5.10 Rest of Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Foundation Models Reshape Perception Software Economics | |
    2. 8.2 Sensor Fusion Becomes the Default Architecture | |
    3. 8.3 Certification Infrastructure Matures Into a Gating Function | |
    4. 8.4 Energy and Sustainability Reporting Pulls Perception Into Scope | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Component | | |
      1. 9.1.1 Cameras | | |
      2. 9.1.2 Sensors | | |
      3. 9.1.3 Other Components | |
    2. 9.2 By Location | | |
      1. 9.2.1 Indoor | | |
      2. 9.2.2 Outdoor | |
    3. 9.3 By Platform | | |
      1. 9.3.1 Unmanned Aerial Vehicles | | |
      2. 9.3.2 Automated Guided Vehicles | | |
      3. 9.3.3 Industrial Robots | | |
      4. 9.3.4 Other Platforms | |
    4. 9.4 By End-user | | |
      1. 9.4.1 Retail | | |
      2. 9.4.2 Industrial and Manufacturing | | |
      3. 9.4.3 Defense and Security | | |
      4. 9.4.4 Transportation and Logistics | | |
      5. 9.4.5 Healthcare | | |
      6. 9.4.6 Other End-users | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions | | LIST OF TABLES | |
  15. TABLE 1 Vision Positioning System Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Vision Positioning System Market — Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 | |
  19. TABLE 5 Vision Positioning System Market Size, by Region, 2021–2035 (USD Billion) | |
  20. TABLE 6 North America Market Size, by Country, 2021–2035 (USD Billion) | |
  21. TABLE 7 Europe Market Size, by Country, 2021–2035 (USD Billion) | |
  22. TABLE 8 Asia-Pacific Market Size, by Country, 2021–2035 (USD Billion) | |
  23. TABLE 9 South America Market Size, by Country, 2021–2035 (USD Billion) | |
  24. TABLE 10 Middle East and Africa Market Size, by Country, 2021–2035 (USD Billion) | |
  25. TABLE 11 Vision Positioning System Market Size, by Component, 2021–2035 (USD Billion) | |
  26. TABLE 12 Vision Positioning System Market Size, by Location, 2021–2035 (USD Billion) | |
  27. TABLE 13 Vision Positioning System Market Size, by Platform, 2021–2035 (USD Billion) | |
  28. TABLE 14 Vision Positioning System Market Size, by End-user, 2021–2035 (USD Billion) | |
  29. TABLE 15 Competitive Benchmarking Matrix, 2026 | |
  30. TABLE 16 Company Profiles — Key Players | |
  31. TABLE 17 Recent Developments & Strategic Announcements, 2023–2025 | |
  32. TABLE 18 Report Scope & Methodology Summary | |
  33. TABLE 19 Detailed Sources and Citations Index | | LIST OF FIGURES | |
  34. FIGURE 1 Market Dynamics — Drivers, Restraints, and Opportunities | |
  35. FIGURE 2 Industry Value Chain Analysis | |
  36. FIGURE 3 Porter's Five Forces Analysis | |
  37. FIGURE 4 Market Size Trend and Forecast, 2021–2035 (USD Billion) | |
  38. FIGURE 5 Year-over-Year Growth Trajectory, 2022–2035 | |
  39. FIGURE 6 Market Share by Component, 2025 | |
  40. FIGURE 7 Market Share by Location, 2025 | |
  41. FIGURE 8 Market Share by Platform, 2025 | |
  42. FIGURE 9 Market Share by End-user, 2025 | |
  43. FIGURE 10 Regional Revenue Share Distribution, 2025 | |
  44. FIGURE 11 Regional CAGR Comparison, 2026–2035 | |
  45. FIGURE 12 Competitive Landscape Positioning Map, 2026 | |
  46. FIGURE 13 Top-Five Vendor Share Concentration, 2026

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By ComponentCameras, Sensors, Other ComponentsCameras (41.5% share, 2025)Sensors (12.9% CAGR)
By LocationIndoor, OutdoorIndoor (65.4% share, 2025)Outdoor (13.85% CAGR)
By PlatformUncrewed Aerial Vehicles, Automated Guided Vehicles, Industrial Robots, Other PlatformsUncrewed Aerial Vehicles (USD 3.19 Billion, 2025)Automated Guided Vehicles (21.7% CAGR)
By End-userRetail, Industrial and Manufacturing, Defense and Security, Transportation and Logistics, Healthcare, Other End-usersIndustrial and Manufacturing (34.6% share, 2025)Healthcare (16.3% CAGR)


Market Segmentation Overview

By Component

Sub-SegmentKey Trend
CamerasGlobal shutter and on-sensor inference displacing rolling shutter designs
SensorsDepth, inertial, and time-of-flight modalities consolidating into shared packages
Other ComponentsEdge processing modules and licensed software driving recurring revenue


Cameras lead this dimension at 41.5% of 2025 revenue because buyers now specify motion-tolerant global shutter imaging as a baseline requirement. That specification carries a price premium over the rolling shutter parts it replaced. Sensors grow fastest at a 12.9% CAGR as integrators abandon discrete inertial and depth modules in favour of pre-fused packages that cut calibration time. Other Components is where the business model is shifting, since processing boards increasingly ship with licensed perception software attached rather than as bare hardware.

By Location

Sub-SegmentKey Trend
IndoorMarkerless mapping replacing fiducial grids and magnetic tape guidance
OutdoorWeather-hardened enclosures and vision-aided inertial navigation maturing


Indoor holds 65.4% of 2025 revenue because controlled lighting lets suppliers guarantee accuracy with fewer redundant sensors, which keeps both hardware cost and conformity-assessment effort down for warehouse and hospital buyers. Outdoor compounds faster at 13.85% as defense-derived vision-aided inertial techniques transfer into ports, mines, and agricultural fleets that cannot rely on satellite positioning. The two are converging technically, with hybrid systems maintaining a single map across threshold crossings.

By Platform

Sub-SegmentKey Trend
Uncrewed Aerial VehiclesSatellite and vision fusion becoming standard on commercial airframes
Automated Guided VehiclesMulti-vendor fleet coordination and reconfigurable layouts
Industrial RobotsVision integration into collaborative cells and precision placement
Other PlatformsHandheld inspection and wearable systems tied to augmented reality.


Uncrewed Aerial Vehicles account for USD 3.19 billion of 2025 revenue, the largest platform pool, sustained by inspection contracts and widening beyond-visual-line-of-sight authorisations that make autonomous flight commercially routine. Automated Guided Vehicles grow fastest at 21.7% as fulfilment operators replace fixed conveyor infrastructure with fleets that can be re-tasked without civil works. Industrial Robots add steady volume through collaborative cells, while Other Platforms remain a smaller pool anchored in handheld inspection tools.

By End-user

Sub-SegmentKey Trend
RetailAutonomous shelf audit and planogram verification
Industrial and ManufacturingAssembly verification and scrap reduction in precision processes
Defense and SecurityRuggedised navigation for contested and satellite-denied environments
Transportation and LogisticsYard automation and high-throughput parcel sortation
HealthcareClinical asset location and workflow timing instrumentation
Other End-usersAgriculture, construction, and research deployment


Industrial and Manufacturing leads at 34.6% of 2025 revenue because scrap reduction and rework avoidance produce a return calculation that plant finance teams accept without extended pilots. Healthcare grows fastest at a 16.3% CAGR as hospitals extend beyond equipment location into workflow timing that connects to reimbursement quality measures. Defense and Security contributes outsized revenue per unit through ruggedisation premiums, while Retail conversion depends on store-format economics that vary widely by operator.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.