Vision Positioning System Market Summary
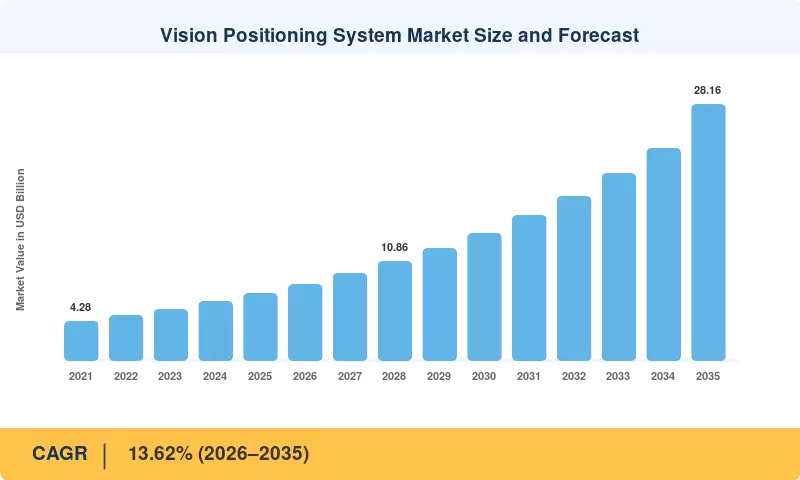
The Vision Positioning System Market reached USD 7.42 billion in 2025 and opens the forecast window at USD 8.38 billion in 2026, climbing to USD 28.16 billion by 2035 at a 13.62% CAGR. Two catalysts anchor that trajectory: the U.S. National Robotics Initiative's continued funding of perception-led autonomy research, and the European Machinery Regulation (EU) 2023/1230, which from January 2027 obliges manufacturers to document the safety logic of self-guided equipment. Both push camera-based localisation from an optional accessory into a compliance-grade subsystem [1][3].
Near-term spending is explained largely by replacement economics. Markerless simultaneous localization and mapping is running on embedded accelerators, replacing fiducial-marker grids, magnetic tape guidance and infrastructure-heavy ultra-wideband anchors. Warehouse operators have historically spent USD 180,000-USD 400,000 retrofitting a single facility with fixed guidance infrastructure. Software-defined perception stacks bring the cost down to a fraction. And since 2023, semiconductor suppliers have committed over USD 2.1 billion to edge inference silicon for this class of workload [4][7]. Therefore, the Vision Positioning System Market increases as much through substitution as through new deployment.
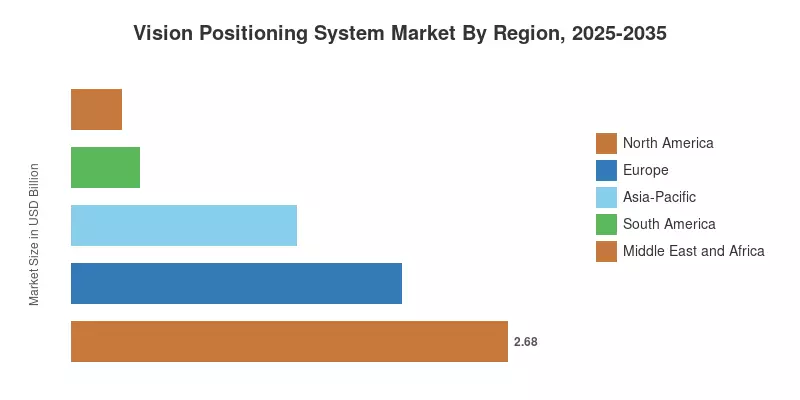
In terms of regions, North America accounts for 36.1% of the 2025 revenue, driven by defense procurement and a high density of installed base of fulfillment centers. The Asia-Pacific region is the fastest-growing at 18.65% through 2035, with Chinese, Japanese and Korean manufacturers electrifying and automating production lines in tandem. Europe holds second place in share, pushed by volume and regulatory pull. Through 2035, competitive advantage in the Vision Positioning System Market will go to vendors shipping validated, auditable perception—not just raw accuracy.
Key Report Takeaways
• By Component
- Cameras led the Vision Positioning System Market with a 41.5% revenue share in 2025, reflecting the migration of inference silicon into the imaging module itself.
- Sensors form the second-largest component pool, expanding at a 12.9% CAGR as inertial, depth, and time-of-flight modalities fuse into single housings.
• By Location
- Indoor deployments accounted for 65.4% of Vision Positioning System Market revenue in 2025, benefiting from stable lighting and bounded operating envelopes.
- Outdoor systems are advancing at a 13.85% CAGR as GNSS-denied navigation moves from defense pilots into commercial fleets.
• By Platform
- Uncrewed Aerial Vehicles captured USD 3.19 billion of 2025 revenue, the largest single platform pool.
- Automated Guided Vehicles register the fastest platform CAGR at 21.7% through 2035
• By End-user
- Industrial and Manufacturing held a 34.6% share of 2025 revenue, anchored in assembly verification and precision placement.
- Healthcare is the fastest-growing end-user vertical at a 16.3% CAGR
• By Region
- North America commanded 36.1% of Vision Positioning System Market revenue in 2025
- Asia-Pacific posts the steepest regional CAGR at 18.65% through 2035
- Middle East and Africa contributed USD 0.31 billion in 2025, the smallest but a fast-normalising base
Market Size and Forecast (2021–2035)
Estimates are derived from a combination of bottom-up unit shipment modeling across four classes of platform and top-down triangulation against reported segment revenue from twelve publicly listed vendors. Historical years are reconciled to customs data on movements of imaging modules and capital-expenditure disclosures from logistics and manufacturing operators. Forecast years are derived by fitting an adoption curve to regulatory compliance dates in the European Union and to disclosed automation budgets in Asia-Pacific.




 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA


