Virtualized Evolved Packet Core Market (2026 - 2035)

ID: MRFR/ICT/4167-CR 121 Pages Apoorva Priyadarshi Last Updated: September 22, 2026
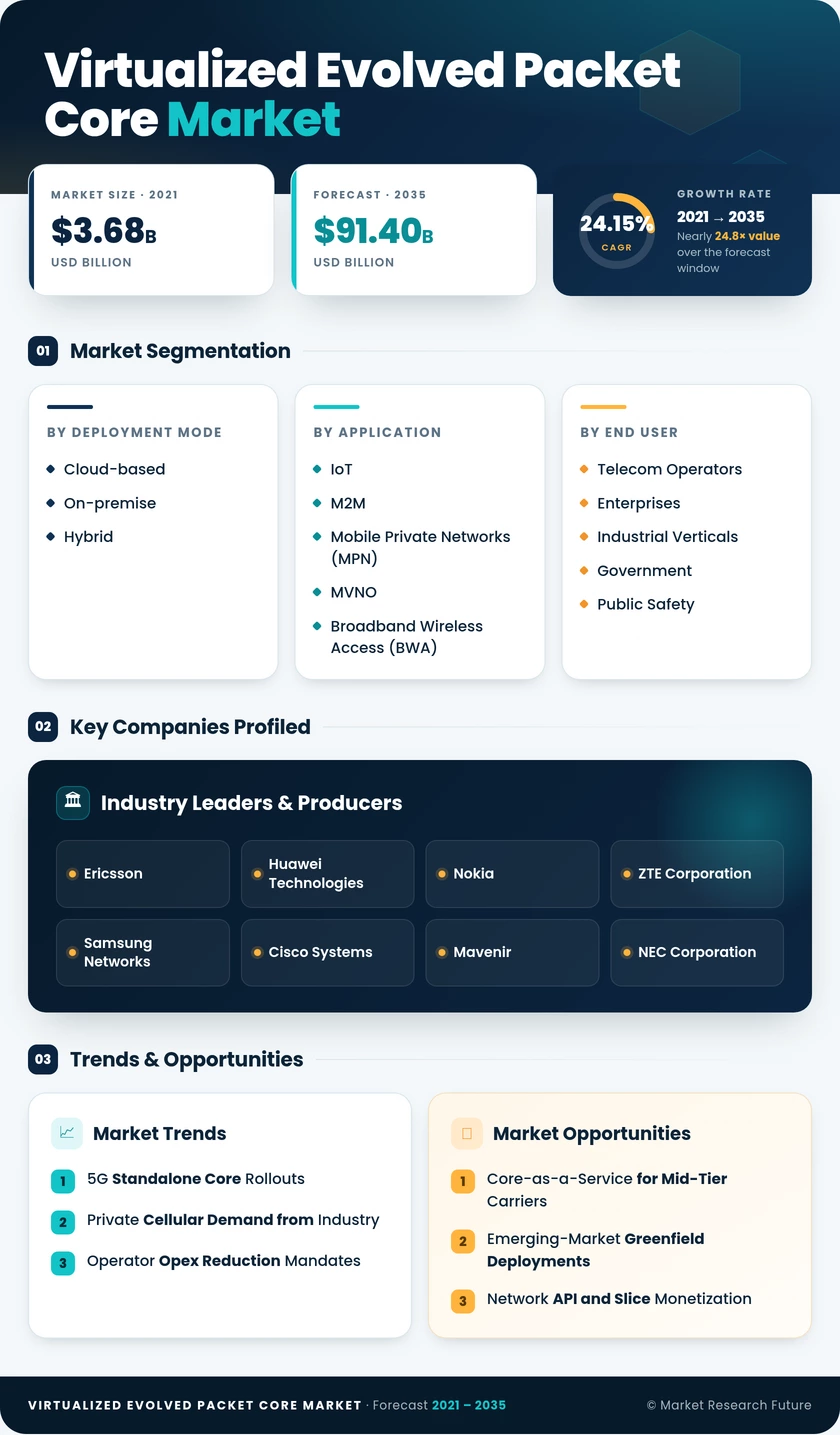
Virtualized Evolved Packet Core Market Size, Share and Research Report By Deployment Mode (Cloud-Based, On-Premise, and Hybrid), By Application (IoT and M2M, Mobile Private Networks (MPN) and MVNO, Broadband Wireless Access (BWA), LTE/VoLTE/VoWiFi, 5G Non-Standalone (NSA) Core, and 5G Standalone (SA) Core), By End User (Telecom Operators, Enterprises and Industrial Verticals, Government and Public Safety, Cloud Service Providers, and MVNE/MVNOs) – Industry Forecast Till 2035
Virtualized Evolved Packet Core Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)24.15%
2025 Market SizeUSD 9.62 Billion
2035 Market SizeUSD 91.40 Billion
Key Players
Ericsson
Huawei Technologies
Nokia
ZTE Corporation
Samsung Networks
Cisco Systems
Opportunities
  • Core-as-a-Service for Mid-Tier Carriers
  • Emerging-Market Greenfield Deployments
  • Network API and Slice Monetization
  1. 1 Market Summary | |
    1. 1.1 Study Assumptions and Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Deployment Mode | |
    2. 2.2 By Application | |
    3. 2.3 By End User | |
    4. 2.4 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2024) | |
    2. 3.2 Base Year Assessment (2025) | |
    3. 3.3 Forecast Market Size (2026–2035) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 5G Standalone Core Rollouts | |
    2. 4.2 Private Cellular Demand from Industry | |
    3. 4.3 Operator Opex Reduction Mandates | |
    4. 4.4 Hyperscaler Telecom Partnerships | |
    5. 4.5 Energy-Efficiency and ESG Mandates | |
    6. 4.6 Government Digital Infrastructure Programs | |
    7. 4.7 Network Slicing and API Monetization | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Cloud-Native Skills Shortage | |
    2. 5.2 Data Sovereignty and Residency Rules | |
    3. 5.3 Legacy Interworking Complexity | |
    4. 5.4 Security Exposure of Disaggregated Cores | |
    5. 5.5 Capital Constraints at Tier-2 Operators | |
  6. 6 Opportunities | |
    1. 6.1 Core-as-a-Service for Mid-Tier Carriers | |
    2. 6.2 Emerging-Market Greenfield Deployments | |
    3. 6.3 Network API and Slice Monetization | |
    4. 6.4 Sustainability-Linked Procurement in Europe | |
    5. 6.5 Defence and Public-Safety Dedicated Slices | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 United States | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 United Kingdom | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Russia | | |
      5. 7.2.5 Italy | | |
      6. 7.2.6 Spain | | |
      7. 7.2.7 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 Japan | | |
      3. 7.3.3 India | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 Australia and New Zealand | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East and Africa | | |
      1. 7.5.1 Middle East | | |
      2. 7.5.2 GCC Countries | | |
      3. 7.5.3 Turkey | | |
      4. 7.5.4 Rest of Middle East | | |
      5. 7.5.5 Africa | | |
      6. 7.5.6 South Africa | | |
      7. 7.5.7 Nigeria | | |
      8. 7.5.8 Egypt | | |
      9. 7.5.9 Rest of Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Autonomous Network Operations | |
    2. 8.2 Platform Economics and Software Licensing | |
    3. 8.3 Energy Intensity and Sustainability Reporting | |
    4. 8.4 Convergence Toward 6G-Ready Architectures | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Deployment Mode | | |
      1. 9.1.1 Cloud-based | | |
      2. 9.1.2 On-premise | | |
      3. 9.1.3 Hybrid | |
    2. 9.2 By Application | | |
      1. 9.2.1 IoT and M2M | | |
      2. 9.2.2 Mobile Private Networks (MPN) and MVNO | | |
      3. 9.2.3 Broadband Wireless Access (BWA) | | |
      4. 9.2.4 LTE/VoLTE/VoWiFi | | |
      5. 9.2.5 5G Non-Standalone (NSA) Core | | |
      6. 9.2.6 5G Standalone (SA) Core | |
    3. 9.3 By End User | | |
      1. 9.3.1 Telecom Operators | | |
      2. 9.3.2 Enterprises and Industrial Verticals | | |
      3. 9.3.3 Government and Public Safety | | |
      4. 9.3.4 Cloud Service Providers | | |
      5. 9.3.5 MVNE/MVNOs | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | |
  11. 11 Recent News and Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions | | LIST OF TABLES | |
  15. TABLE 1 Global Virtualized Evolved Packet Core Market Size and Forecast (USD Billion), 2021–2035 | |
  16. TABLE 2 Global Virtualized Evolved Packet Core Market — Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 | |
  19. TABLE 5 Global Market Size by Region (USD Billion), 2021–2035 | |
  20. TABLE 6 North America Market Size by Country (USD Billion), 2021–2035 | |
  21. TABLE 7 Europe Market Size by Country (USD Billion), 2021–2035 | |
  22. TABLE 8 Asia-Pacific Market Size by Country (USD Billion), 2021–2035 | |
  23. TABLE 9 South America Market Size by Country (USD Billion), 2021–2035 | |
  24. TABLE 10 Middle East and Africa Market Size by Country (USD Billion), 2021–2035 | |
  25. TABLE 11 Global Market Size by Deployment Mode (USD Billion), 2021–2035 | |
  26. TABLE 12 Global Market Size by Application (USD Billion), 2021–2035 | |
  27. TABLE 13 Global Market Size by End User (USD Billion), 2021–2035 | |
  28. TABLE 14 Competitive Benchmarking Matrix, 2026 | |
  29. TABLE 15 Company Profiles — Key Players | |
  30. TABLE 16 Recent Developments and Strategic Announcements, 2023–2025 | |
  31. TABLE 17 Report Scope and Methodology Summary | |
  32. TABLE 18 Detailed Sources and Citations | |
  33. TABLE 19 North America Market Size by Deployment Mode (USD Billion), 2021–2035 | |
  34. TABLE 20 Europe Market Size by Application (USD Billion), 2021–2035 | |
  35. TABLE 21 Asia-Pacific Market Size by End User (USD Billion), 2021–2035 | |
  36. TABLE 22 Segmentation Quick Reference Matrix | | LIST OF FIGURES | |
  37. FIGURE 1 Market Dynamics — Drivers, Restraints and Opportunities | |
  38. FIGURE 2 Industry Value Chain Analysis | |
  39. FIGURE 3 Porter's Five Forces Analysis | |
  40. FIGURE 4 Global Market Size Trend (USD Billion), 2021–2035 | |
  41. FIGURE 5 Year-over-Year Growth Trajectory, 2021–2035 | |
  42. FIGURE 6 Market Share by Deployment Mode, 2025 | |
  43. FIGURE 7 Market Share by Application, 2025 | |
  44. FIGURE 8 Market Share by End User, 2025 | |
  45. FIGURE 9 Regional Market Share Distribution, 2025 | |
  46. FIGURE 10 Regional CAGR Comparison, 2026–2035 | |
  47. FIGURE 11 Country-Level Contribution Within Asia-Pacific, 2025 | |
  48. FIGURE 12 Competitive Landscape — Revenue Share Positioning, 2026 | |
  49. FIGURE 13 Vendor Strategic Positioning Matrix | |
  50. FIGURE 14 Forecast Scenario Analysis, 2026–2035

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Deployment ModeCloud-based; On-premise; HybridCloud-based (58.9% share, 2025)Hybrid (27.4% CAGR)
By ApplicationIoT and M2M; Mobile Private Networks (MPN) and MVNO; Broadband Wireless Access (BWA); LTE/VoLTE/VoWiFi; 5G Non-Standalone (NSA) Core; 5G Standalone (SA) CoreLTE/VoLTE/VoWiFi (50.1% share, 2025)5G Standalone (SA) Core (31.6% CAGR)
By End UserTelecom Operators; Enterprises and Industrial Verticals; Government and Public Safety; Cloud Service Providers; MVNE/MVNOsTelecom Operators (66.2% share, 2025)Enterprises and Industrial Verticals (30.7% CAGR)


Market Segmentation Overview

By Deployment Mode

Sub-SegmentKey Trend
Cloud-basedHyperscaler telecom regions absorb production control-plane workloads
On-premiseRetained where lawful-intercept and latency budgets prohibit offloading
HybridSplit control and user planes satisfy residency rules without losing cloud economics


Cloud-based deployment leads because carriers now accept public-cloud regions for production control-plane functions, a threshold crossed once roaming and charging workloads proved stable there. Hybrid grows fastest as German, Indian, and Saudi residency rules force user-plane functions onto national soil while operators still want elastic control planes. On-premise holds only where lawful-intercept custody or hard latency ceilings leave no alternative, and its share compresses each year as regulators accept certified hybrid architectures.

By Application

Sub-SegmentKey Trend
IoT and M2MDeterministic latency profiles unlock industrial robotics workloads
Mobile Private Networks (MPN) and MVNOCampus spectrum licences drive dedicated core demand
Broadband Wireless Access (BWA)Standalone capacity enables fibre substitution economics
LTE/VoLTE/VoWiFiSustains volume as 4G subscribers migrate gradually
5G Non-Standalone (NSA) CoreTransitional architecture with declining new-build share
5G Standalone (SA) CoreService-based architecture enables slicing and network APIs


LTE/VoLTE/VoWiFi remains the revenue anchor because 4G still carries most subscribers, and operators cannot decommission it while regulators protect legacy voice. 5G Standalone (SA) Core grows fastest since slice-attribute pricing and network APIs are technically impossible on non-standalone architecture, which converts core investment into a revenue prerequisite. 5G Non-Standalone (NSA) Core is already in structural decline for new builds, and Broadband Wireless Access rides standalone capacity to compete on fibre-adjacent economics.

By End User

Sub-SegmentKey Trend
Telecom OperatorsNational modernization programs and licence obligations sustain volume
Enterprises and Industrial VerticalsPrivate cellular replaces plant wireless in manufacturing and logistics
Government and Public SafetyDedicated slices replace separate mission-critical networks
Cloud Service ProvidersPackaged core-as-a-service targets mid-tier carriers
MVNE/MVNOsCloud-native cores enable rapid vertical niche launches


Telecom Operators remain dominant because licence obligations and coverage mandates make core modernization non-discretionary at national scale. Enterprises and Industrial Verticals grow fastest, driven by manufacturers and port operators who need contractual latency guarantees that wireless LAN cannot provide. Cloud Service Providers occupy an unusual position — competing as suppliers of packaged cores while MVNE/MVNOs buy that same capability to launch vertical propositions in weeks rather than quarters.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.