Vascular Stents Market

Vascular Stents Market Size, Growth Research Report By Type (Drug-Eluting Stents, Bare-Metal Stents, Biodegradable Stents), By Application (Coronary Artery Disease, Peripheral Vascular Disease, Carotid Artery Disease), By Material (Metal Stents, Polymer Stents, Composite Stents), By End Use (Hospitals, Cardiac Catheterization Labs, Ambulatory Surgical Centers) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Competitor Industry Analysis and Trends Forecast Till 2035
ID: MRFR/MED/0899-HCR 95 Pages Satyendra Maurya, Kinjoll Dey Last Updated: September 29, 2026
Vascular Stents Market
Market Size
Forecast Period2025 - 2035
CAGR (2025 - 2035)3.61%
2024 Market Size$ 6.92 Billion
2025 Market Size$ 7.17 Billion
2035 Market Size$ 10.22 Billion
Key Players
Medtronic
Boston Scientific
Abbott Laboratories
B. Braun Melsungen AG
Terumo Corporation
Cordis Corporation
Opportunities
  • Rising Prevalence of Cardiovascular Diseases
  • Regulatory Support and Reimbursement Policies
  • Technological Advancements in Vascular Stents

Vascular Stents Market Summary

As per Market Research Future analysis, the Vascular Stents Market Size was estimated at 6.921 USD Billion in 2024. The Vascular Stents industry is projected to grow from 7.171 USD Billion in 2025 to 10.22 USD Billion by 2035, exhibiting a CAGR of 3.61% during the forecast period 2025 - 2035. North America market with the largest revenue share of 44.79% in 2024.

Key Market Trends & Highlights

The market is experiencing robust growth driven by technological advancements and increasing healthcare demands.

  • North America remains the largest market for vascular stents, driven by advanced healthcare infrastructure and high patient awareness.
  • The Asia-Pacific region is emerging as the fastest-growing market, fueled by rising healthcare investments and a growing population.
  • Drug-eluting stents dominate the market, while bare-metal stents are witnessing rapid growth due to their cost-effectiveness.
  • Key market drivers include technological advancements in vascular stents and the rising prevalence of cardiovascular diseases.

Market Size & Forecast

2024 Market Size 6.921 (USD Billion)
2035 Market Size 10.22 (USD Billion)
CAGR (2025 - 2035) 3.61%

Major Players

Medtronic (US), Boston Scientific (US), Abbott Laboratories (US), B. Braun Melsungen AG (DE), Terumo Corporation (JP), Cordis Corporation (US), Cook Medical (US), Johnson & Johnson (US), Stryker Corporation (US)

Vascular Stents Market Drivers

Rising Prevalence of Cardiovascular Diseases

The increasing incidence of cardiovascular diseases is a primary driver for the market. As lifestyle-related factors such as obesity, sedentary behavior, and unhealthy diets become more prevalent, the demand for vascular interventions is expected to rise. Data indicates that cardiovascular diseases remain a leading cause of mortality worldwide, necessitating effective treatment options.
 
This trend is likely to propel the adoption of vascular stents, as they are critical in managing conditions such as coronary artery disease. The growing awareness of cardiovascular health and the importance of early intervention may further stimulate market growth, as healthcare systems prioritize preventive measures and treatment options in the market.

Regulatory Support and Reimbursement Policies

Regulatory support and favorable reimbursement policies are crucial drivers for the market. Governments and health authorities are increasingly recognizing the importance of vascular interventions in improving patient outcomes. As a result, there is a trend towards streamlined approval processes for new stent technologies, which may encourage innovation and market entry.
 
Additionally, favorable reimbursement frameworks are likely to enhance the affordability and accessibility of vascular stents, making them more appealing to healthcare providers and patients alike. This supportive regulatory environment could stimulate growth in the market, as stakeholders seek to capitalize on emerging opportunities.

Technological Advancements in Vascular Stents

The market is experiencing a notable transformation due to rapid technological advancements. Innovations such as drug-eluting stents and bioresorbable stents are enhancing patient outcomes and reducing complications. The introduction of advanced materials and coatings is improving stent performance, leading to higher adoption rates among healthcare providers.
 
According to recent data, the market for drug-eluting stents is projected to grow significantly, driven by their effectiveness in preventing restenosis. Furthermore, the integration of digital technologies, such as imaging and monitoring systems, is likely to enhance procedural precision and patient safety. As these technologies evolve, they may contribute to a more efficient healthcare delivery system, ultimately benefiting the market.

Aging Population and Increased Healthcare Expenditure

The aging population is a significant factor influencing the market. As individuals age, the risk of developing cardiovascular diseases escalates, leading to a higher demand for vascular interventions. This demographic shift is accompanied by increased healthcare expenditure, as governments and private sectors invest more in advanced medical technologies.
 
Reports suggest that healthcare spending is projected to rise, particularly in regions with aging populations, thereby enhancing the accessibility of vascular stents. This trend may lead to a more robust market environment, as healthcare providers seek to adopt innovative solutions to meet the needs of older patients in the market.

Growing Awareness and Education on Cardiovascular Health

The growing awareness and education surrounding cardiovascular health are pivotal in shaping the market. Public health campaigns and educational initiatives are increasingly informing individuals about the risks associated with cardiovascular diseases and the importance of early detection and treatment.
 
This heightened awareness is likely to lead to an increase in screening and diagnostic procedures, subsequently driving demand for vascular stents. Furthermore, as patients become more informed about their treatment options, they may actively seek out vascular interventions, thereby contributing to market growth. The emphasis on cardiovascular health education may play a vital role in the future trajectory of the market.
Market Segment Insights

By Type:

The market is primarily dominated by Drug-Eluting Stents, which hold the largest market share due to their advanced capabilities in releasing medication that reduces the risk of restenosis. Bare-Metal Stents, while traditionally established in the market, are now witnessing increasing competition from Biodegradable Stents. This shift is reflective of changing preferences in treatment methodologies among healthcare providers and patients.

By Application:

The Vascular Stents Market is segmented primarily into three key categories: Coronary Artery Disease (CAD), Peripheral Vascular Disease (PVD), and Carotid Artery Disease (CAD). Among these, the CAD segment holds the largest market share, reflecting its significant impact on cardiovascular health globally. In contrast, PVD is witnessing rapid growth as increasing lifestyle-related ailments and an aging population drive demand for advanced treatment options.

By Material:

In the vascular stents market, the material segment exhibits a diverse distribution among metal, polymer, and composite stents. Metal stents have established themselves as the dominant player due to their durability and widespread clinical acceptance. They account for a significant share of the market, largely because of their proven efficacy in various vascular procedures. In contrast, polymer stents are gaining traction, fueled by advancements in material science and increasing demand for bioresorbable options that minimize long-term complications. Growth trends indicate that polymer stents are emerging as the fastest-growing segment as they present unique features such as biocompatibility and reduced risk of restenosis. Factors driving this growth include an increasing preference for minimally invasive procedures and ongoing innovations in polymers that enhance stent performance. As healthcare providers continue to seek safer alternatives, polymer stents are poised to expand their market share rapidly, complementing the established presence of metal stents.

By End Use:

Hospitals hold a significant portion of the market share as they are the primary setting for various cardiovascular procedures. With state-of-the-art infrastructure and advanced medical technology, hospitals provide comprehensive treatment options that cater to a large patient demographic, contributing to their dominant position in this segment. Cardiac catheterization labs are also prominently featured, as they specialize in minimally invasive procedures and are essential in managing patients with complex cardiovascular issues. These labs are gaining traction due to their ability to perform stent placements efficiently, thus enhancing their market relevance.

Get more detailed insights about Vascular Stents Market

Regional Insights

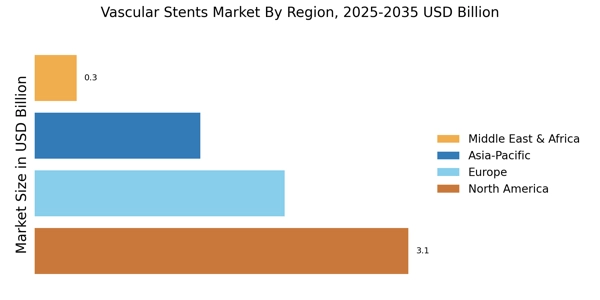
North America dominated the global Vascular Stents Market in 2024, reaching a market size of USD 3.1 Billion. This dominance can be attributed to advanced healthcare infrastructure and high patient awareness. Europe follows with a significant valuation of 2.0 USD Billion in 2023, expected to grow to 2.8 USD Billion, driven by an increasing elderly population and funding for vascular treatments.

In the APAC region, where rapid urbanization and growing healthcare expenditure have taken root, the market was valued at 1.5 USD Billion in 2023 and may reach 2.0 USD Billion by 2032.South America represents an emerging market with a valuation of 0.8 USD Billion in 2023, anticipated to grow to 1.1 USD Billion, driven by rising cardiac diseases and healthcare access improvements. MEA, albeit the smallest market of 0.38 USD Billion in 2023, is showing potential due to increasing investments in healthcare infrastructure, expected to reach 0.5 USD Billion by 2032.

Vascular Stents Market Regional Image

Key Players and Competitive Insights

The Vascular Stents Market is a dynamic and competitive landscape driven by technological advancements, increasing prevalence of cardiovascular diseases, and rising demand for minimally invasive procedures. Various companies compete by innovating new materials and designs that enhance the performance and longevity of vascular stents. Additionally, strategic partnerships, mergers, and acquisitions among manufacturers contribute to increased market competitiveness. Companies are also focusing on expanding their geographical presence to tap into emerging markets, which offer opportunities for growth.
 
Competitive strategies such as product differentiation, distribution channel optimization, and aggressive marketing drive the market forward. The competition is fierce as firms seek to capture significant market share by addressing the evolving needs of hospitals and healthcare providers worldwide.Stryker Corporation is a prominent player in the market, well-known for its commitment to quality and innovation. The company has established a strong presence through a comprehensive portfolio of cutting-edge vascular stenting solutions designed for various patient needs. Stryker's strengths lie in its strong research and development capabilities, enabling the company to introduce advanced stent technologies that promise enhanced patient outcomes. 
 
The company’s focus on developing stents that prioritize patient safety and efficacy positions it favorably within the market. Furthermore, Stryker's ability to leverage its extensive distribution network allows for expansive market reach and accessibility of its products across different regions, thereby reinforcing its competitive advantage.Gore Medical is recognized for its significant contributions to the market, particularly known for its innovative approaches to vascular surgery.
 
The company has developed a reputation for high-quality products that are both reliable and effective in various clinical settings. Gore Medical's key strengths include its advanced engineering expertise and dedication to research that facilitates constant product improvement. The company also emphasizes physician education and training, ensuring healthcare providers are well-informed about the use and benefits of its vascular stents. Gore Medical's commitment to developing materials that minimize complications while enhancing patient recovery times has solidified its standing in the market, allowing it to maintain a competitive edge over other industry players.

Key Companies in the Vascular Stents Market include

Recent Industry Developments

September 2026, This is the first sirolimus drug-eluting balloon approved in the U.S. It is approved for coronary in-stent restenosis and leaves no permanent implant. The approval is supported by a trial showing non-inferiority to usual care, which included 80% repeat drug-eluting stents. Target lesion failure was 15.2% versus 13.5%. Cordis has also completed enrollment in a 960-patient trial comparing the balloon with drug-eluting stents in small coronary vessels. It is a balloon, not a stent, but it competes directly with repeat stenting for a condition that accounts for about 10% of U.S. PCIs. Cordis is also entering the U.S. coronary drug-coated balloon market, where Boston Scientific's Agent has been approved since 2024. (Source: citoday.com)

August 2026, Enrollment is complete at 335 patients in the U.S. pivotal trial, which is testing the investigational system in severely calcified, de novo coronary lesions before stent placement. Abbott's Vascular president said the company is now working toward a premarket approval submission. It is an R&D milestone, not an approval. It shows Abbott building vessel-preparation technology around its Xience stent franchise, where severe calcium can make stent delivery and expansion harder. (Source: cardiovascularnews.com)

June 2026, The program has two single-arm IDE studies, one transcarotid and one transfemoral. They are testing a purpose-built carotid lithotripsy platform for calcified carotid arteries before stenting, in patients at high risk for endarterectomy. If it succeeds, it would extend J&J's Shockwave lithotripsy technology into carotid artery stenting, alongside the stent systems from Medtronic and Terumo. The system is investigational. (Source: jnj.com)

Future Outlook

Vascular Stents Market Future Outlook

The Vascular Stents Market is projected to grow at a 3.61% CAGR from 2025 to 2035, driven by technological advancements, increasing cardiovascular diseases, and rising healthcare expenditures.

New opportunities lie in:

  • Development of bioresorbable stents for enhanced patient outcomes. Expansion into emerging markets with tailored product offerings. Integration of digital health solutions for remote patient monitoring.

By 2035, the market is expected to achieve robust growth and innovation.

Market Segmentation

Vascular Stents Market Type Outlook

  • Drug-Eluting Stents
  • Bare-Metal Stents
  • Biodegradable Stents

Vascular Stents Market End Use Outlook

  • Hospitals
  • Cardiac Catheterization Labs
  • Ambulatory Surgical Centers

Vascular Stents Market Material Outlook

  • Metal Stents
  • Polymer Stents
  • Composite Stents

Vascular Stents Market Application Outlook

  • Coronary Artery Disease
  • Peripheral Vascular Disease
  • Carotid Artery Disease

Report Scope

MARKET SIZE 2024 6.921(USD Billion)
MARKET SIZE 2025 7.171(USD Billion)
MARKET SIZE 2035 10.22(USD Billion)
COMPOUND ANNUAL GROWTH RATE (CAGR) 3.61% (2025 - 2035)
REPORT COVERAGE Revenue Forecast, Competitive Landscape, Growth Factors, and Trends
BASE YEAR 2024
Market Forecast Period 2025 - 2035
Historical Data 2019 - 2024
Market Forecast Units USD Billion
Key Companies Profiled Medtronic (US), Boston Scientific (US), Abbott Laboratories (US), B. Braun Melsungen AG (DE), Terumo Corporation (JP), Cordis Corporation (US), Cook Medical (US), Johnson & Johnson (US), Stryker Corporation (US)
Segments Covered Type, Application, Material, End Use, Regional
Key Market Opportunities Advancements in biodegradable stent technology present new opportunities in the market.
Key Market Dynamics Technological advancements and regulatory changes drive innovation and competition in the market.
Countries Covered North America, Europe, APAC, South America, MEA

Frequently Asked Questions

What is the projected market valuation of the Vascular Stents Market by 2035?
The market is projected to reach a valuation of 10.22 USD Billion by 2035.
What was the market valuation of the market in 2024?
In 2024, the overall market valuation was 6.921 USD Billion.
What is the expected CAGR for the Vascular Stents Market during the forecast period 2025 - 2035?
The expected CAGR for the market during the forecast period 2025 - 2035 is 3.61%.
Which companies are considered key players in the market?
Key players in the market include Medtronic, Boston Scientific, Abbott Laboratories, and others.
What are the projected valuations for Drug-Eluting Stents by 2035?

The projected valuation for Drug-Eluting Stents is expected to reach 3.12 USD Billion by 2035.

How do Bare-Metal Stents perform in terms of market valuation by 2035?

Bare-Metal Stents are projected to achieve a market valuation of 3.12 USD Billion by 2035.

What is the expected market size for Biodegradable Stents by 2035?

Biodegradable Stents are anticipated to reach a market size of 4.98 USD Billion by 2035.

What is the projected market size for Coronary Artery Disease applications by 2035?

The market size for Coronary Artery Disease applications is projected to reach 3.0 USD Billion by 2035.

What is the expected valuation for Peripheral Vascular Disease applications by 2035?

The expected valuation for Peripheral Vascular Disease applications is 3.0 USD Billion by 2035.

What are the projected valuations for different materials used in stents by 2035?

Composite Stents are projected to reach a valuation of 4.22 USD Billion by 2035.

Author
Author Author Profile Satyendra Maurya LinkedIn Research Analyst
An accomplished research analyst with high proficiency in market forecasting, data visualization, competitive benchmarking, and others. He holds a pronounced track record in research and consulting projects for sectors such as life sciences, medical devices, and healthcare IT. His capabilities in qualitative and quantitative analysis have resulted in positive client outcomes. Working on niche market trends, opportunities, sales, and forecasted value is part of his skill set.
Co-Author Co-Author Profile Kinjoll Dey LinkedIn Senior Research Analyst
He is an extremely curious individual currently working in Healthcare and Medical Devices Domain. Kinjoll is comfortably versed in data centric research backed by healthcare educational background. He leverages extensive data mining and analytics tools such as Primary and Secondary Research, Statistical Analysis, Machine Learning, Data Modelling. His key role also involves Technical Sales Support, Client Interaction and Project management within the Healthcare team. Lastly, he showcases extensive affinity towards learning new skills and remain fascinated in implementing them.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of global regulatory databases for cardiovascular devices, peer-reviewed interventional cardiology literature, clinical trial registries, and authoritative cardiovascular health organizations. Key sources included the US Food & Drug Administration (FDA) Center for Devices and Radiological Health (CDRH) Premarket Approval (PMA) database and MAUDE (Manufacturer and User Facility Device Experience) database, European Medicines Agency (EMA) medical device regulations and notified body certifications, National Institutes of Health (NIH) National Heart, Lung, and Blood Institute (NHLBI) cardiovascular research initiatives, Centers for Disease Control and Prevention (CDC) National Center for Health Statistics cardiovascular disease surveillance, Centers for Medicare & Medicaid Services (CMS) procedure utilization databases, Healthcare Cost and Utilization Project (HCUP) National Inpatient Sample for PCI and stenting procedures, Society for Cardiovascular Angiography and Interventions (SCAI) procedural standards and registries, American College of Cardiology (ACC) National Cardiovascular Data Registry (NCDR) CathPCI Registry, European Society of Cardiology (ESC) Euro Heart Survey, World Health Organization (WHO) Global Burden of Disease cardiovascular disease statistics, Transcatheter Cardiovascular Therapeutics (TCT) clinical data repositories, National Center for Biotechnology Information (NCBI/PubMed) for systematic reviews on drug-eluting vs. bare-metal stent outcomes, Journal of the American College of Cardiology (JACC), European Heart Journal, and Catheterization and Cardiovascular Interventions peer-reviewed publications. These sources were utilized to collect PCI procedure volumes, stent implantation trends, regulatory classification data, clinical safety and efficacy studies (including late stent thrombosis and restenosis rates), demographic epidemiology of coronary and peripheral artery disease, reimbursement codes (CPT, DRG, HCPCS), and competitive landscape intelligence across drug-eluting stents (DES), bare-metal stents (BMS), bioresorbable vascular scaffolds (BVS), and peripheral vascular stent technologies.


Primary Research

Interviews with both supply-and demand-side players were conducted as part of the primary research process in order to get vascular stent ecosystem-specific qualitative and quantitative data. From the supply side, we heard from CEOs, VPs of R&D and clinical affairs, heads of regulatory strategies, and commercial/general managers from stent delivery system OEMs, suppliers of nitinol/cobalt-chromium raw materials, manufacturers of coronary and peripheral stents, and stent delivery systems. Board-certified interventional cardiologists, vascular surgeons, interventional radiologists, medical directors of catheterization laboratories (cath labs), administrators of hospital cardiovascular service lines, purchasing managers for hospital cardiovascular devices, clinical resource specialists from group purchasing organizations (GPOs), and administrators of ambulatory surgical centers (ASCs) that specialize in outpatient percutaneous coronary intervention (PCI) and peripheral interventions made up the demand-side sources. The market segmentation was confirmed by primary research across different types of stents, applications, and materials. The timelines for next-generation stents, including magnesium-based bioresorbable scaffolds and polymer-free DES, were also confirmed. Insights were gathered regarding cath lab adoption patterns, value-based purchasing strategies, stent pricing dynamics, and reimbursement pathway evolution under bundled payment models.

Primary Respondent Breakdown:

By Designation: C-level Primaries (40%), Director Level (25%), Others (35%)

By Region: North America (40%), Europe (25%), Asia-Pacific (25%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through revenue triangulation and procedural volume analysis specific to cardiovascular interventions. The methodology included:

Identification of 35+ key manufacturers across North America, Europe, Asia-Pacific, and Latin America specializing in coronary stents, peripheral vascular stents, and bioresorbable scaffolds

Product mapping across drug-eluting stents (limus-class and paclitaxel-eluting), bare-metal stents, bioresorbable vascular scaffolds, covered stents, and self-expanding nitinol peripheral stents

Analysis of reported and modeled annual revenues specific to vascular stent portfolios, including original equipment manufacturer (OEM) and private label arrangements

Coverage of manufacturers representing 75-80% of global market share in 2024, including dominant players in the coronary DES segment and emerging specialists in bioresorbable technologies

Extrapolation using bottom-up (procedure volume × average selling price by country, accounting for dual antiplatelet therapy bundled vs. unbundled pricing) and top-down (manufacturer revenue validation, distributor markup analysis, and GPO contract value assessment) approaches to derive segment-specific valuations for coronary stents, peripheral arterial disease (PAD) stents, and carotid artery stents

Cross-validation against CMS utilization data for inpatient PCI procedures, NCDR registry volumes, and Eurostat healthcare procedure statistics to ensure accuracy in penetration rates and stent-to-procedure ratios across hospital inpatient, hospital outpatient, and freestanding cath lab settings

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.