Used Cooking Oil Market (2026 - 2035)

Used Cooking Oil (UCO) Market Size, Share, Industry Trend & Analysis Research Report By Source (HoReCa, Household Kitchens, Food Processing Plants), By End Use (Biodiesel and HVO, Oleo-Chemicals, Animal Feed, Others), By Geography (North America, South America, Europe, Asia-Pacific, Middle East and Africa) - Forecast to 2035
ID: MRFR/FnB/3099-CR 200 Pages Snehal Singh Last Updated: November 08, 2026
Used Cooking Oil Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.45%
2025 Market SizeUSD 7.71 Billion
2035 Market SizeUSD 14.41 Billion
Key Players
Darling Ingredients
Neste Oyj
Greenergy Fuels
Olleco
Argent Energy Group
Baker Commodities
Opportunities
  • Sovereign SAF Hubs in the Gulf
  • Co-Processing Retrofits
  • Emerging-Market Formalisation

Used Cooking Oil Market Summary

The Used Cooking Oil Market closed 2025 at USD 7.71 billion and enters the forecast window at USD 8.21 billion in 2026, expanding to USD 14.41 billion by 2035 at a 6.45% CAGR. Two policy engines explain most of that trajectory. Europe's Renewable Energy Directive III pushed the 2030 transport renewables target to 29%, while the US Clean Fuel Production Credit under Section 45Z began paying producers up to USD 1.00 per gallon for low-carbon-intensity diesel from January 2025 [1][2]. Both instruments reward waste-derived feedstock over virgin vegetable oil, and collectors have repriced accordingly.

Collection itself is being re-engineered. Manual grease-trap pickups, paper manifests and informal cash-based aggregation are giving way to sensor-fitted storage bins, GPS-verified route software and blockchain-anchored chain-of-custody records demanded by ISCC EU certification auditors. Neste alone committed roughly USD 2.1 billion to its Rotterdam expansion, lifting renewable capacity toward 6.8 million tonnes annually and tightening competition for every litre entering the Used Cooking Oil Market [3].

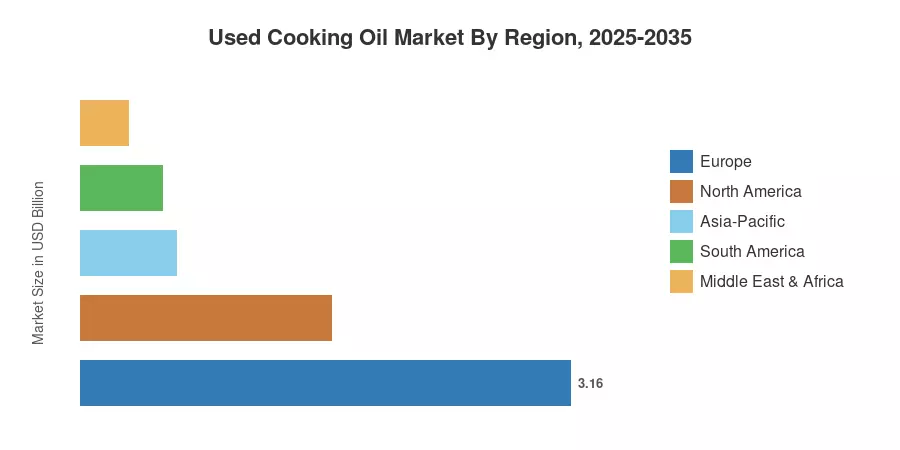
Regionally, Europe holds 41.0% of 2025 value on the strength of mandate depth and mature rendering networks. Asia-Pacific grows fastest at 8.1% CAGR as China, Indonesia and Malaysia shift from raw export to domestic processing. North America contributed USD 1.62 billion in 2025, anchored by RIN economics. Through 2035, aviation demand will decide who captures the margin across the Used Cooking Oil Market.


Key Report Takeaways

Highlights below summarise where value concentrates across the Used Cooking Oil Market.

• By Source

  • HoReCa channels account for 52.5% of 2025 global volume value, reflecting predictable per-outlet yields
  • Household Kitchens represent the fastest-expanding source at 7.9% CAGR through 2035
  • Food Processing Plants contributed USD 1.58 billion in 2025 within the Used Cooking Oil Market

• By End Use

  • Biodiesel and HVO absorb 68.0% of collected volume
  • Oleo-Chemicals generated USD 1.19 billion in 2025
  • Animal Feed applications grow at 3.4% CAGR, constrained by EU feed-ban rules

• By Region

  • Europe leads with 41.0% revenue share
  • Asia-Pacific posts the strongest regional CAGR at 8.1%
  • Middle East & Africa remains the smallest contributor to the Used Cooking Oil Market at 4.0% share


Market Size and Forecast (2021–2035)

Estimates below blend collector-level volume reporting, customs and trade-flow data for HS 1518, certified sustainable feedstock registries, and revenue triangulation across 40+ processors. Prices are weighted by regional CIF benchmarks and converted to constant-currency USD. The Used Cooking Oil Market series is reconciled annually against biodiesel and HVO plant utilisation rates.
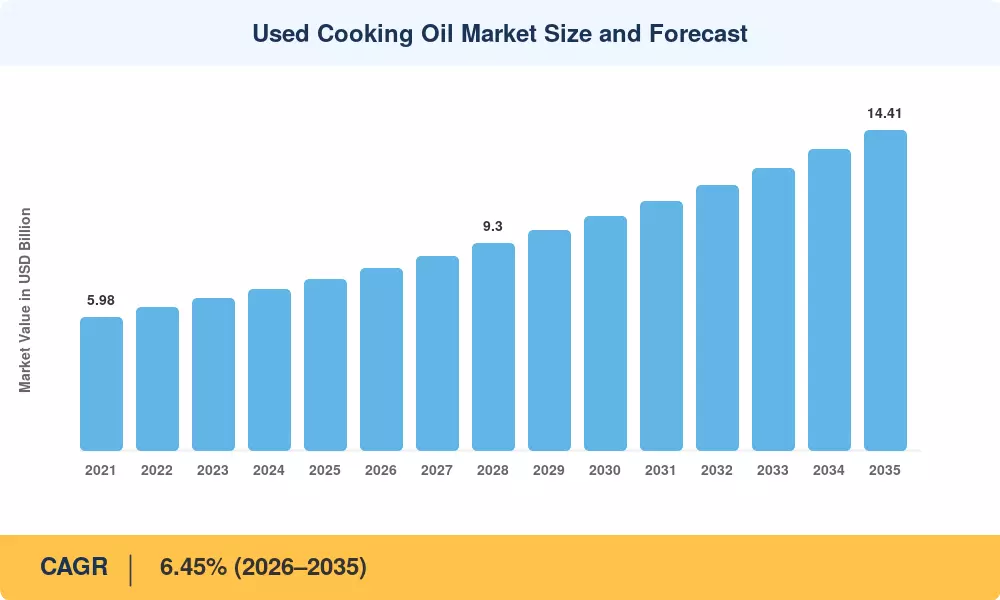
Used Cooking Oil Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
RED III and national blending mandates +1.35 pp Europe Long-term (≥4 yr)
Section 45Z credit and RFS D4 RIN pricing +1.10 pp North America Medium-term (2–4 yr)
SAF mandates: ReFuelEU Aviation, CORSIA +0.95 pp Global Long-term (≥4 yr)
HoReCa and quick-service outlet expansion +0.75 pp Asia-Pacific Medium-term (2–4 yr)
Corporate net-zero and Scope 3 procurement +0.55 pp Global Medium-term (2–4 yr)
Digital route optimisation in collection logistics +0.40 pp Europe, North America Short-term (≤2 yr)
FOG discharge enforcement by municipal utilities +0.30 pp Global Short-term (≤2 yr)


Mandate Depth in Europe

With RED III, Brussels lifted the bar once further, mandating a 14.5% reduction in transportation-related greenhouse gas intensity by 2030 and raising the advanced biofuel sub-targets to 5.5% [1]. Dutch HBE ticket prices remained over EUR 13 for the majority of 2025, and Germany's GHG quota increased to 25.1% by 2030 [15]. Because of these processes, each certified liter becomes a tradable compliance asset, which explains why European gate prices often surpass Asian equivalents by USD 90–120 per ton.


US Credit Architecture

Washington substituted a producer-side incentive based on carbon intensity for the blender's credit. Waste oils normally score between 15 and 22 gCO2e/MJ, and fuels scoring less than 50 gCO2e/MJ are eligible for rising value under 45Z [2]. Biomass-based diesel is set at 5.61 billion gallons in the EPA's 2026–2027 Renewable Fuel Standard quantities, a step adjustment that brings almost 1.4 million more tons of waste fats into US refineries [16].


Aviation Pull-Through

Airlines now compete directly with road-fuel producers for the same molecules. ReFuelEU Aviation requires 2% SAF in 2025, rising to 6% in 2030 and 20% by 2035, with a synthetic sub-quota that leaves waste lipids carrying most near-term volume [7]. Estimates SAF output reached 2.0 million tonnes in 2025, still under 1% of jet fuel demand, implying sustained scarcity premiums for certified waste oil processing capacity [17].

Foodservice Density in Asia

China's catering revenue exceeded CNY 5.6 trillion in 2024, and India added more than 18,000 organised quick-service outlets between 2022 and 2025 [10][8]. Density matters more than volume: a collector servicing 400 outlets within a 15-kilometre radius achieves roughly 38% lower cost per litre than one covering a dispersed rural territory.


Restraints Impact Analysis

Restraint weights follow the same directional convention as Section 4 and represent modelled drag rather than deductible components. Several restraints interact — fraud enforcement, for example, simultaneously suppresses reported volume and raises verified-material prices. Buyers evaluating the Used Cooking Oil Market should treat these as risk-adjusted planning inputs.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Feedstock adulteration and certification fraud −0.85 pp Europe, Asia-Pacific Medium-term (2–4 yr)
Fragmented household collection economics −0.60 pp Global Long-term (≥4 yr)
Price volatility versus tallow and POME substitutes −0.50 pp Global Short-term (≤2 yr)
Export restrictions and anti-dumping actions −0.45 pp Asia-Pacific Short-term (≤2 yr)
Annex IX Part B multiplier caps −0.35 pp Europe Medium-term (2–4 yr)


The Traceability Problem

Several ISCC certificates were suspended in 2024 as a result of investigations into imports coming into Europe from Southeast Asia, since volumes claimed from some origins were far higher than plausible local generation [5][6]. There were immediate repercussions: Physical mass-balance audits were mandated by European customers, and compliance costs increased by an estimated USD 8–14 per ton. Satellite-verified site inspections are increasingly required by certification agencies for high-risk origins.


Household Channel Economics

Although it is costly to collect, residential oil is abundant. Municipal drop-off programs seldom recover costs without subsidies because the average European household discards 3–5 liters annually compared to 900–1,400 liters from a mid-sized restaurant [11]. The ceiling is demonstrated by Brazil's voluntary supermarket collection network, where recovery rates are still close to 4% of household generation despite nationwide coverage [20].


Used Cooking Oil Market Opportunities

Sovereign SAF Hubs in the Gulf

Abu Dhabi and Riyadh are pairing refinery co-processing with regional aggregation, targeting jet fuel exports rather than domestic road blending. Because Gulf states generate modest domestic volumes, success depends on importing certified material from South Asia and East Africa — creating a trading corridor that barely existed in 2021 and now shapes freight economics across the Used Cooking Oil Market.

Co-Processing Retrofits

Conventional refiners can inject 5–10% lipid feedstock into existing hydrotreaters at roughly one-fifth the capital cost of a greenfield HVO unit [12]. Retrofit projects in Spain, Italy and California demonstrate 18-month payback at prevailing credit values, opening participation to operators previously priced out.

Emerging-Market Formalisation

Indonesia, Vietnam and Nigeria host large informal aggregation networks with no certification pathway. Development-finance-backed programmes that issue digital collector IDs and weighbridge receipts can convert grey volume into premium certified supply, lifting realised prices by 25–40% for participating collectors [20].

Data Monetisation and Yield Analytics

Sensor-equipped containers generate fill-rate, temperature and quality telemetry that collectors increasingly sell back to foodservice chains as fryer-management insight. Subscription analytics layered onto collection contracts carry 55–70% gross margins, materially higher than the underlying commodity trade, and represent the clearest new business model inside the Used Cooking Oil Market [11].

Oleo-Chemical Premiumisation

Surfactant and lubricant formulators facing bio-content disclosure requirements are qualifying waste-derived fatty acids for personal-care and industrial applications, where realised values exceed fuel-grade netbacks by USD 140–260 per tonne [9].


Used Cooking Oil Market Future Outlook

Autonomous Collection Networks

Route density determines profitability, and operators are automating the decision layer. Fill-level sensors combined with predictive models cut empty pickups by 30–45% in early European deployments, and the same telemetry underpins the certification audit trail regulators increasingly demand [11]. By 2030, expect algorithmic dispatch to be table stakes across the Used Cooking Oil Market rather than a differentiator.

Refinery Asset Reallocation

IEA projects global biofuel demand growing roughly 38% between 2024 and 2030, with waste-based pathways capturing a disproportionate share of new capacity [4]. Refiners facing declining road-diesel demand in OECD markets will keep converting hydrotreaters rather than idling them, sustaining structural feedstock scarcity.

Carbon Intensity as Currency

Pricing is shifting from tonnage to gCO2e/MJ. As California LCFS, Canadian CFR and 45Z all settle value on measured carbon intensity, suppliers able to document low-emission logistics will command premiums of USD 30–60 per tonne over commodity-grade material [2][14].

Verification Infrastructure Consolidation

Fragmented national registries will converge toward interoperable digital passports. IRENA has argued that harmonised sustainability accounting is the binding constraint on cross-border bioenergy trade, and resolution of that constraint would materially widen the addressable Used Cooking Oil Market for exporters in Africa and South Asia [18].


Regional Market Share Analysis

Region Metric Primary Investment Themes
North America USD 1.62 Billion (2025) 45Z-driven HVO capacity, RIN trading desks
Europe 41.0% share Certification infrastructure, SAF co-location
Asia-Pacific 8.1% CAGR Domestic processing, export substitution
South America 6.9% CAGR Soy-diesel blending, municipal recovery schemes
Middle East & Africa 4.0% share Aviation hubs, import aggregation
Total USD 7.71 Billion (2025) —

Geographic distribution within the Used Cooking Oil Market reflects mandate strength first and generation volume second — Asia-Pacific produces more waste oil than Europe yet monetises less of it domestically.


North America

Country Metric Key Driver
US 84.0% of region 45Z credit and RFS D4 obligation volumes
Canada USD 0.19 Billion (2025) Clean Fuel Regulations compliance credits
Mexico 5.8% CAGR Cross-border feedstock export to US refiners


Rendering incumbents dominate here. Darling Ingredients operates more than 200 collection and processing sites, and its Diamond Green Diesel joint venture consumes a substantial share of domestic waste lipids internally [12]. EPA's set rule volumes for 2026–2027 effectively guarantee offtake, which has compressed collector churn and pushed restaurant contracts from spot arrangements toward three-year fixed-margin structures [16].

Europe

Country Metric Key Driver
Germany 21.5% of region GHG quota escalation to 25.1% by 2030
UK USD 0.44 Billion (2025) RTFO development fuel certificates
France 6.2% CAGR TIRUERT incentive restructuring
Italy 11.0% of region Eni biorefinery conversions
Spain 5.9% CAGR Repsol Cartagena HVO offtake
Nordic Countries USD 0.31 Billion (2025) Sweden reduction obligation
Russia 2.4% of region Limited mandate framework
Rest of Europe 9.5% of region Central European collection build-out


Depth of enforcement separates Europe from every other region in the Used Cooking Oil Market. The Union Database for Biofuels went live to trace consignments end-to-end, and national regulators can now cross-check declared origins against registry entries [6]. Italy and Spain converted legacy crude refineries into biorefineries, embedding demand geographically close to Mediterranean collection networks.

Asia-Pacific

Country Metric Key Driver
China 38.5% of region Export volumes plus emerging SAF plants
India 9.4% CAGR RUCO programme and OMC procurement
Japan USD 0.21 Billion (2025) 2030 SAF replacement target
South Korea 7.6% CAGR Renewable fuel standard expansion
ASEAN 19.0% of region Malaysia and Indonesia aggregation hubs
Rest of Asia-Pacific 6.5% of region Nascent collection formalisation


Policy is turning outbound flows inward across the Used Cooking Oil Market. China's SAF pilot programme designated multiple airports for blended jet fuel uplift, while domestic producers commissioned units aimed at capturing conversion margin previously exported [10]. India's RUCO initiative, administered by FSSAI, links food-safety inspection of frying oil to mandatory handover, an unusually effective enforcement design [8].

South America

Country Metric Key Driver
Brazil 71.0% of region B15 blending mandate progression
Argentina USD 0.09 Billion (2025) Export-oriented biodiesel capacity
Rest of South America 8.0% of region Municipal recovery pilots


Brazil's National Energy Policy Council advanced the biodiesel blend toward B15, and while soybean oil supplies most feedstock, waste lipids earn premium CBIO credits under RenovaBio [20]. Collection remains concentrated in São Paulo and Rio Grande do Sul, where cooperative networks have organised informal collectors into audited supply chains.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 26.0% of region Aramco SAF joint ventures
UAE 9.8% CAGR Tadweer waste-to-fuel mandates
South Africa USD 0.05 Billion (2025) Municipal FOG enforcement
Egypt 12.5% of region Tagaddod collection network
Rest of MEA 21.0% of region Import aggregation for Gulf refiners


Aviation ambition outpaces domestic generation. UAE authorities set a 1% SAF requirement for departing flights from 2031, and Emirates has run demonstration flights on fully blended fuel [17]. Egypt has become an unexpected exporter, with organised networks shipping certified volumes into European biorefineries.


Used Cooking Oil Market By Region, 2025-2035

Used Cooking Oil Market Segmentation

By Source

Source composition determines both cost-to-collect and certification risk across the Used Cooking Oil Market.

Segment Metric Primary Demand Driver
HoReCa 52.5% share High per-site yield and contractable volumes
Household Kitchens 7.9% CAGR Municipal recovery schemes and deposit incentives
Food Processing Plants USD 1.58 Billion (2025) Consistent quality and single-point logistics


HoReCa remains the commercial backbone. Restaurants, hotels and catering operations deliver predictable weekly volumes at known quality specifications, allowing collectors to underwrite fixed-price contracts and finance container fleets against them. Food Processing Plants offer the cleanest material — low free fatty acid content, minimal moisture — and increasingly negotiate direct supply agreements with biorefiners, bypassing intermediaries and capturing 12–18% more of the value chain than they did in 2021 [9].

By End Use

The end-use mix has narrowed sharply since 2021, and the Used Cooking Oil Market now functions primarily as a fuel supply chain.

Segment Metric Primary Demand Driver
Biodiesel and HVO 68.0% share Blending mandates and producer tax credits
Oleo-Chemicals USD 1.19 Billion (2025) Bio-content requirements in surfactants
Animal Feed 3.4% CAGR Regional permissibility and protein economics
Others 5.5% share Industrial lubricants, candles, specialty uses


Biodiesel and HVO dominate because policy pays for them. Every major mandate regime assigns waste-derived fuel double-counting treatment or superior carbon scoring, so processors consistently outbid alternative outlets. Oleo-Chemicals occupy the premium tier: fatty acid distillation for surfactants, plasticisers and metalworking fluids yields netbacks well above fuel parity, though qualification cycles run 12–24 months and volumes stay comparatively small [9].


Competitive Benchmarking

Concentration is low. Estimated HHI sits near 620, with the top five participants controlling roughly 31–36% of global value — a structure typical of logistics-intensive businesses where local route density beats global scale. Consolidation is accelerating nonetheless, as refiners buy collectors to secure supply. Vertical integration is now the defining strategic pattern in the Used Cooking Oil Market.

Company Est. Revenue Share Range Key Offerings for Used Cooking Oil Market Strategic Positioning
Darling Ingredients ~10–13% Collection, rendering, DAR PRO services Vertically integrated via Diamond Green Diesel
Neste Oyj ~8–11% Feedstock sourcing, HVO and SAF production Global renewables leader with own aggregation arm
Greenergy Fuels ~4–6% Waste-based biodiesel, supply and distribution Strong UK and Northern Europe fuel logistics
Olleco ~3–5% Foodservice collection, biodiesel supply Closed-loop model with grocery and QSR chains
Argent Energy Group ~3–5% Multi-feedstock biodiesel processing Specialist in difficult, low-grade waste streams
Baker Commodities ~2–4% Grease collection, rendering Established US West and Central route network
Münzer Bioindustrie ~2–4% Collection, biodiesel manufacture Central European density with own fleet
SARIA / ecoMotion ~2–4% Rendering, biodiesel, oleochemical inputs Diversified by-product portfolio
ADM ~2–3% Feedstock trading, processing Agricultural trading reach and blending capability
Brocklesby Ltd ~1–3% Waste oil recovery and refining Technical processing of contaminated streams
Buffalo Biodiesel ~1–2% Restaurant collection, resale Aggressive regional route acquisition


Recent News & Developments

Selected events shaping the Used Cooking Oil Market:

  • European Commission (April 2024): Launched an investigation into biodiesel imports from China amid concerns over mislabelled waste feedstock, prompting provisional duties and a repricing of certified European material [5]
  • Neste (June 2024): Completed Rotterdam expansion engineering, targeting SAF capacity of 500,000 tonnes annually and deepening direct collector partnerships across Northwest Europe [3]
  • US Treasury and IRS (January 2025): Published 45Z guidance with the 45ZCF-GREET emissions model, clarifying carbon-intensity scoring for waste lipids and unlocking delayed producer investment [2]
  • Darling Ingredients (March 2025): Expanded European collection footprint through bolt-on acquisitions, reinforcing feedstock security for Diamond Green Diesel's sustainable aviation unit [12]
  • FSSAI, India (August 2024): Broadened RUCO enforcement to smaller food business operators, adding an estimated 60,000 registered outlets to the mandatory handover framework [8]
  • EPA (June 2025): Proposed Renewable Fuel Standard volumes for 2026 and 2027, setting biomass-based diesel at levels well above prior-year obligations [16]
  • Emirates and partners (January 2024): Operated a demonstration flight with one engine on 100% sustainable aviation fuel, validating waste-lipid pathways at commercial scale [17]
  • ISCC (November 2024): Introduced enhanced audit requirements for high-risk origins, including unannounced site visits and mass-balance reconciliation [6]
  • UCO is a key waste-based biofuel feedstock, accounting for 16.5% of Europe’s feedstock consumption, according to 2025-2026 data reported by the European Biodiesel Board (EBB). A significant share of imported UCO arrives in the ARA region via bulk deliveries from Asia, the Middle East and South America.


Used Cooking Oil Market Report Scope

Report Attribute/Metric Details
Market Scope Global collection, aggregation, processing and end-use of used cooking oil across HoReCa, household and industrial sources
Study Period 2021-2035
Base Year 2025
Historical Data 2021–2024
Forecast Period 2026–2035
Market Size in 2025 USD 7.71 Billion
Market Size in 2035 USD 14.41 Billion
CAGR (2026–2035) 6.45%
Fastest Growing Segments Household Kitchens (Source); Biodiesel and HVO (End Use); Asia-Pacific (Geography)
Regions Covered Asia-Pacific (Geography); North America, Europe, APAC, South America, MEA
Companies Profiled 11 (Darling Ingredients, Neste Oyj, Greenergy Fuels, Olleco, Argent Energy Group, Baker Commodities, Münzer Bioindustrie, SARIA / ecoMotion, ADM, Brocklesby Ltd, Buffalo Biodiesel)
Valuation Currency USD Billion
Methodology Triangulated approach: company filings, procedural volume databases, 220+ primary interviews

FAQs

What contractual structures should buyers use when securing supply in the Used Cooking Oil Market?
Three-year fixed-margin contracts indexed to a published edible oil benchmark reduce exposure better than spot purchasing. Include audit-access clauses and origin declarations. Buyers without certification rights in the contract routinely lose compliance value at the point of sale [6].
How do insurers and lenders assess collection businesses?
Route density and contract tenure drive valuation more than tonnage. Lenders typically discount portfolios where more than 30% of volume sits on spot terms. Environmental liability from historic tank storage is the most common diligence blocker [12].
Does material quality change what a supplier can charge?
Yes. Free fatty acid content, moisture, and impurity levels determine which processors can accept a load without pre-treatment. Clean sub-5% FFA material within the Used Cooking Oil Market commands premiums that fully offset better filtration and storage handling [9].
What integration challenges arise when refiners acquire collectors in the Used Cooking Oil Market?
Cultural and systems mismatch dominates. Refinery planning cycles run quarterly while collection operates daily, and legacy route software rarely connects to refinery ERP. Successful acquirers keep collection operations independent for at least 18 months [12].
How should procurement teams evaluate certification claims?
Request the certificate number and verify it directly against the scheme registry rather than accepting supplier PDFs. Check that declared origin volumes are plausible for the stated collection footprint. Registry cross-checks now catch most misdeclarations [6].
Which emerging use cases could shift demand in the Used Cooking Oil Market after 2030?
Marine fuel is the significant one. Bio-methanol and B30 blends for shipping face tightening IMO carbon intensity rules, creating a second large-volume outlet that competes directly with aviation for certified waste lipids [18].
Is regional arbitrage still profitable for traders?
Margins have compressed substantially since 2023 as anti-dumping duties and traceability audits raised the cost of moving material across borders. Arbitrage now works mainly on certified, fully documented cargoes into mandate-heavy destinations [5][19].    
Author
Author Author Profile Snehal Singh LinkedIn Manager - Research
High acumen in analyzing complex macro & micro markets with more than 6 years of work experience in the field of market research. By implementing her analytical skills in forecasting and estimation into market research reports, she has expertise in Packaging, Construction, and Equipment domains. She handles a team size of 20-25 resources and ensures smooth running of the projects, associated marketing activities, and client servicing.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed energy journals, waste management publications, and authoritative environmental organizations. Key sources included the US Environmental Protection Agency (EPA) – Renewable Fuel Standard (RFS) program and National Renewable Energy Laboratory (NREL), European Commission – Renewable Energy Directive (RED III) and Eurostat Energy Database, US Energy Information Administration (EIA), International Energy Agency (IEA) Bioenergy Program, US Department of Agriculture (USDA) – Economic Research Service and National Agricultural Statistics Service, Roundtable on Sustainable Biomaterials (RSB), ASTM International (biodiesel standards), International Sustainability and Carbon Certification (ISCC), Food and Agriculture Organization (FAO) of the United Nations, National Biodiesel Board (NBB), Waste Management World, Biomass and Bioenergy Journal, Renewable and Sustainable Energy Reviews, and national environmental ministry reports from key biodiesel-producing markets. These sources were used to collect biodiesel production statistics, renewable energy policy frameworks, waste oil collection volumes, feedstock pricing trends, and regulatory compliance data for used cooking oil, animal feed applications, and industrial lubricant sectors.


Primary Research

To gather both qualitative and quantitative information, the primary research process involved interviewing players from both the supply and demand sides. From the supply side, we heard from waste management firms, rendering plants, used cooking oil collectors, biodiesel refiners, and VPs of sustainability as well as heads of regulatory affairs and procurement. Directors of fleet operations, sustainability officers from QSRs, procurement leads from biofuel distributors, nutritionists for animal feed, and supply chain managers from food processing conglomerates made up the demand-side sources. The market segmentation was confirmed through primary research, which also established the expansion deadlines for the renewable diesel facility and provided insights into the economics of collection logistics, the volatility of UCO pricing, and the requirements for ISCC certification.

Primary Respondent Breakdown:

By Designation: C-level Primaries (30%), Director Level (32%), Others (38%)

By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through feedstock volume mapping and revenue analysis across the value chain. The methodology included:

Identification of 50+ key operators across North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa

Feedstock mapping across restaurant grease trap waste, food processing effluents, household collection programs, and industrial food manufacturing by-products

Analysis of reported and modeled annual revenues specific to UCO collection, refining, and end-use applications (biodiesel, SAF, animal feed)

Coverage of collectors and refiners representing 75-80% of global market share in 2024

Extrapolation using bottom-up (UCO collection volume × average selling price by country/region) and top-down (biodiesel production capacity × UCO feedstock blend ratio) approaches to derive segment-specific valuations for transesterification versus hydrotreatment pathways

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.

















