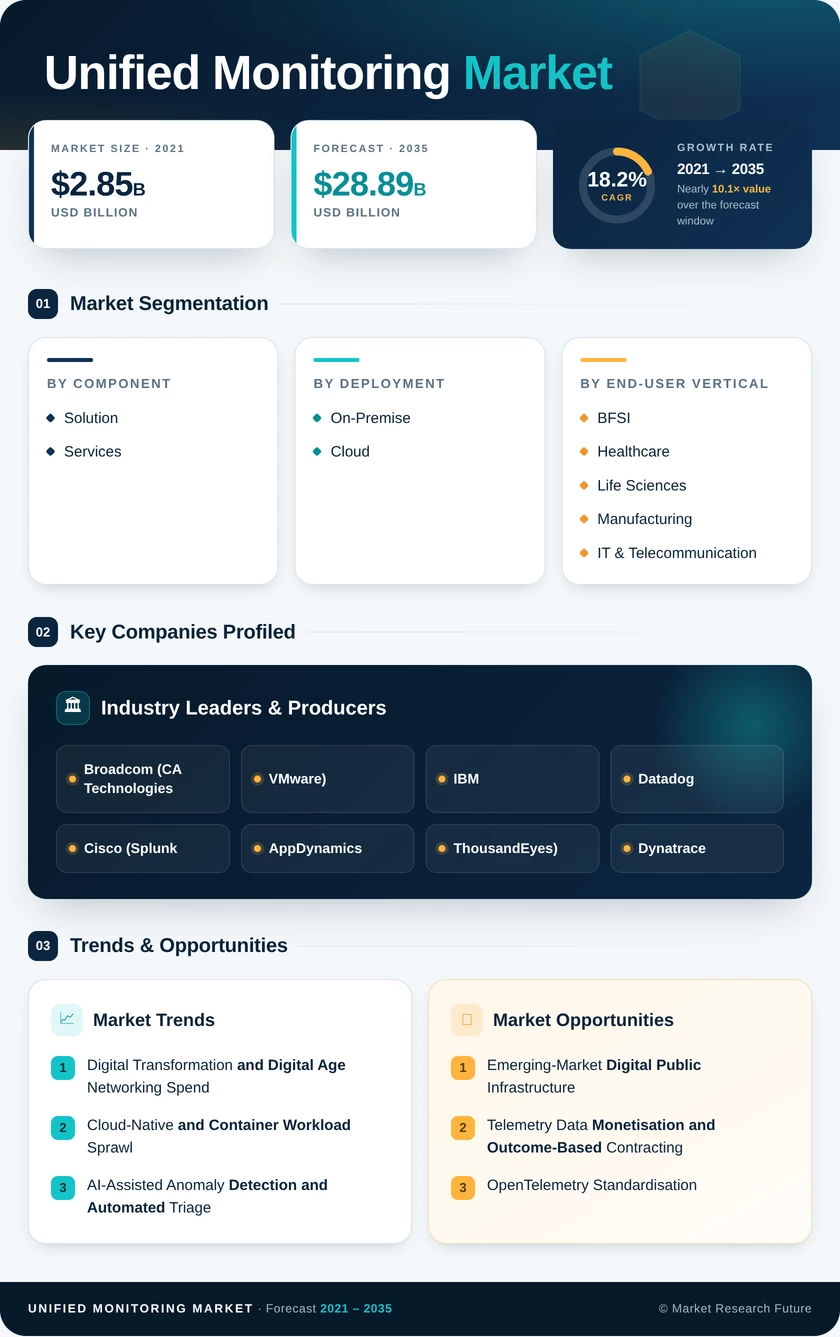
Market Segmentation Analysis
By Component
9.1.1 Solution
9.1.2 Services
By Deployment
9.2.1 On-Premise
9.2.2 Cloud
By End-user Vertical
9.3.1 BFSI
9.3.2 Healthcare and Life Sciences
9.3.3 Manufacturing
9.3.4 IT & Telecommunication
9.3.5 Retail
9.3.6 Other End-user Vertical
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Component | Solution; Services | Solution (68.4% share, 2025) | Services (19.6% CAGR, 2026–2035) |
| By Deployment | On-Premise; Cloud | Cloud (USD 3.34 Billion, 2025) | Cloud (USD 3.34 Billion, 2025) |
| By End-user Vertical | BFSI; Healthcare and Life Sciences; Manufacturing; IT & Telecommunication; Retail; Other End-user Vertical | BFSI (24.8% share, 2025) | Healthcare and Life Sciences (20.8% CAGR, 2026–2035) |
Market Segmentation Overview
By Component
| Sub-Segment | Key Trend |
| Solution | Correlation engines and unified dashboards displacing tier-specific point tools; AI-driven root-cause analysis moving into base subscription tiers |
| Services | Consolidation programmes driving demand for integration, custom collector development, and 24/7 managed operations |
Solution holds 68.4% of 2025 revenue because the licensed correlation and dashboarding layer is where displacement value is realised, and buyers replacing eight or ten incumbent tools are purchasing that engine rather than the reporting around it. Services grow faster at a 19.6% CAGR, reflecting a practical constraint: instrumenting mainframe subsystems, proprietary controllers, and undocumented middleware requires specialist engineering that most internal teams cannot resource. Enterprise deals in this market rarely close without an attached implementation scope, and managed operations extend that attachment beyond go-live.
By Deployment
| Sub-Segment | Key Trend |
| On-Premise | Sustained by data residency rules, air-gapped defence and payment estates, and existing capital investment in local collection infrastructure |
| Cloud | Default choice for elastic ingestion, faster rollout, and consumption-aligned commercial terms |
Cloud accounts for USD 3.34 Billion of 2025 revenue and is the practical default wherever telemetry volumes fluctuate with request traffic rather than host count. On-Premise retains a 38.3% share for reasons regulation will not remove this decade — logs carrying personal data under European rules, restricted-egress payment and defence estates, and national cloud frameworks in Saudi Arabia and India that constrain where control planes may run. The prevailing enterprise pattern is hybrid: a self-hosted collection tier feeding a cloud-hosted analytics and correlation layer.
By End-user Vertical
| Sub-Segment | Key Trend |
| BFSI | Operational resilience supervision and instant-payment availability obligations turning telemetry into audit evidence |
| Healthcare and Life Sciences | Electronic health record uptime and connected clinical device estates replacing fragmented manual oversight |
| Manufacturing | IT–OT convergence extending coverage to plant-floor networks and industrial controllers |
| IT & Telecommunication | Standalone 5G core deployment and service assurance across distributed network functions |
| Retail | Peak-season commerce availability and omnichannel order-flow integration |
| Other End-user Vertical | Public sector, education, logistics, and energy estates modernising legacy infrastructure |
BFSI leads with 24.8% share, and the driver is compulsion rather than preference — resilience regulation attaches reporting deadlines to incidents, which requires evidence-grade telemetry across payment gateways, core banking, and third-party connectivity. IT & Telecommunication follows at USD 1.21 Billion as operators instrument standalone 5G cores and distributed network functions. Healthcare and Life Sciences grows fastest at a 20.8% CAGR from a smaller base, because imaging pipelines, EHR platforms, and thousands of networked clinical devices create a monitoring surface that hospital IT departments previously covered with disconnected, largely manual tooling.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA