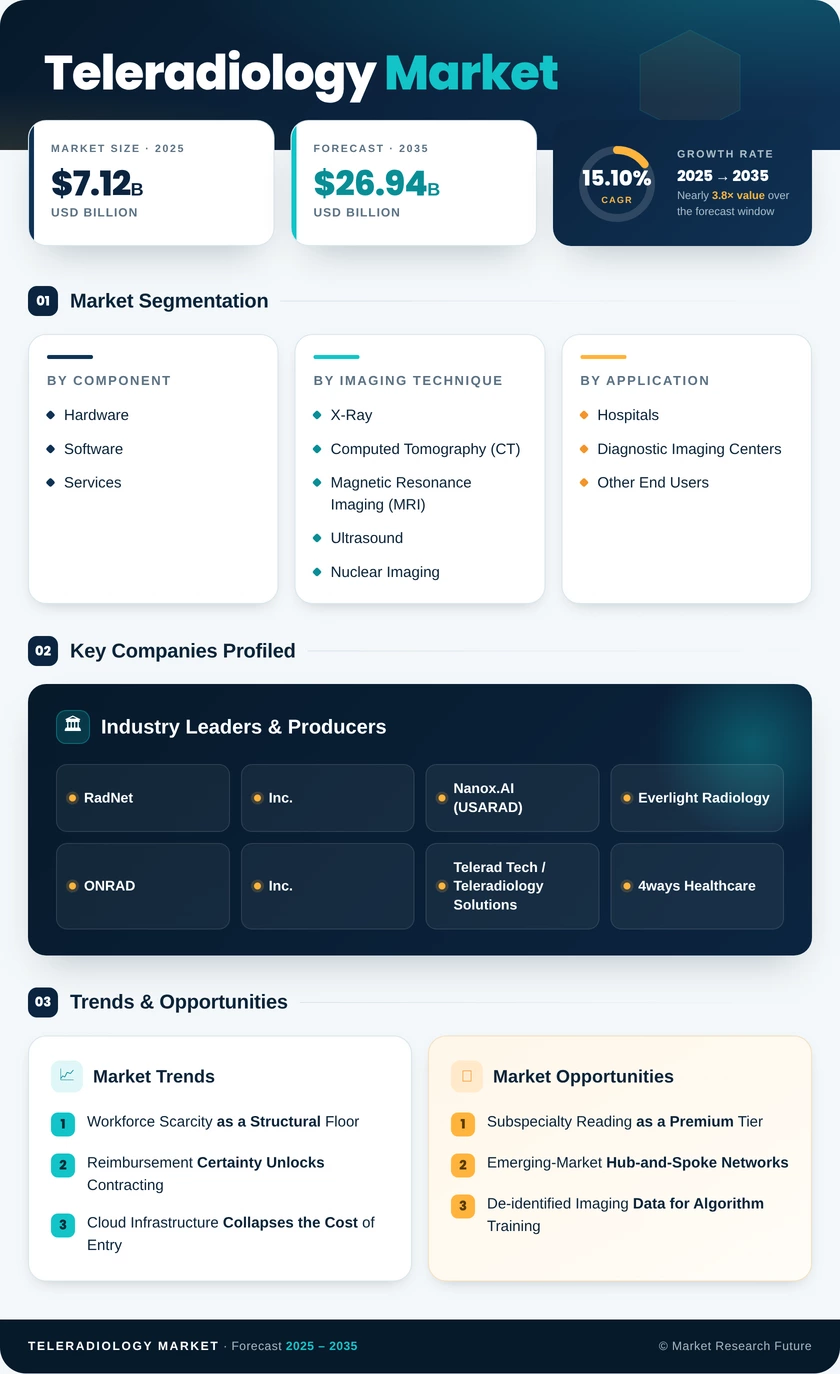
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Component | Hardware, Software, Services | Software | Hardware |
| By Imaging Technique | X-Ray, Computed Tomography (CT), Magnetic Resonance Imaging (MRI), Ultrasound, Nuclear Imaging, Others | Computed Tomography (CT) | Magnetic Resonance Imaging (MRI) |
| By End User | Hospitals, Diagnostic Imaging Centers, Other End Users | Hospitals | Diagnostic Imaging Centers |
| By Geography | North America, Europe, Asia-Pacific, South America, Middle East & Africa | North America | Asia-Pacific |
Market Segmentation Overview
By Component
| Sub-Segment | Key Trend |
| Hardware | Diagnostic display refresh to meet DICOM calibration standards for primary interpretation |
| Software | Consolidation of viewer, worklist, and archive functions into single subscription platforms |
| Services | Shift from generalist night coverage toward contracted subspecialty read capacity |
Component economics are diverging. Software retains pricing power because it sits at every workflow touchpoint, while services compete increasingly on turnaround guarantees rather than per-study rates. Hardware remains a replacement-cycle business tied to display certification requirements.
By Imaging Technique
| Sub-Segment | Key Trend |
| X-Ray | High-volume emergency throughput with growing algorithmic pre-read |
| Computed Tomography (CT) | Stroke and trauma protocols driving time-critical remote interpretation |
| Magnetic Resonance Imaging (MRI) | Subspecialty neuro and musculoskeletal reads commanding premium pricing |
| Ultrasound | Handheld point-of-care devices creating new expert-read demand tiers |
| Nuclear Imaging | Oncology staging and cardiac perfusion expanding specialized read volume |
| Others | Mammography and hybrid modalities entering remote reading workflows |
Modality mix determines margin. CT and MRI carry the acuity and complexity that justify premium contracting, while X-ray and ultrasound drive raw volume and are the first modalities where algorithmic pre-reading materially changes reader workload.
By End User
| Sub-Segment | Key Trend |
| Hospitals | Continuous emergency coverage obligations sustaining long-term contracts |
| Diagnostic Imaging Centers | Scanner capacity growth outpacing radiologist recruitment |
| Other End Users | Urgent care, mobile screening, and correctional health adopting on-demand reads |
Hospitals will remain the revenue base through 2035, but growth concentrates in imaging centers and non-traditional settings where remote interpretation is the enabling condition for adding capacity at all.
By Geography
| Sub-Segment | Key Trend |
| North America | Consolidation into national platforms with subspecialty panel depth |
| Europe | Public-sector outsourcing under workforce pressure, constrained by data residency |
| Asia-Pacific | Hub-and-spoke networks connecting district facilities to urban reading centers |
| South America | Private hospital chains centralizing interpretation across distributed sites |
| Middle East & Africa | Sovereign digital health programs funding national reading infrastructure |
Geographic growth follows the gap between imaging capacity and interpretation capacity. That gap is widest in Asia-Pacific and Africa, and most commercially monetizable where reimbursement or sovereign funding already exists.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA