Segmentation Quick Reference
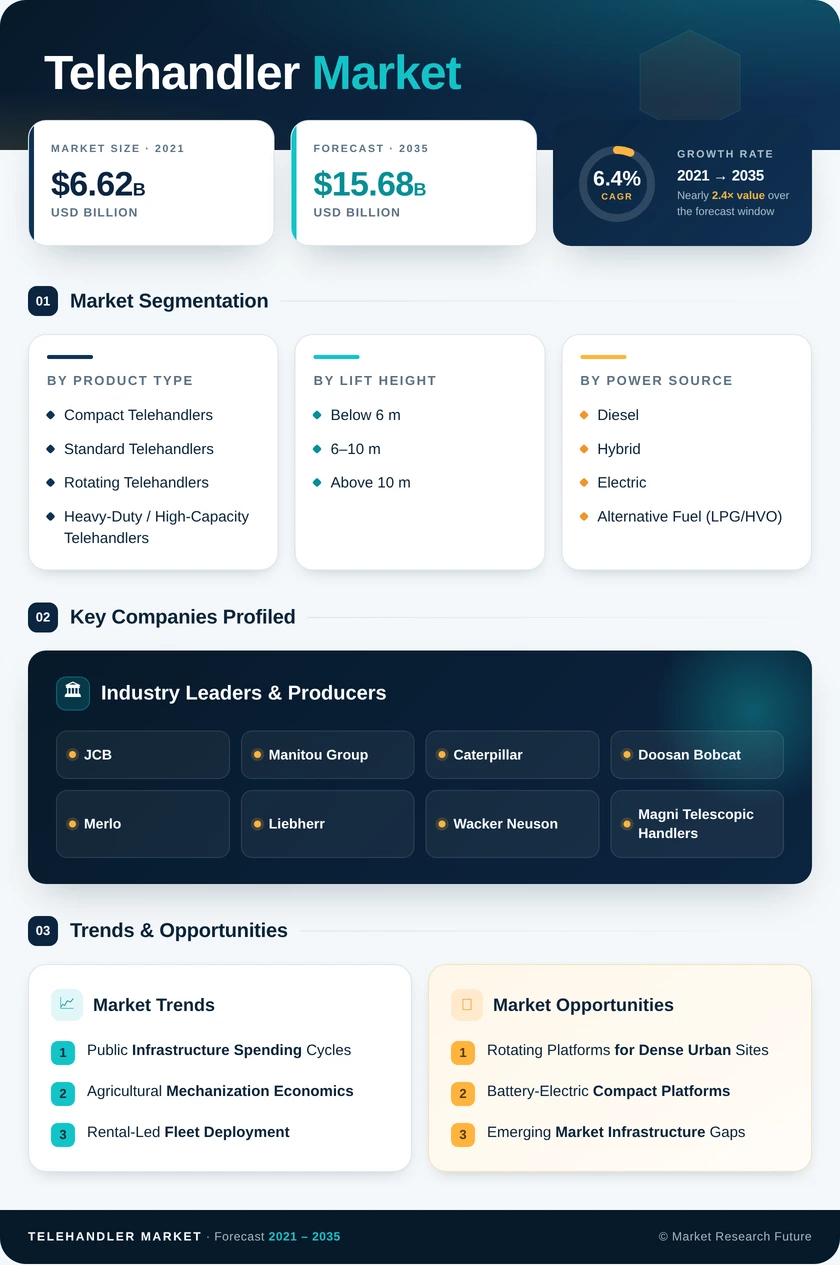
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Product Type | Compact Telehandlers; Standard Telehandlers; Rotating Telehandlers; Heavy-Duty / High-Capacity Telehandlers | Compact Telehandlers | Rotating Telehandlers |
| By Lift Height | Below 6 m; 6–10 m; Above 10 m | 6–10 m | Above 10 m |
| By Power Source | Diesel; Hybrid; Electric; Alternative Fuel (LPG/HVO) | Diesel | Electric |
| By Application | Construction; Agriculture; Logistics & Industrial Material Handling; Mining & Quarrying; Others (Utilities, Municipal) | Construction | Logistics & Industrial Material Handling |
| By Geography | North America; Europe; Asia-Pacific; South America; Middle East & Africa | North America | Asia-Pacific |
Market Segmentation Overview
By Product Type
| Sub-Segment | Key Trend |
| Compact Telehandlers | Electrification concentrates here first, driven by indoor and low-emission-zone duty cycles |
| Standard Telehandlers | Rental fleet standardization on common driveline and cab architecture across capacity classes |
| Rotating Telehandlers | Substitution for mobile cranes on constrained urban sites, led by Italian and French suppliers |
| Heavy-Duty / High-Capacity Telehandlers | Specification driven by mining, port, and industrial maintenance contracts requiring extended reach under load |
Product-type competition has moved beyond capacity ratings. Compact units retain the broadest application base, but rotating configurations are absorbing work previously split between a crane and a conventional handler, which improves site economics and shortens mobilization schedules. Heavy-duty machines remain a small, high-margin pocket where engineering reputation and parts availability determine supplier selection.
By Lift Height
| Sub-Segment | Key Trend |
| Below 6 m | Sustained agricultural and indoor demand where overhead clearance limits machine height |
| 6–10 m | Core volume band aligned to two-to-three-storey construction and standard warehouse racking |
| Above 10 m | Fastest growth as urban vertical density rises and facade renovation activity expands |
Lift height segmentation tracks building typology more closely than it tracks geography. The 6–10 metre band remains the rental default because it covers the widest range of jobs without stability trade-offs. Above-10-metre demand rises alongside multi-storey residential and commercial construction, particularly in Europe and East Asia where site footprints are constrained.
By Power Source
| Sub-Segment | Key Trend |
| Diesel | Retains majority position through remote-site and high-duty-cycle applications with no charging access |
| Hybrid | Serves as a compliance bridge for buyers unwilling to accept battery residual value risk |
| Electric | Fastest-growing power source, concentrated in compact classes and regulated urban jurisdictions |
| Alternative Fuel (LPG/HVO) | Enables lifecycle emission reduction without powertrain replacement or charging infrastructure |
Powertrain choice is now a compliance decision as much as an operating one. Diesel remains dominant because site power availability, not machine technology, is the binding constraint on electrification. Where charging exists and access rules are tightening, electric adoption is accelerating well ahead of the global average, and HVO compatibility offers fleets an interim path to reported emission reductions.
By Application
| Sub-Segment | Key Trend |
| Construction | Public infrastructure programs set the cyclical rhythm for overall category demand |
| Agriculture | Farm labor cost inflation and operation consolidation sustain year-round machine utilization |
| Logistics & Industrial Material Handling | Fastest-growing application as yard operations exceed conventional forklift capability |
| Mining & Quarrying | Maintenance access and site servicing drive demand for high-capacity, high-reach configurations |
| Others (Utilities, Municipal) | Grid maintenance, substation work, and municipal services generate steady replacement volume |
Application mix provides natural diversification. Construction and agriculture follow different cycles — one driven by public capital budgets, the other by commodity prices — which moderates aggregate volatility. Logistics represents genuinely incremental demand rather than substitution, as distribution yards require rough-terrain capability that intralogistics equipment cannot deliver.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA