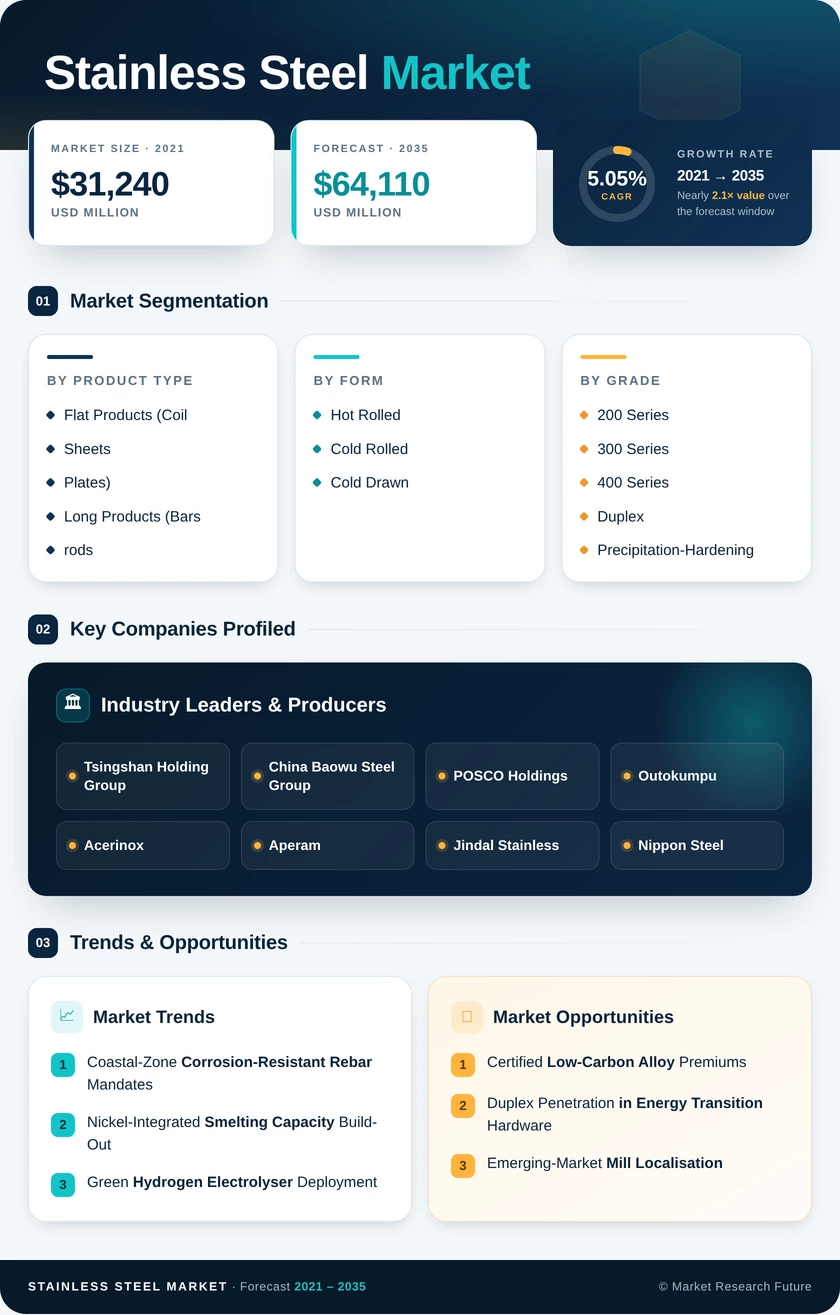
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Product Type | Flat Products (Coil, Sheets, Plates); Long Products (Bars, rods and wire) | Flat Products (Coil, Sheets, Plates) — 62.5% share (2025) | Flat Products (Coil, Sheets, Plates) — 5.50% CAGR (2026–2035) |
| By Form | Hot Rolled; Cold Rolled; Cold Drawn | Cold Rolled — 50.3% share (2025) | Cold Drawn — 5.62% CAGR (2026–2035) |
| By Grade | 200 Series; 300 Series; 400 Series; Duplex; Precipitation-Hardening and Others | 300 Series — 52.2% share (2025) | Duplex — 5.66% CAGR (2026–2035) |
| By Application | Building and Construction; Automotive and Transportation; Metal Products; Electrical Machinery; Mechanical Engineering; Other Applications | Building and Construction — 33.9% share (2025) | Automotive and Transportation — 5.64% CAGR (2026–2035) |
Market Segmentation Overview
By Product Type
| Sub-Segment | Key Trend |
| Flat Products (Coil, Sheets, Plates) | Curtain-wall architecture drives 1.2 mm thin-gauge sheet demand and new annealing capacity |
| Long Products (Bars, rods and wire) | Coastal reinforcement mandates and duplex bar in offshore drilling sustain volume |
Flat Products (Coil, Sheets, Plates) lead at 62.5% of 2025 value and also grow fastest at 5.50%, because facade, appliance, and body-panel buyers all specify coil and sheet, and mills have invested in pickling and bright-anneal lines to serve them. Long Products (Bars, rods and wire) grow more slowly at 4.41% but occupy positions flat product cannot enter: reinforcing bar under India's coastal code, and duplex bar in desalination and offshore fastening. The split is functional rather than competitive, so share drift between them is gradual.
By Form
| Sub-Segment | Key Trend |
| Hot Rolled | Thickness-driven infrastructure demand from bridges and water pipelines |
| Cold Rolled | Finish premiums of USD 150–200 per tonne on bright-annealed material |
| Cold Drawn | Diameter tolerance near ±0.01 mm supports medical and aerospace pricing |
Cold Rolled dominates at 50.3% of 2025 value because sanitary design rules and architectural visibility make ±0.05 mm tolerance and mirror finish mandatory rather than optional, and mills holding inline bright-anneal capacity realise materially higher price. Cold Drawn grows fastest at 5.62% from a narrow base, serving suture wire and aerospace bolt specifications where tolerance rather than tonnage sets price. Hot Rolled retains the largest thickness range and remains the cost-efficient choice for structural infrastructure work.
By Grade
| Sub-Segment | Key Trend |
| 200 Series | Nickel volatility drives appliance substitution into manganese-bearing grades |
| 300 Series | Weldability and general corrosion resistance secure food and facade applications |
| 400 Series | Exhaust and heat-resistant components track vehicle emissions regulation |
| Duplex | Electrolyser, offshore, and brine-handling orders lift qualified plate demand |
| Precipitation-Hardening and Others | Aerospace strength requirements sustain pricing above USD 4,000 per tonne |
The 300 Series holds 52.2% of 2025 demand because its weldability and corrosion performance make it the default for food processing and building exteriors, and requalifying away from it carries validation cost most fabricators avoid. Duplex advances fastest at 5.66% as European electrolyser programmes and Gulf desalination circuits reward higher strength at reduced wall thickness. Nickel price swings continue transferring low-stress appliance volume into the 200 Series, which caps austenitic share growth even as absolute tonnage rises.
By Application
| Sub-Segment | Key Trend |
| Building and Construction | Whole-life costing offsets triple material cost against 75-year service life |
| Automotive and Transportation | Battery enclosures migrate from aluminium extrusion to thin-gauge sheet |
| Metal Products | Industrial fastener and hardware demand tracks manufacturing output |
| Electrical Machinery | Transformer housings and switchgear absorb thin-gauge material |
| Mechanical Engineering | Pump, valve, and heat exchanger replacement on long service intervals |
| Other Applications | Medical, chemical, and pulp uses sustain the widest margins |
Building and Construction anchors demand at 33.9% of 2025 value, driven by coastal reinforcement mandates and facade specification where public procurement now discounts maintenance avoided over sixty years. Automotive and Transportation grows fastest at 5.64% as enclosure and fuel-cell programmes convert platform volume toward thin-gauge sheet for thermal containment. Mechanical Engineering contributes 12.1% with predictable replacement cycles in pumps and heat exchangers, providing a counter-cyclical floor when construction spending softens.
just now

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA