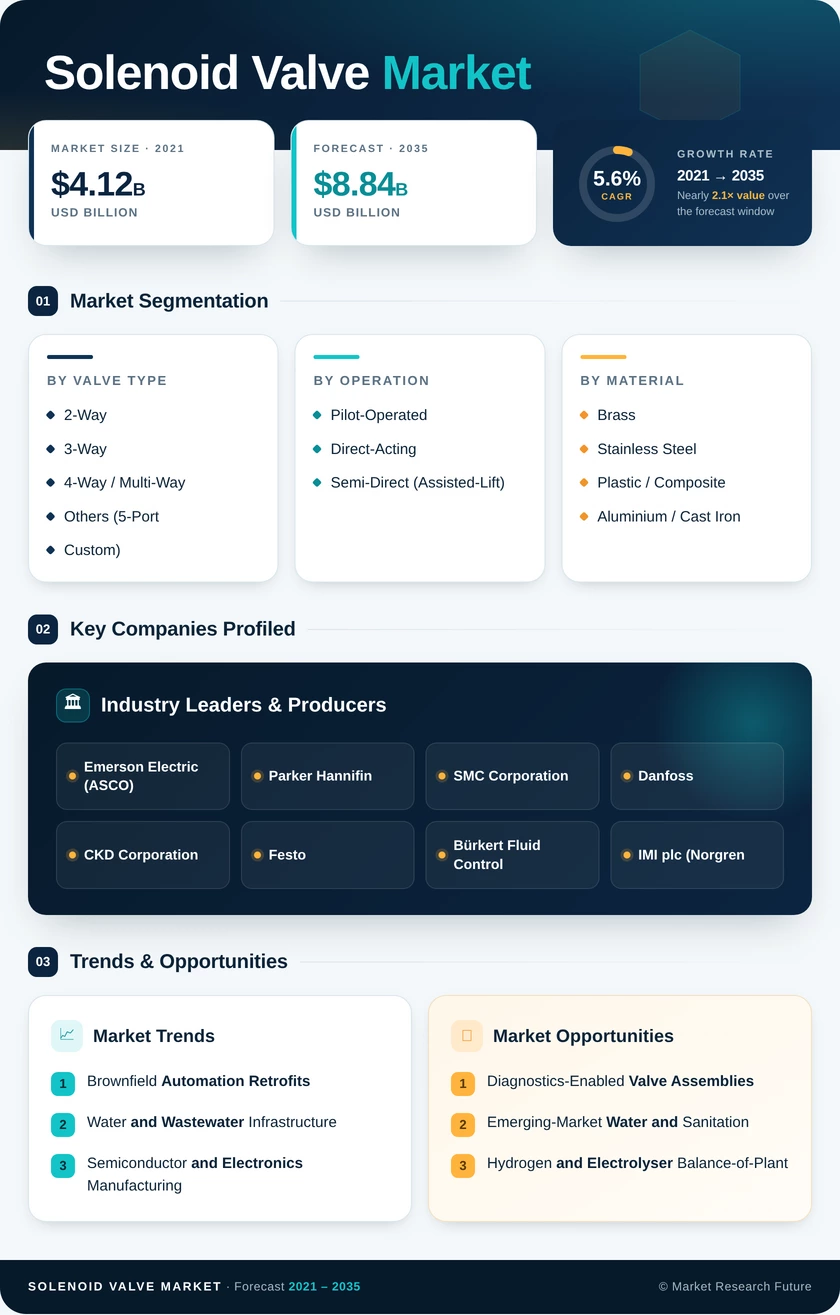
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Valve Type | 2-Way; 3-Way; 4-Way / Multi-Way; Others (5-Port, Custom) | 2-Way | 4-Way / Multi-Way |
| By Operation | Pilot-Operated; Direct-Acting; Semi-Direct (Assisted-Lift) | Pilot-Operated | Semi-Direct (Assisted-Lift) |
| By Material | Brass; Stainless Steel; Plastic / Composite; Aluminium / Cast Iron | Brass | Stainless Steel |
| By End-Use Industry | Oil, Gas & Petrochemicals; Water & Wastewater; Food, Beverage & Pharmaceutical; Chemicals; Semiconductor & Electronics; Automotive & General Industrial; Power & HVAC | Oil, Gas & Petrochemicals | Food, Beverage & Pharmaceutical |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | Asia-Pacific | Middle East & Africa |
Market Segmentation Overview
By Valve Type
| Sub-Segment | Key Trend |
| 2-Way | Volume backbone; sharpest price competition from regional producers |
| 3-Way | Growing as pilot element for larger actuated valve assemblies |
| 4-Way / Multi-Way | Expanding with double-acting cylinder automation in assembly plants |
| Others (5-Port, Custom) | Machine-builder-specific designs with high switching cost |
Port configuration is the first specification decision and the one most closely tied to price. Simple isolation duty gravitates to two-port bodies where competition is fiercest, while multi-port assemblies command better margin because they are designed into machinery and rarely re-sourced mid-lifecycle.
By Operation
| Sub-Segment | Key Trend |
| Pilot-Operated | Preferred above DN15 where line pressure can perform the mechanical work |
| Direct-Acting | Mandatory for zero-differential, vacuum, and analytical service |
| Semi-Direct (Assisted-Lift) | Bridging option for installations with fluctuating supply pressure |
Actuation method is dictated by physics rather than preference. Where differential pressure is reliable, and orifices are large, piloted designs win decisively on coil power. Where pressure may fall to zero, no piloted design will function, which guarantees a durable floor for direct-acting demand.
By Material
| Sub-Segment | Key Trend |
| Brass | Default for potable water, compressed air and light oil duty |
| Stainless Steel | Fastest expansion on hygienic, corrosive and high-purity requirements |
| Plastic / Composite | Selected for aggressive chemicals and demineralised water |
| Aluminium / Cast Iron | Standard for pneumatic manifolds and heavy industrial frames |
Material selection increasingly follows audit requirements rather than engineering minimums. Once a plant falls under hygienic or high-purity oversight, documentation and surface-finish evidence become part of the purchase, and that documentation is what shifts spend upward regardless of whether the process strictly demands it.
By End-Use Industry
| Sub-Segment | Key Trend |
| Oil, Gas & Petrochemicals | Largest revenue pool; hazardous-area certification is table stakes |
| Water & Wastewater | Programme-funded demand with long replacement horizons |
| Food, Beverage & Pharmaceutical | Fastest growth on hygienic-design and validation requirements |
| Chemicals | Corrosion resistance and media compatibility drive specification |
| Semiconductor & Electronics | Ultraclean qualification creates high barriers and high margin |
| Automotive & General Industrial | High-cycle duty rewards long mechanical life |
| Power & HVAC | Steady replacement demand tied to building and plant retrofits |

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA