Solar Panel Recycling Market (2026 - 2035)

ID: MRFR/EnP/5238-CR 128 Pages Anshula Mandaokar Last Updated: September 15, 2026
Solar Panel Recycling Market Research Report By Process (Thermal, Mechanical, Laser), By Panel Type (Crystalline Silicon, Thin Film), By Shelf Life (Normal Loss, Early Loss), By Material Recovered (Glass, Silicon Wafers, Silver, Aluminum, Other Metals) - Forecast to 2035
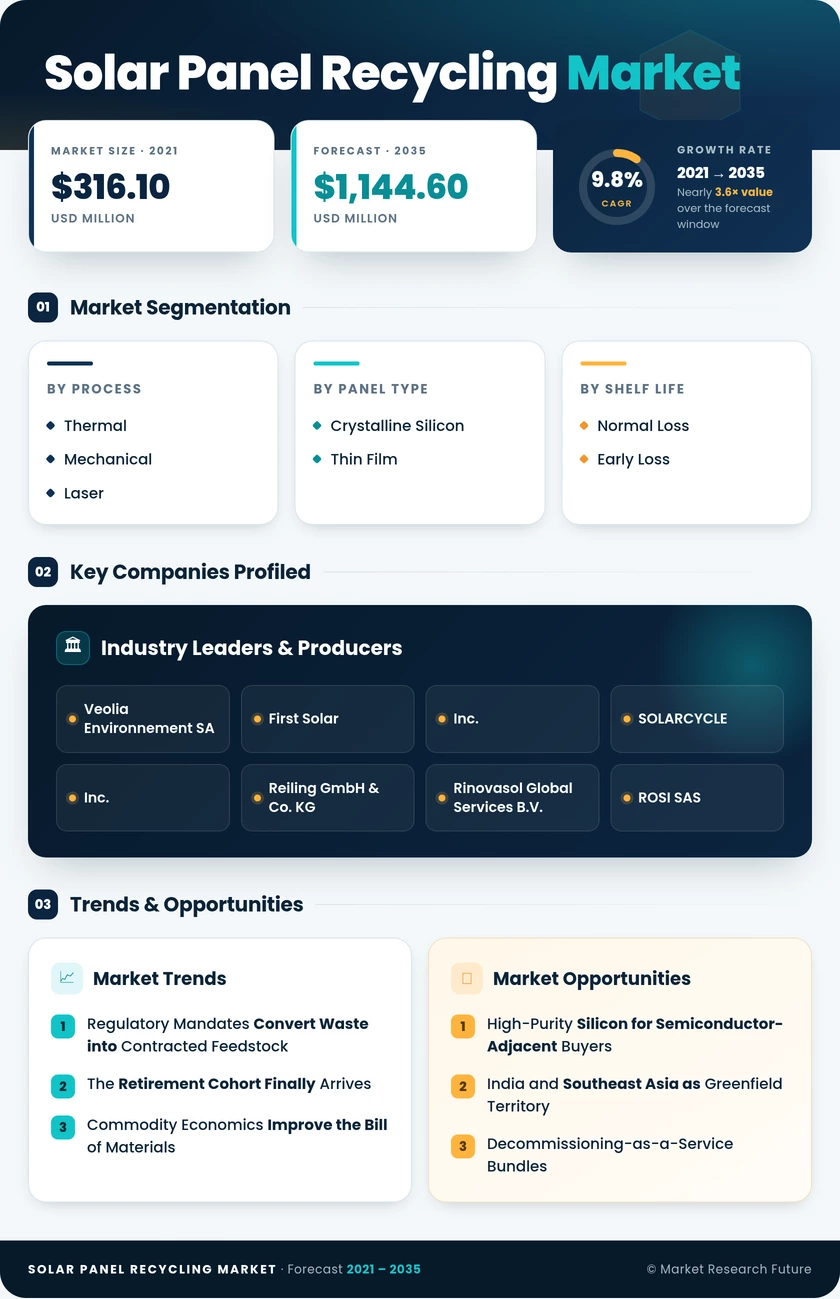
Solar Panel Recycling Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)9.8%
2025 Market SizeUSD 451.5 Million
2035 Market SizeUSD 1,144.6 Million
Key Players
Veolia Environnement SA
First Solar, Inc.
SOLARCYCLE, Inc.
Reiling GmbH & Co. KG
Rinovasol Global Services B.V.
ROSI SAS
Opportunities
  • High-Purity Silicon for Semiconductor-Adjacent Buyers
  • India and Southeast Asia as Greenfield Territory
  • Decommissioning-as-a-Service Bundles
  1. 1 Market Summary | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Technology | |
    2. 2.2 By Sector | |
    3. 2.3 By Region | |
  3. 3 Market Size & Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2024) | |
    2. 3.2 Base Year Assessment (2025) | |
    3. 3.3 Forecast Market Size (2026–2035) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Regulatory Mandates & Producer Responsibility | |
    2. 4.2 First-Generation Module Retirement Wave | |
    3. 4.3 Commodity Economics of Recovered Materials | |
    4. 4.4 Industrial Policy & Domestic Content Incentives | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Collection Logistics & Transport Cost | |
    2. 5.2 Voluntary Regimes & Volume Volatility | |
    3. 5.3 Encapsulant Separation Limitations | |
  6. 6 Opportunities | |
    1. 6.1 High-Purity Silicon Offtake | |
    2. 6.2 Emerging Asia-Pacific Greenfield Capacity | |
    3. 6.3 Decommissioning-as-a-Service | |
    4. 6.4 Recycled-Content Data & Certification | |
    5. 6.5 Second-Life Module Resale | |
  7. 7 Regional Market Share & Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of Middle East & Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Automation & Plant Economics | |
    2. 8.2 Feedstock Contracting & Consolidation | |
    3. 8.3 Recycled Content in Product Standards | |
    4. 8.4 Critical Minerals Policy Alignment | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Process | | |
      1. 9.1.1 Thermal | | |
      2. 9.1.2 Mechanical | | |
      3. 9.1.3 Laser | |
    2. 9.2 By Panel Type | | |
      1. 9.2.1 Crystalline Silicon | | |
      2. 9.2.2 Thin Film | |
    3. 9.3 By Shelf Life | | |
      1. 9.3.1 Normal Loss | | |
      2. 9.3.2 Early Loss | |
    4. 9.4 By Material Recovered | | |
      1. 9.4.1 Glass | | |
      2. 9.4.2 Silicon Wafers | | |
      3. 9.4.3 Silver | | |
      4. 9.4.4 Aluminum | | |
      5. 9.4.5 Other Metals | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 Veolia Environnement SA | | |
      2. 10.3.2 First Solar, Inc. | | |
      3. 10.3.3 SOLARCYCLE, Inc. | | |
      4. 10.3.4 Reiling GmbH & Co. KG | | |
      5. 10.3.5 Rinovasol Global Services B.V. | | |
      6. 10.3.6 ROSI SAS | | |
      7. 10.3.7 We Recycle Solar, Inc. | | |
      8. 10.3.8 Envaris GmbH | | |
      9. 10.3.9 Silrec Corporation | | |
      10. 10.3.10 PV Industries Pty Ltd | | |
      11. 10.3.11 Echo Environmental Holdings | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope & Methodology | |
  13. 13 Detailed Sources & Citations | |
  14. 14 Frequently Asked Questions | | LIST OF TABLES | | Source: Market Research Future (MRFR) Analysis | | LIST OF FIGURES | | Source: Market Research Future (MRFR) Analysis

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By ProcessThermal, Mechanical, LaserMechanicalLaser
By Panel TypeCrystalline Silicon, Thin FilmCrystalline SiliconThin Film
By Shelf LifeNormal Loss, Early LossNormal LossEarly Loss
By Material RecoveredGlass, Silicon Wafers, Silver, Aluminum, Other MetalsGlassSilver
By RegionNorth America, Europe, Asia-Pacific, South America, Middle East & AfricaEuropeAsia-Pacific


Market Segmentation Overview

By Process

Sub-SegmentKey Trend
ThermalPyrolysis-based encapsulant removal expanding at facilities co-located with energy-recovery assets
MechanicalRetains volume leadership through low capital intensity, but faces value-ceiling pressure
LaserSelective ablation scaling rapidly for intact wafer and busbar recovery


Process choice increasingly reflects a strategic decision about where an operator wants to compete. Volume players stay mechanical and optimise logistics; value players invest in thermal-laser sequences and sell into qualified material markets.

By Panel Type

Sub-SegmentKey Trend
Crystalline SiliconDominant feedstock, with recovery focused on wafer integrity and silver capture
Thin FilmHazardous-material handling rules channel volumes into regulated treatment routes


Feedstock composition dictates process design more than any other variable. Crystalline lines optimise for silver and silicon purity, while thin-film operations prioritise containment and semiconductor-layer capture.

By Shelf Life

Sub-SegmentKey Trend
Normal LossPredictable warranty-expiry cohorts underpin long-term capacity planning
Early LossWeather, transport and defect claims generate irregular but high-quality batches


Planning around normal-loss volumes is straightforward; early-loss streams are the operational wildcard. Facilities with flexible intake and insurance-sector relationships capture the premium these batches carry.

By Material Recovered

Sub-SegmentKey Trend
GlassContamination control determines whether output reaches container-grade or construction fill
Silicon WafersPurity upgrading toward solar-grade specifications unlocks step-change pricing
SilverHighest value density; principal target of process innovation
AluminumEstablished smelter routes make frames the most reliably monetised fraction
Other MetalsCopper, tin and indium recovery improving with finer separation technology


Material economics explain almost every capital decision in this industry. Mass sits in glass, margin sits in metals, and the operators that reconcile the two profitably will define the next decade.



Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.