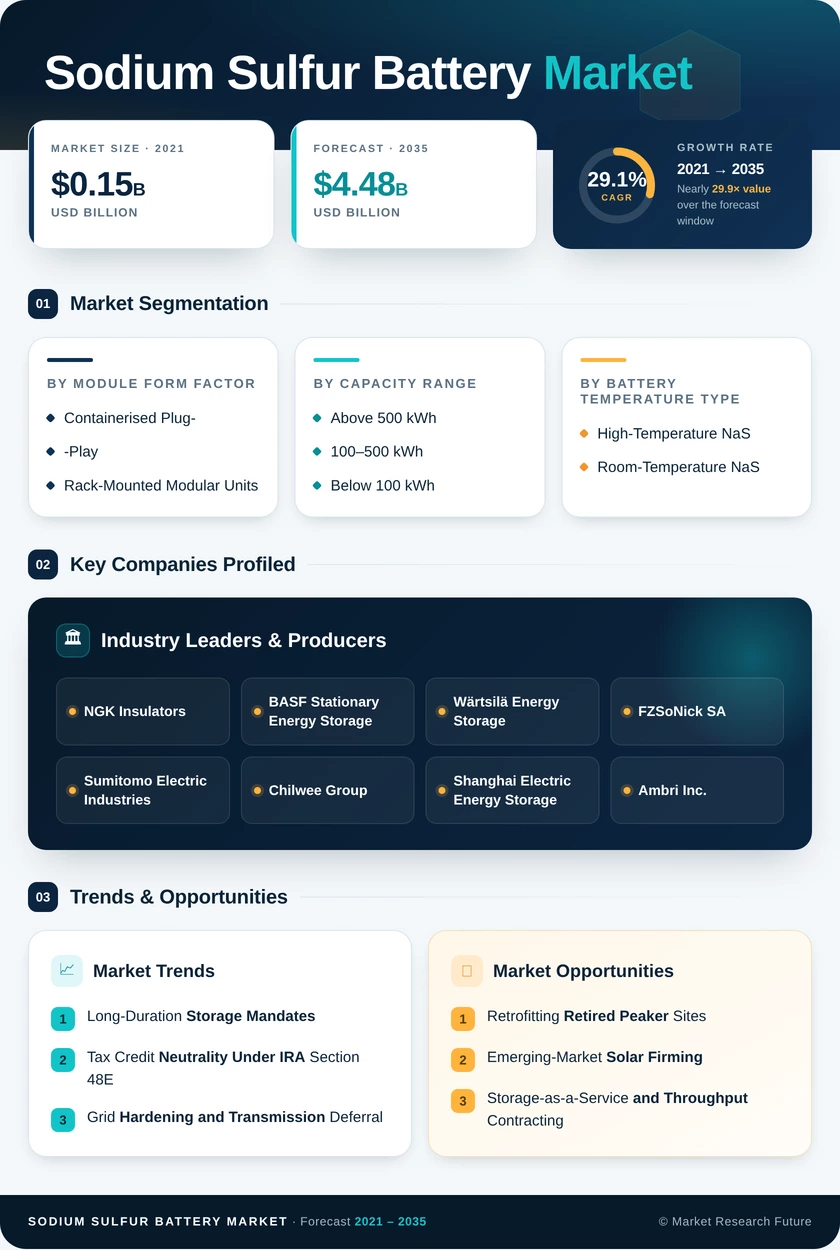
Sodium Sulfur Battery Market (2026 - 2035)

ID: MRFR/EnP/5815-HCR 111 Pages Anshula Mandaokar Last Updated: October 16, 2026
Sodium Sulfur Battery Market Research Report By Module Form Factor (Containerised Plug-and-Play, Rack-Mounted Modular Units), By Capacity Range (Above 500 kWh, 100–500 kWh, Below 100 kWh), By Battery Temperature Type (High-Temperature NaS, Room-Temperature NaS), By Installation Type (Grid-Scale (>10 MWh), Commercial & Industrial (0.5–10 MWh), Residential & Microgrid (<0.5 MWh)), By Application (Renewable Energy Stabilisation, Load-Levelling & Peak Shaving, Backup & Emergency Power, Others (T&D Deferral, Ancillary Services)) - Forecast to 2035
Sodium Sulfur Battery Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)29.1%
2025 Market SizeUSD 0.35 Billion
2035 Market SizeUSD 4.48 Billion
Key Players
NGK Insulators
BASF Stationary Energy Storage
Wärtsilä Energy Storage
FZSoNick SA
Sumitomo Electric Industries
Chilwee Group
Opportunities
  • Retrofitting Retired Peaker Sites
  • Emerging-Market Solar Firming
  • Storage-as-a-Service and Throughput Contracting
  1. 1 Market Overview | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Market Summary & Key Report Takeaways | |
    1. 2.1 Takeaways by Battery Temperature Type | |
    2. 2.2 Takeaways by Module Form Factor | |
    3. 2.3 Takeaways by Installation Type | |
    4. 2.4 Takeaways by Application | |
    5. 2.5 Takeaways by Region | |
  3. 3 Market Size & Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2024) | |
    2. 3.2 Base Year Assessment (2025) | |
    3. 3.3 Forecast Market Size (2026–2035) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Long-Duration Storage Mandates | |
    2. 4.2 Tax Credit Neutrality Under IRA Section 48E | |
    3. 4.3 Grid Hardening and Transmission Deferral | |
    4. 4.4 Driver Impact Scoring Matrix | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Thermal Management Overhead | |
    2. 5.2 Ceramic Electrolyte Supply Concentration | |
    3. 5.3 Competitive Pressure From Lithium Iron Phosphate | |
    4. 5.4 Restraint Impact Scoring Matrix | |
  6. 6 Market Opportunity Analysis | |
    1. 6.1 Retrofitting Retired Peaker Sites | |
    2. 6.2 Emerging-Market Solar Firming | |
    3. 6.3 Storage-as-a-Service and Throughput Contracting | |
    4. 6.4 Industrial Waste-Heat Integration | |
    5. 6.5 Fleet Analytics and Performance Monetisation | |
    6. 6.6 Industry Value Chain Analysis | |
    7. 6.7 Porter's Five Forces Analysis | |
  7. 7 Regional Market Share & Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of Middle East & Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Autonomous Dispatch and Predictive Thermal Control | |
    2. 8.2 Platform Economics and Modular Standardisation | |
    3. 8.3 The Long-Duration Supercycle | |
    4. 8.4 Circularity and Disclosure Pressure | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Module Form Factor | | |
      1. 9.1.1 Containerised Plug-and-Play | | |
      2. 9.1.2 Rack-Mounted Modular Units | |
    2. 9.2 By Capacity Range | | |
      1. 9.2.1 Above 500 kWh | | |
      2. 9.2.2 100–500 kWh | | |
      3. 9.2.3 Below 100 kWh | |
    3. 9.3 By Battery Temperature Type | | |
      1. 9.3.1 High-Temperature NaS | | |
      2. 9.3.2 Room-Temperature NaS | |
    4. 9.4 By Installation Type | | |
      1. 9.4.1 Grid-Scale (>10 MWh) | | |
      2. 9.4.2 Commercial & Industrial (0.5–10 MWh) | | |
      3. 9.4.3 Residential & Microgrid (<0.5 MWh) | |
    5. 9.5 By Application | | |
      1. 9.5.1 Renewable Energy Stabilisation | | |
      2. 9.5.2 Load-Levelling & Peak Shaving | | |
      3. 9.5.3 Backup & Emergency Power | | |
      4. 9.5.4 Others (T&D Deferral, Ancillary Services) | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 NGK Insulators | | |
      2. 10.3.2 BASF Stationary Energy Storage | | |
      3. 10.3.3 Wärtsilä Energy Storage | | |
      4. 10.3.4 FZSoNick SA | | |
      5. 10.3.5 Sumitomo Electric Industries | | |
      6. 10.3.6 Chilwee Group | | |
      7. 10.3.7 Shanghai Electric Energy Storage | | |
      8. 10.3.8 Ambri Inc. | | |
      9. 10.3.9 Eos Energy Enterprises | | |
      10. 10.3.10 Hitachi Energy | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope & Methodology | |
    1. 12.1 Study Period & Base Year | |
    2. 12.2 Valuation Currency & Conversion | |
    3. 12.3 Abbreviations | |
  13. 13 Detailed Sources & Citations | |
  14. 14 Frequently Asked Questions | | LIST OF TABLES | |
  15. TABLE 1 Global Sodium Sulfur Battery Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Global Sodium Sulfur Battery Market – Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 | |
  19. TABLE 5 Global Market Size, by Module Form Factor, 2021–2035 (USD Billion) | |
  20. TABLE 6 Global Market Size, by Capacity Range, 2021–2035 (USD Billion) | |
  21. TABLE 7 Global Market Size, by Battery Temperature Type, 2021–2035 (USD Billion) | |
  22. TABLE 8 Global Market Size, by Installation Type, 2021–2035 (USD Billion) | |
  23. TABLE 9 Global Market Size, by Application, 2021–2035 (USD Billion) | |
  24. TABLE 10 Global Market Size, by Region, 2021–2035 (USD Billion) | |
  25. TABLE 11 North America Market Size, by Country, 2021–2035 (USD Billion) | |
  26. TABLE 12 Europe Market Size, by Country, 2021–2035 (USD Billion) | |
  27. TABLE 13 Asia-Pacific Market Size, by Country, 2021–2035 (USD Billion) | |
  28. TABLE 14 South America Market Size, by Country, 2021–2035 (USD Billion) | |
  29. TABLE 15 Middle East & Africa Market Size, by Country, 2021–2035 (USD Billion) | |
  30. TABLE 16 North America Market Size, by Application, 2021–2035 (USD Billion) | |
  31. TABLE 17 Europe Market Size, by Installation Type, 2021–2035 (USD Billion) | |
  32. TABLE 18 Asia-Pacific Market Size, by Battery Temperature Type, 2021–2035 (USD Billion) | |
  33. TABLE 19 South America Market Size, by Capacity Range, 2021–2035 (USD Billion) | |
  34. TABLE 20 Middle East & Africa Market Size, by Module Form Factor, 2021–2035 (USD Billion) | |
  35. TABLE 21 Competitive Benchmarking Matrix, 2026 | |
  36. TABLE 22 Company Profiles – Key Players | |
  37. TABLE 23 Recent Developments & Strategic Announcements, 2023–2025 | |
  38. TABLE 24 Report Scope & Methodology Summary | |
  39. TABLE 25 Detailed Sources & Citations Index | | Source: Market Research Future Analysis | | LIST OF FIGURES | |
  40. FIGURE 1 Market Dynamics – Drivers, Restraints, Opportunities & Challenges | |
  41. FIGURE 2 Industry Value Chain Analysis | |
  42. FIGURE 3 Porter's Five Forces Analysis | |
  43. FIGURE 4 Global Market Size Trend & Forecast, 2021–2035 (USD Billion) | |
  44. FIGURE 5 Year-over-Year Growth Trajectory, 2022–2035 | |
  45. FIGURE 6 Share by Module Form Factor, 2025 vs 2035 | |
  46. FIGURE 7 Share by Capacity Range, 2025 vs 2035 | |
  47. FIGURE 8 Share by Battery Temperature Type, 2025 vs 2035 | |
  48. FIGURE 9 Share by Installation Type, 2025 vs 2035 | |
  49. FIGURE 10 Share by Application, 2025 vs 2035 | |
  50. FIGURE 11 Regional Share Distribution, 2025 | |
  51. FIGURE 12 Regional CAGR Comparison, 2026–2035 | |
  52. FIGURE 13 Country-Level Contribution Heat Map | |
  53. FIGURE 14 Competitive Landscape – Revenue Share Positioning, 2026 | |
  54. FIGURE 15 Strategic Positioning Quadrant of Key Players | | Source: Market Research Future Analysis

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Module Form FactorContainerised Plug-and-Play; Rack-Mounted Modular UnitsContainerised Plug-and-PlayRack-Mounted Modular Units
By Capacity RangeAbove 500 kWh; 100–500 kWh; Below 100 kWhAbove 500 kWh100–500 kWh
By Battery Temperature TypeHigh-Temperature NaS; Room-Temperature NaSHigh-Temperature NaSRoom-Temperature NaS
By Installation TypeGrid-Scale (>10 MWh); Commercial & Industrial (0.5–10 MWh); Residential & Microgrid (<0.5 MWh)Grid-Scale (>10 MWh)Commercial & Industrial (0.5–10 MWh)
By ApplicationRenewable Energy Stabilisation; Load-Levelling & Peak Shaving; Backup & Emergency Power; OthersRenewable Energy StabilisationLoad-Levelling & Peak Shaving
By GeographyNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaAsia-PacificNorth America


Market Segmentation Overview

By Module Form Factor

Sub-SegmentKey Trend
Containerised Plug-and-PlayFactory pre-commissioning cuts site construction to under nine months
Rack-Mounted Modular UnitsIndoor retrofit demand rising among data centres and hospitals


Form factor is now a procurement decision more than an engineering one. Utilities want delivery certainty, which containers provide; constrained commercial sites want density, which racks provide.

By Capacity Range

Sub-SegmentKey Trend
Above 500 kWhThermal enclosure overhead amortises favourably at utility scale
100–500 kWhStandardised debt products unlocking mid-market buyers
Below 100 kWhTelecom and remote infrastructure niche with premium pricing


Scale economics still favour the largest systems, but the mid-band is where new customer acquisition is happening fastest as financing structures mature.

By Battery Temperature Type

Sub-SegmentKey Trend
High-Temperature NaSTwenty-year field data underpins lender confidence
Room-Temperature NaSPilot programs targeting elimination of standby heating load


Bankability keeps high-temperature designs dominant through the forecast period. Room-temperature chemistry represents the technical frontier and the primary threat to incumbent share after 2030.

By Installation Type

Sub-SegmentKey Trend
Grid-Scale (>10 MWh)Duration-specific procurement mandates expanding across jurisdictions
Commercial & Industrial (0.5–10 MWh)Demand-charge arbitrage plus resilience value stacking
Residential & Microgrid (<0.5 MWh)Island and off-grid reliability applications


Grid-scale volume drives revenue; the commercial tier drives growth rate. Vendors are restructuring sales organisations to serve both channels simultaneously.

By Application

Sub-SegmentKey Trend
Renewable Energy StabilisationCurtailment penalties making firming economically mandatory
Load-Levelling & Peak ShavingWidening time-of-use spreads in deregulated markets
Backup & Emergency PowerCritical facility resilience codes tightening post-disaster
Others (T&D Deferral, Ancillary)Network operators treating storage as a capex avoidance tool


Application mix is shifting steadily from pure renewable integration toward multi-revenue dispatch strategies, a transition that rewards chemistries with unlimited cycling tolerance.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.