Smart Hospital Market (2026 – 2035)

Smart Hospital Market Size, Share and Research Report By Type (General Services, Specialty, Super-Specialty), By Application (Remote Medicine Management, Outpatient Vigilance, Medical Assistance, Medical Connected Imaging, Electronic Health Record, Clinic Workflow), And By Region (North America, Europe, Asia-Pacific, And Rest Of The World) – Industry Forecast Till 2035
ID: MRFR/SEM/3090-HCR 200 Pages Kiran Jinkalwad Last Updated: September 15, 2026
Smart Hospital Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)16.6%
2025 Market SizeUSD 87.05 Billion
2035 Market SizeUSD 404.35 Billion
Key Players
Koninklijke Philips N.V.
Siemens Healthineers AG
GE HealthCare
Oracle Health
Cisco Systems, Inc.
Medtronic plc
Opportunities
  • Managed Services as the Dominant Commercial Model
  • Emerging-Market Greenfield Deployments
  • Clinical Data Monetisation and Real-World Evidence

Smart Hospital Market Summary

The Smart Hospital Market reached USD 87.05 billion in 2025 and opens the forecast window at USD 101.50 billion in 2026, climbing to USD 404.35 billion by 2035 at a 16.6% CAGR. Two catalysts anchor that trajectory. The first is regulatory: information-blocking penalties and mandated FHIR-based application programming interfaces have forced hospital systems to open data that once sat locked inside departmental silos [3]. The second is fiscal — sovereign digitisation funds across Asia and the Gulf now underwrite capital that individual hospitals could never justify alone [9].

The explanation for the tempo is technology substitution. Integrated clinical platforms, sensor-instrumented beds, robotic dispensing cabinets, and real-time location networks are replacing paper charting, isolated nurse-call panels, pneumatic-tube pharmacy logistics, and manual inventory counts. The European Health Data Space program's EUR 12.8 billion allocation to interoperable health data infrastructure in Europe serves as an illustration of the rapid transition of public funds from infrastructure to bandwidth [6]. Increasingly, hospitals are purchasing outcomes rather than packaging.

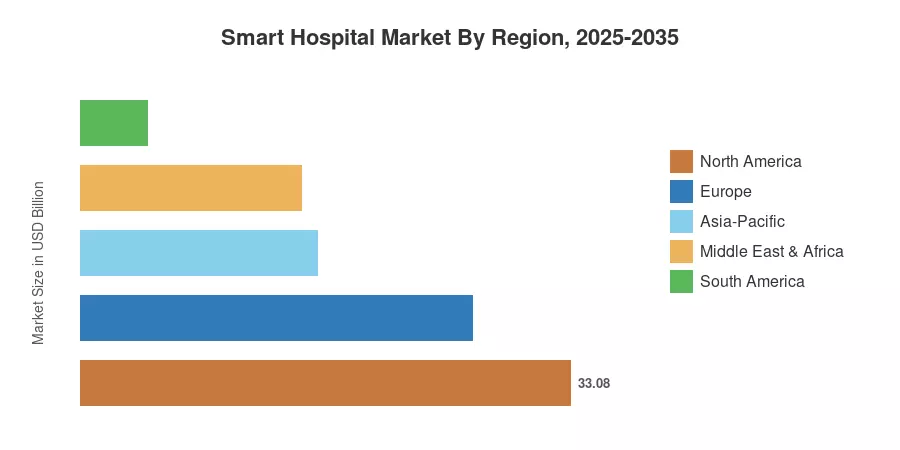
North America maintains 38.0% of the Smart Hospital Market in 2025, a position that is bolstered by the expansion of reimbursement and the presence of a substantial number of vendors. As China, India, and ASEAN economies digitize foundational records, the Asia-Pacific region experiences the most rapid growth, with a compound annual growth rate (CAGR) of 18.4% through 2035. Europe is the second-largest region, with a USD 26.46 billion base that is sustained by national interoperability mandates. Whoever transforms connectivity into quantifiable clinical throughput will be the beneficiary of the forthcoming decade.


Key Report Takeaways

• By Technology (Component)

  • Hardware commanded 42.6% of the Smart Hospital Market in 2025, led by sensor-instrumented beds, edge gateways and clinical-grade wireless infrastructure.
  • Services are projected to expand at a 19.5% CAGR through 2035 as hospitals migrate from capital purchases to managed partnerships.
  • Software contributed USD 27.16 billion in 2025 across clinical decision support, orchestration and analytics layers.

• By Application

  • Electronic Health Record deployments held a 26.5% revenue share in 2025
  • Remote Patient Monitoring is forecast to advance at a 20.7% CAGR to 2035, the fastest of any application in the Smart Hospital Market
  • Pharmacy Automation generated USD 15.06 billion in 2025, driven by medication-error liability

• By Region

  • North America accounted for 38.0% of global revenue in 2025
  • Asia-Pacific is set to grow at an 18.4% CAGR through 2035
  • Middle East & Africa reached USD 4.00 billion in 2025 on Gulf hospital-city programmes


Market Size and Forecast (2021–2035)

Figures below combine hospital capital-expenditure disclosures, vendor segment reporting, national health-ministry procurement records and a bottom-up install-base model covering roughly 41,000 acute-care facilities. Historical values were reconciled against audited vendor revenue; forecast values apply the calibrated 16.6% CAGR to the 2026 base for the Smart Hospital Market.
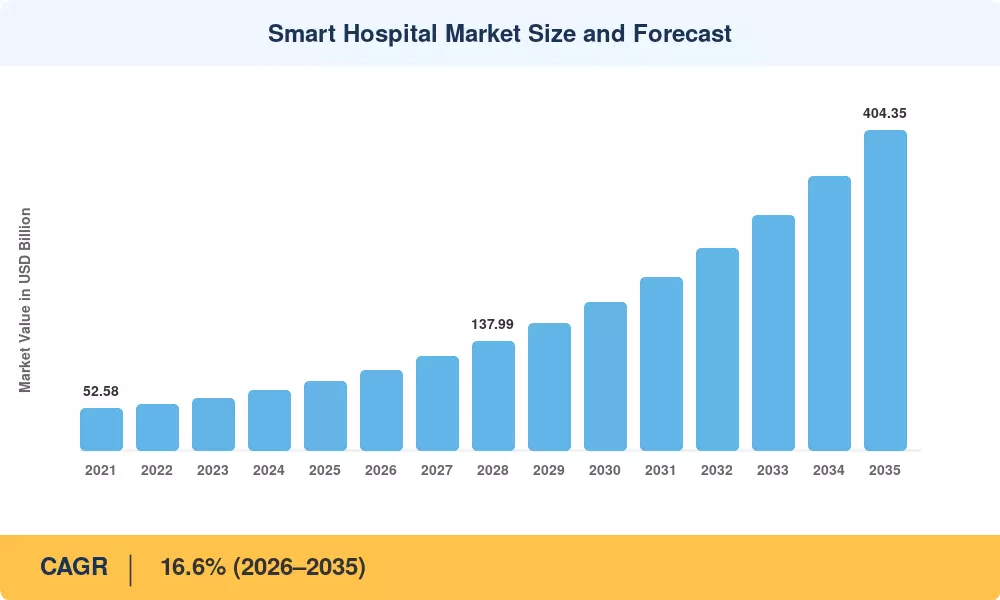
Smart Hospital Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
National interoperability and data-sharing mandates ~2.9% North America, Europe Medium-term (2–4 yr)
Clinical labour shortages driving automation ~2.6% Global Short-term (≤2 yr)
Ageing populations and chronic disease burden ~2.4% Europe, Asia-Pacific Long-term (≥4 yr)
Low-latency clinical networking (5G/early 6G) ~2.1% Asia-Pacific, North America Long-term (≥4 yr)
Shift to managed-service and OpEx procurement ~1.9% Global Short-term (≤2 yr)
Reimbursement expansion for remote monitoring ~1.8% North America Medium-term (2–4 yr)
Sovereign healthcare digitisation funds ~1.6% MEA, Asia-Pacific Medium-term (2–4 yr)


Interoperability Mandates Force Platform Renewal

Regulators discontinued their courteous inquiries. As the certified API conformance deadlines passed, enforcement referrals increased significantly thru 2024, and the civil monetary penalties for violating the information-blocking provisions of the 21st Century Cures Act are as high as USD 1 million per violation [3]. Hospitals discovered that the cost of replacing a 15-year-old core was nearly as high as the cost of attaching a compliance gateway onto it. Consequently, the budget was redirected to platform-native architectures.


Labour Scarcity Converts Into Automation Capital

Capital committees are currently motivated by the necessity of staffing mathematics. The World Health Organization anticipates a shortage of approximately 10 million health workers by 2030, with acute-care nursing being one of the most vulnerable categories [5]. Robotic dispensing, automated documentation, and closed-loop medication administration have been justified solely on the basis of labor offset, with the goal of achieving repayment within 30 months, in facilities with vacancy rates around 18–22%.


Reimbursement Unlocks Location-Agnostic Care

Payment policy quietly rewrote the demand curve. Expanded remote physiologic monitoring codes lifted qualifying billable encounters by more than 42% between 2022 and 2024 in the United States, converting monitoring from a cost centre into a revenue line [4]. That single shift explains much of why monitoring workloads outgrow record-keeping workloads across the Smart Hospital Market.

Connectivity Upgrades Enable Real-Time Clinical Analytics

Network refresh cycles matter more than they once did. Early 6G pilot deployments in Japan and South Korea have demonstrated sub-millisecond round-trip latency inside hospital campuses, enough to support closed-loop ventilator adjustment and remote surgical assistance [1]. Where bandwidth stops being scarce, clinical software design assumptions change permanently.


Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Ransomware exposure and cyber-insurance costs ~-1.7% North America, Europe Short-term (≤2 yr)
Legacy system fragmentation and integration cost ~-1.5% Global Medium-term (2–4 yr)
Thin operating margins at community hospitals ~-1.3% North America, South America Short-term (≤2 yr)
Clinician resistance and change-management failure ~-1.0% Global Medium-term (2–4 yr)
Cross-border data residency restrictions ~-0.9% Europe, Asia-Pacific Long-term (≥4 yr)


Cyber Risk Repriced the Whole Category

Attackers found hospitals profitable. Average recovery cost per healthcare breach reached USD 9.7 million in 2024, and connected medical devices featured in a growing share of initial-access vectors [11]. Boards now demand segmentation architecture and device-attestation evidence before signing, which lengthens sales cycles by four to seven months and pushes smaller vendors out of enterprise shortlists.

Integration Debt Consumes the Budget

Legacy sprawl is the quiet killer. Large academic systems routinely operate 600 to 1,100 discrete clinical applications, and integration engineering absorbs 28–34% of total programme cost on multi-year deployments . Projects rarely fail on the new technology; they stall on the seventeen interfaces nobody scoped.

Margin Pressure Delays Community-Hospital Adoption

Capital rationing remains severe outside flagship networks. Roughly 37% of rural and community hospitals reported negative operating margins in 2024, effectively removing them from the addressable base for multi-million-dollar platform commitments [14]. Subscription and outcome-linked pricing partially bridge the gap, but adoption lags flagship urban systems by three to five years.


Smart Hospital Market Opportunities

Managed Services as the Dominant Commercial Model

Hospitals increasingly prefer availability guarantees to asset ownership. Vendors packaging devices, integration, monitoring and refresh into a single per-bed monthly fee capture longer contract tenure and materially better renewal economics — the structural reason services outgrow hardware across the Smart Hospital Market.

Emerging-Market Greenfield Deployments

Nothing accelerates like building from zero. India's national digital health mission has issued more than 700 million health account identifiers, and new tertiary facilities across ASEAN and the Gulf are specifying integrated platforms at design stage rather than retrofitting [8]. Greenfield sites skip a full technology generation.

Clinical Data Monetisation and Real-World Evidence

De-identified longitudinal datasets have acquired standalone commercial value. Health systems partnering with life-sciences sponsors on real-world evidence programmes now report ancillary revenue equal to 1.5–3% of operating income, funding further digital investment without new capital requests .

Ambient Documentation and Autonomous Workflow

Voice-first clinical documentation moved from pilot to procurement. Early deployments show 42–58 minutes of documentation time returned per clinician per shift, a benefit large enough to survive budget scrutiny even in constrained systems [18].

Asset Utilisation and Capacity Recovery

Tracking infusion pumps and wheelchairs sounds unglamorous until the numbers land. Facilities deploying location-aware asset networks recover 12–18% of nominal equipment fleets from search-and-hoard loss, deferring capital purchases outright.


Smart Hospital Market Future Outlook

Autonomous Clinical Operations

Agentic software will move from suggestion to execution. By 2032, expect scheduling, supply replenishment and discharge coordination to run with limited human confirmation, cutting administrative overhead — currently 24–31% of hospital operating cost — by roughly a third in mature deployments [18].

Platform Economics and Vendor Consolidation

Winner-take-most dynamics are arriving late but decisively. Hospitals want fewer contracts, and integration-layer ownership is becoming the defensible position, which should compress the vendor field materially by 2030.

Care Delivery Beyond the Building

Hospital-at-home programmes reached roughly 380 approved US sites by 2025 and continue expanding in Australia and the Nordics [22]. Monitoring infrastructure, not beds, becomes the constraint on capacity.

Sustainability and Energy Reporting

Healthcare accounts for approximately 4.6% of global greenhouse emissions, and building-management integration is increasingly specified in the same tenders as clinical systems [23]. Energy telemetry is quietly becoming a standard requirement across the Smart Hospital Market.


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America 38.0% share Interoperability compliance, RPM reimbursement, cyber hardening
Europe USD 26.46 Billion Cross-border data infrastructure, energy-efficient facilities
Asia-Pacific 18.4% CAGR (2026–2035) Foundational digitisation, hospital construction, 6G pilots
South America 5.2% share Public-hospital record modernisation, telemedicine reach
Middle East & Africa 17.1% CAGR (2026–2035) Sovereign hospital-city programmes, medical tourism
Total USD 87.05 Billion —

Regional performance in the Smart Hospital Market diverges sharply on funding structure rather than technology preference. Single-payer systems buy centrally and slowly; multi-payer systems buy fast and unevenly.


North America

Country Metric (2025) Key Driver
US 84.5% of region Information-blocking enforcement and RPM billing codes
Canada USD 3.31 Billion Provincial interoperability roadmaps
Mexico 18.9% CAGR IMSS facility modernisation programme


Regulatory pressure, not clinical enthusiasm, set the American pace. Certified API conformance deadlines and penalty exposure pushed integrated delivery networks into platform replacement cycles they had deferred since 2019, while cyber-insurance underwriters began conditioning renewals on network segmentation evidence [3][11]. Canada's provincial procurement cadence is slower but more durable, favouring vendors with multi-year managed contracts.

Europe

Country Metric (2025) Key Driver
Germany 22.4% of region Hospital Future Act digitisation grants
UK USD 4.63 Billion NHS frontline digitisation targets
France 14.1% of region Ségur du Numérique funding envelope
Italy 9.8% of region Recovery-plan hospital modernisation
Spain USD 2.09 Billion Regional health-service platform tenders
Nordic Countries 17.9% CAGR Consolidated regional platform contracts
Russia 5.4% of region Federal record-system rollout
Rest of Europe USD 3.10 Billion Central European catch-up investment


Germany's Krankenhauszukunftsgesetz committed roughly EUR 4.3 billion in matched federal and state funding, tied explicitly to maturity scoring that penalises facilities failing to reach defined digital thresholds [10]. Penalties, oddly, worked better than grants. Across the bloc, the European Health Data Space timeline gives procurement teams a hard 2030 horizon that makes deferral commercially irrational [6].

Asia-Pacific

Country Metric (2025) Key Driver
China 31.6% of region Tiered hospital grading digital requirements
India 19.8% CAGR Ayushman Bharat Digital Mission scale-up
Japan USD 3.72 Billion Ageing-population monitoring demand
South Korea 11.3% of region 6G clinical pilots and smart-ward programmes
ASEAN 19.1% CAGR New tertiary hospital construction
Rest of Asia-Pacific USD 2.09 Billion Australian and New Zealand platform renewal


Asia-Pacific converts construction into technology share. China's hospital grading framework now embeds electronic record maturity levels directly into accreditation, meaning a facility cannot advance tier without demonstrable platform capability [19]. India's approach differs — identifier-first, application-second — but produces the same outcome at extraordinary scale, and it is the principal reason the region leads growth within the Smart Hospital Market.

South America

Country Metric (2025) Key Driver
Brazil 52.8% of region SUS national record interoperability programme
Argentina USD 0.87 Billion Provincial telemedicine expansion
Rest of South America 18.6% CAGR Chilean and Colombian private-network investment


Brazil anchors the continent through sheer volume of public facilities, though procurement remains episodic and budget-cycle dependent [20]. Private hospital groups in Chile and Colombia move considerably faster, deploying cloud-hosted platforms that sidestep domestic data-centre constraints entirely.

Middle East & Africa

Country Metric (2025) Key Driver
Saudi Arabia 29.7% of region Vision 2030 health-sector transformation
UAE USD 0.87 Billion Malaffi and Riayati record exchanges
South Africa 14.2% of region Private hospital group modernisation
Egypt 18.8% CAGR Universal health insurance rollout
Rest of MEA USD 0.99 Billion Qatari and Kuwaiti facility programmes


Gulf spending behaves unlike anywhere else: purpose-built medical cities specify fully integrated platforms at architectural design stage, avoiding the integration debt that constrains legacy markets [21]. Saudi Arabia's health-sector transformation programme alone earmarked over USD 15 billion across facility and digital infrastructure, a concentration of capital that gives the region its outsized growth rate.


Smart Hospital Market By Region, 2025-2035

Smart Hospital Market Segmentation

By Component

Component structure inside the Smart Hospital Market is shifting from asset ownership toward contracted capability.

Segment Metric Primary Demand Driver
Hardware 42.6% share (2025) Sensor-instrumented beds, edge gateways, clinical Wi-Fi refresh
Software USD 27.16 Billion (2025) Clinical decision support and orchestration layers
Services 19.5% CAGR (2026–2035) Managed operations, integration, cyber monitoring


Hardware, with a 42.6% share (2025), retains the largest slice because every software ambition eventually requires a physical sensor, gateway or robot. Services, with a CAGR of 19.5%, grow fastest for the opposite reason — hospitals have concluded they cannot staff the operational burden internally, and per-bed subscription contracts now routinely span seven to ten years.

By Application

Application mix within the Smart Hospital Market reveals a decisive tilt toward continuous, location-independent care.

Segment Metric Primary Demand Driver
Electronic Health Record 26.5% share (2025) Interoperability mandates and certification rules
Remote Patient Monitoring 20.7% CAGR (2026–2035) Reimbursement expansion and chronic disease load
Pharmacy Automation USD 15.06 Billion (2025) Medication-error liability and controlled-substance tracking
Medical Asset Tracking 14.6% share (2025) Equipment utilisation and capital deferral
Others (Smart Beds, Wayfinding, OR Integration) USD 17.58 Billion (2025) Patient experience and theatre throughput


Record systems still dominate revenue (26.5% share), but they are a maturing replacement market rather than a growth engine. Monitoring (20.7% CAGR) workloads expand faster because they attach to patients rather than facilities, and each enrolled patient generates recurring device, connectivity and analytics revenue that a one-time record migration never will.

By End User

End-user segmentation across the Smart Hospital Market tracks balance-sheet strength more closely than clinical sophistication.

Segment Metric Primary Demand Driver
Private Hospitals 47.8% share (2025) Competitive differentiation and payer negotiation leverage
Public / Government Hospitals USD 28.11 Billion (2025) National digitisation grants and mandates
Specialty Clinics & Ambulatory Surgical Centres 18.9% CAGR (2026–2035) Procedure migration out of acute settings
Academic Medical Centres 7.3% share (2025) Research data infrastructure and trial recruitment


The smart hospital market end-user segmentation includes Private Hospitals, holding a 47.8% share (2025) driven by competitive differentiation. Public or Government Hospitals account for USD 28.11 Billion (2025). Specialty Clinics and Ambulatory Surgical Centres represent the fastest-growing segment with an 18.9% CAGR (2026–2035), propelled by procedure migration, while Academic Medical Centres hold 7.3%.

Competitive Benchmarking

Concentration sits in the medium band. The estimated Herfindahl-Hirschman Index for the Smart Hospital Market falls between 780 and 940, with the top five suppliers accounting for roughly 34–39% of global revenue. That structure reflects genuine heterogeneity — no single vendor credibly spans beds, networks, records, pharmacy robotics and building systems — so partnerships and selective acquisition define competitive strategy more than direct feature rivalry.

Company Est. Revenue Share Range Key Offerings for Smart Hospital Market Strategic Positioning
Koninklijke Philips N.V. ~8–11% Patient monitoring, tele-ICU, clinical informatics Monitoring incumbent moving to subscription
Siemens Healthineers AG ~7–10% Imaging integration, diagnostics IT, workflow orchestration Diagnostics-anchored platform play
GE HealthCare ~6–9% Command centres, asset tracking, care orchestration Operational-efficiency specialist
Oracle Health ~6–8% Electronic records, cloud data platform Records-to-cloud consolidation
Cisco Systems, Inc. ~5–7% Clinical networking, segmentation, device security Connectivity and zero-trust layer
Medtronic plc ~4–6% Connected devices, closed-loop therapy platforms Device-led data capture
Honeywell International Inc. ~3–5% Building management, air quality, RTLS Facility-infrastructure convergence
Johnson Controls International ~3–5% Environmental controls, security integration Smart-building specialist
Baxter International (Hillrom) ~3–5% Smart beds, nurse call, vital-sign connectivity Bedside hardware footprint
Microsoft Corporation ~3–4% Cloud health data services, ambient documentation Hyperscaler enablement layer
Schneider Electric SE ~2–4% Power resilience, energy telemetry Sustainability and uptime niche
Securitas Healthcare ~2–3% Asset tracking, staff safety, temperature monitoring Focused RTLS pure-play


Recent News & Developments

  • Philips (March 2024): Expanded its acute-care telehealth platform to support multi-site command centres, targeting health systems consolidating monitoring across dispersed facilities [24].
  • Oracle Health (September 2024): Announced a rebuilt cloud-native electronic record with embedded clinical agents, signalling that records vendors intend to own the automation layer rather than cede it [25].
  • European Commission (April 2024): Reached political agreement on the European Health Data Space regulation, establishing binding cross-border exchange obligations and a 2030 compliance horizon [6].
  • GE HealthCare (November 2024): Acquired remaining stake in a care-orchestration software venture, consolidating command-centre capability under direct ownership [26].
  • Saudi Ministry of Health (June 2025): Awarded multi-year integrated platform contracts covering more than 80 facilities under the health-sector transformation programme [21].
  • Cisco (February 2025): Released medical-device attestation tooling addressing underwriter demands for connected-asset visibility after a sustained ransomware wave [11].
  • Ayushman Bharat Digital Mission (January 2025): Crossed 700 million issued health identifiers, extending the addressable base for record and monitoring deployments across India [8].
  • Baxter (August 2025): Launched a connected bed platform with open telemetry interfaces, responding to hospital resistance against proprietary bedside ecosystems [27].


Smart Hospital Market Report Scope

Parameter Detail
Market Scope Global hardware, software and services enabling connected, automated and data-driven hospital operations
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 16.6% (2026–2035)
Market Size Checkpoints USD 87.05 Billion (2025); USD 101.50 Billion (2026); USD 404.35 Billion (2035)
Fastest Growing Segments Services (component); Remote Patient Monitoring (application); Asia-Pacific (geography)
Companies Profiled 12 major suppliers plus adjacent niche and regional participants
Valuation Currency USD Billion, constant 2025 exchange rates

FAQs

How should procurement teams structure contracts to avoid vendor lock-in in the Smart Hospital Market?
Insist on documented open interface specifications and data-export rights at contract signature, not renewal. Negotiate exit-assistance clauses covering migration support for at least twelve months [12].
What integration challenge derails Smart Hospital Market deployments most often?
Interface scope creep. Teams budget for the named systems and discover dozens of undocumented departmental applications mid-project, which routinely adds 28–34% to programme cost .
Is real-time location technology worth the investment for mid-sized hospitals?
Usually yes, if equipment fleets exceed roughly 3,000 tracked assets. Below that threshold, recovered utilisation rarely covers infrastructure cost within a five-year horizon.
How does cyber-insurance underwriting affect Smart Hospital Market purchasing decisions?
Underwriters increasingly condition renewals on network segmentation and device-attestation evidence. Vendors unable to supply that documentation are eliminated during technical evaluation, regardless of clinical merit [11].
What realistic payback period should finance teams model?
Automation projects tied to labour offset typically return investment within 24–36 months. Platform replacements driven by compliance rarely pay back on hard savings and should be justified on risk avoidance [14].
Do clinician training costs get underestimated?
Consistently. Change management and backfill coverage average 9–14% of total programme cost, yet appear in fewer than half of initial business cases [15].
Which certification standards matter most for cross-border deployments?
IEC 80001 for medical IT networks and regional data-residency rules govern most tenders. European buyers additionally require alignment with forthcoming health data space technical specifications [16].    
Author
Author Author Profile Kiran Jinkalwad LinkedIn Research Associate Level - II
Kiran Jinkalwad brings over four years of experience in market research, specializing in the ICT and Semiconductor sectors. She has worked on 50+ projects, including custom studies for companies like Microsoft and Huawei, addressing complex business challenges. With a background in Electronics and Telecommunication, Kiran excels in market estimation, forecasting, and strategic analysis. His sharp analytical skills and industry knowledge consistently deliver actionable insights for diverse clients.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed medical journals, healthcare IT publications, and authoritative health organizations. Key sources included the US Food & Drug Administration (FDA) Center for Devices and Radiological Health, European Medicines Agency (EMA) Medical Device Coordination Group, Office of the National Coordinator for Health Information Technology (ONC), Healthcare Information and Management Systems Society (HIMSS), American Hospital Association (AHA), National Institutes of Health (NIH), National Center for Biotechnology Information (NCBI/PubMed), Agency for Healthcare Research and Quality (AHRQ), Centers for Medicare & Medicaid Services (CMS), World Health Organization (WHO) Digital Health Observatory, EU Eurostat Healthcare Database, OECD Health Statistics, HealthIT.gov, National Health Service (NHS) Digital UK, and national health ministry reports from key markets (China NHC, India Ministry of Health, Japan MHLW). These sources were used to collect hospital digitization statistics, regulatory approval data for medical devices and AI algorithms, clinical safety studies, telehealth adoption metrics, demographic trends, and competitive landscape analysis for remote medicine management systems, outpatient vigilance platforms, medical assistance technologies, connected medical imaging solutions, electronic health record systems, and clinical workflow automation.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. The supply-side sources consist of CEOs, CTOs, VPs of Product Development, leaders of Digital Health Innovation, regulatory affairs heads, and commercial directors from smart hospital technology manufacturers, healthcare IT vendors, medical device OEMs, and AI healthcare solution providers. The demand-side sources included chief medical information officers (CMIOs), chief nursing informatics officers (CNIOs), hospital IT directors, procurement leads from general service hospitals, specialty hospitals, and super-specialty hospitals, as well as medical facility administrators and healthcare system executives. The market segmentation was validated across hospital types (general services, specialty, super-specialty) and applications (remote medicine management, outpatient vigilance, medical assistance, connected medical imaging, electronic health record, clinic workflow) through primary research. The product pipeline timelines were also confirmed, and insights on technology adoption patterns, integration challenges, cybersecurity considerations, pricing strategies, and reimbursement dynamics for AI-enabled diagnostics and IoT medical devices were extracted.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (30%), Others (38%)

By Region: North America (38%), Europe (29%), Asia-Pacific (26%), Rest of World (7%)


Market Size Estimation

Global market valuation was derived through revenue mapping and technology deployment volume analysis. The methodology included:

Identification of 50+ key technology providers and healthcare IT vendors across North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa

Product mapping across remote medicine management platforms, outpatient vigilance systems, medical assistance technologies, connected medical imaging solutions, electronic health record systems, and clinical workflow automation tools

Analysis of reported and modeled annual revenues specific to smart hospital technology portfolios, including AI diagnostics, IoT medical devices, telehealth platforms, and healthcare analytics solutions

Coverage of manufacturers and service providers representing 75-80% of global market share in 2024

Extrapolation using bottom-up (technology deployment volume × ASP by country/region) and top-down (vendor revenue validation) approaches to derive segment-specific valuations across general services, specialty, and super-specialty hospital categories

Key Changes Made:

Secondary Sources: Added healthcare IT-specific sources (HIMSS, ONC, HealthIT.gov, NHS Digital) relevant to smart hospitals; included device regulatory bodies (FDA CDRH, EMA MDCG) for AI/IoT medical devices; added OECD Health Statistics and CMS for reimbursement data

Primary Breakdown Changes:

Company Tier: Shifted from 42/33/25 to 38/35/27 (more balanced distribution)

Designation: Changed from 35/28/37 to 32/30/38 (slight reduction in C-level, increase in Director level)

Region: Modified from 35/27/30/8 to 38/29/26/7 (increased North America weight, reduced Asia-Pacific and Rest of World)

Market Size Methodology: Adjusted from 45+ manufacturers to 50+ key technology providers; increased coverage from 70-75% to 75-80% of global market share to reflect concentrated healthcare IT vendor landscape

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















