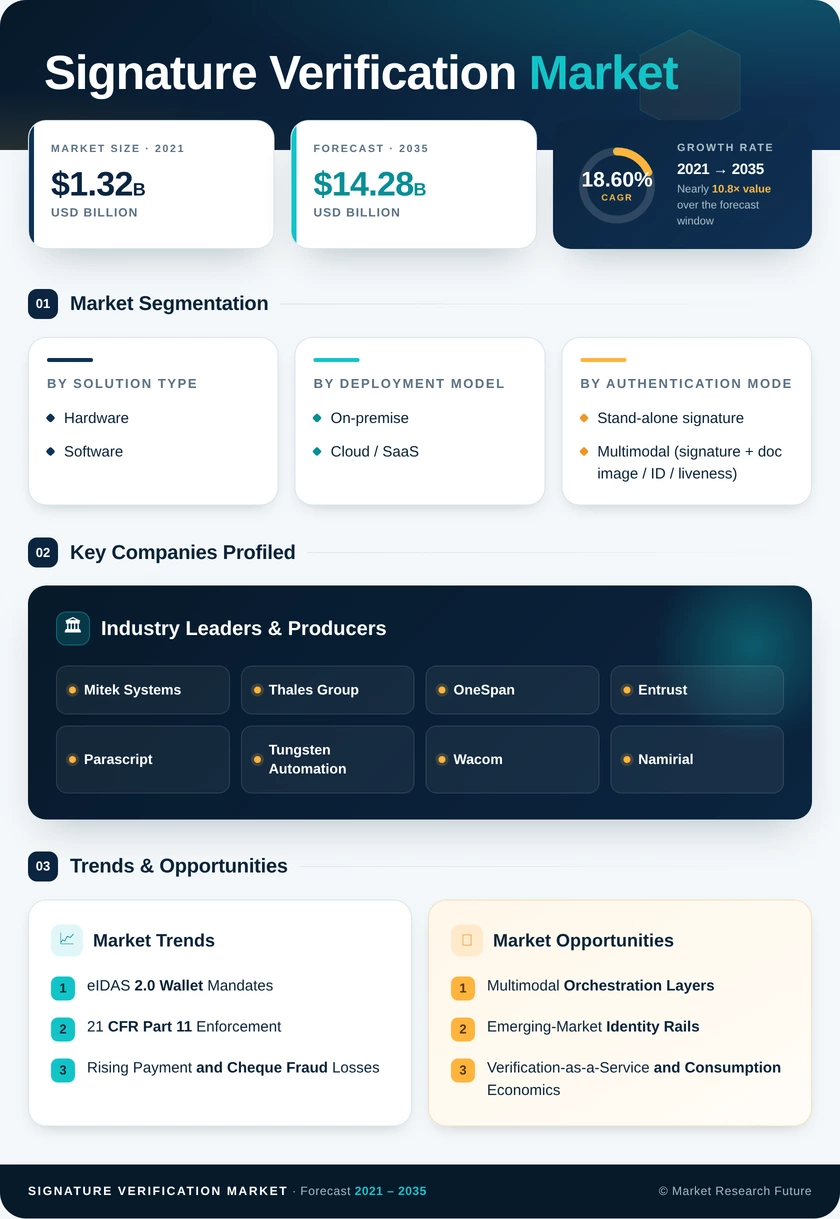
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Solution Type | Hardware; Software | Software (53.3% revenue share, 2025) | Software |
| By Deployment Model | On-premise; Cloud / SaaS | On-premise (50.1% revenue share, 2025) | Cloud / SaaS (25.2% CAGR, 2026–2035) |
| By Authentication Mode | Stand-alone signature; Multimodal (signature + doc image / ID / liveness) | Stand-alone signature (65.8% revenue share, 2025) | Multimodal (21.5% CAGR, 2026–2035) |
| By End-user Industry | Financial Services; Healthcare; Government and Elections; Logistics; Legal and Real Estate | Financial Services (21.9% revenue share, 2025) | Government and Elections (22.8% CAGR, 2026–2035) |
Market Segmentation Overview
By Solution Type
| Sub-Segment | Key Trend |
| Hardware | Certified pads and sensors persist in notarial, judicial, and laboratory settings requiring physical custody |
| Software | Cloud-native scoring engines distributed as SDKs inside banking, healthcare, and public-service applications |
Software leads this dimension and also grows fastest, because verification is increasingly consumed as an embedded function rather than a discrete station a customer walks to. Hardware demand does not disappear: courts and life-sciences laboratories still mandate certified capture with cryptographic timestamping, and those devices carry seven-to-ten-year amortisation schedules that delay replacement. As buyers retire pads at end-of-life rather than mid-cycle, spend migrates steadily from one-time device purchases to subscription software.
By Deployment Model
| Sub-Segment | Key Trend |
| On-premise | Retained for examiner access, latency control, and audit isolation in banking and life sciences |
| Cloud / SaaS | Elastic capacity and centralised model training, delivered through regional zones that satisfy residency rules |
On-premise remains the larger base while Cloud / SaaS grows fastest, and the crossover is being driven by workload shape rather than feature parity. Election boards and lenders generate short, intense processing peaks that make dedicated on-site capacity economically wasteful. Hybrid architectures — artefacts held locally, inference executed in a regional zone — have become the standard compromise for regulated buyers who cannot yet defend full migration to their supervisors.
By Authentication Mode
| Sub-Segment | Key Trend |
| Stand-alone signature | Embedded in legacy process design across lending, notarial, and records workflows |
| Multimodal (signature + doc image / ID / liveness) | Layered assurance adopted as generative forgery tooling defeats single-factor checks |
Stand-alone signature verification still carries the majority of revenue because existing procedures assume one handwritten authorisation per instrument. Multimodal grows fastest, since institutions facing synthetic handwriting can no longer defend a single factor to auditors. Adaptive scoring keeps the transition commercially viable: routine sessions clear on the signature alone, and only anomalous cases escalate to combined document, credential, and liveness checks, which limits friction on conversion-sensitive journeys.
By End-user Industry
| Sub-Segment | Key Trend |
| Financial Services | Cheque adjudication and account-opening controls underwritten by quantified loss avoidance |
| Healthcare | E-consent capture across surgical preparation and tele-medicine prescription reconciliation |
| Government and Elections | Statutory ballot adjudication deadlines and citizen-service portal automation |
| Logistics | On-device proof-of-delivery capture synced to back-end validation to cut chargebacks |
| Legal and Real Estate | Non-repudiation evidence for closings and instrument execution |
Financial Services holds the largest share because banks price verification accuracy directly against write-offs, making the business case durable through rate cycles. Government and Elections expands fastest, as jurisdictions must clear mail-ballot and benefits-claim volumes inside statutory windows that manual review cannot meet. Healthcare and Logistics buy on cycle-time and dispute reduction respectively, while Legal and Real Estate buyers select on evidentiary defensibility rather than throughput, which favours vendors with audit-grade logging.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA