Shale Gas Market (2026 - 2035)

ID: MRFR/EnP/10258-HCR 128 Pages Priya Nagrale Last Updated: September 16, 2026
Shale Gas Market Research Report By Well Type (Horizontal Wells, Vertical Wells, Directional Wells), By Technology (Hydraulic Fracturing, Horizontal Drilling, Refracturing), By Application (Power Generation, Industrial, Residential and Commercial, Transportation), By Distribution Channel (Pipeline, Liquefied Natural Gas (LNG), Compressed Natural Gas (CNG)) - Forecast to 2035
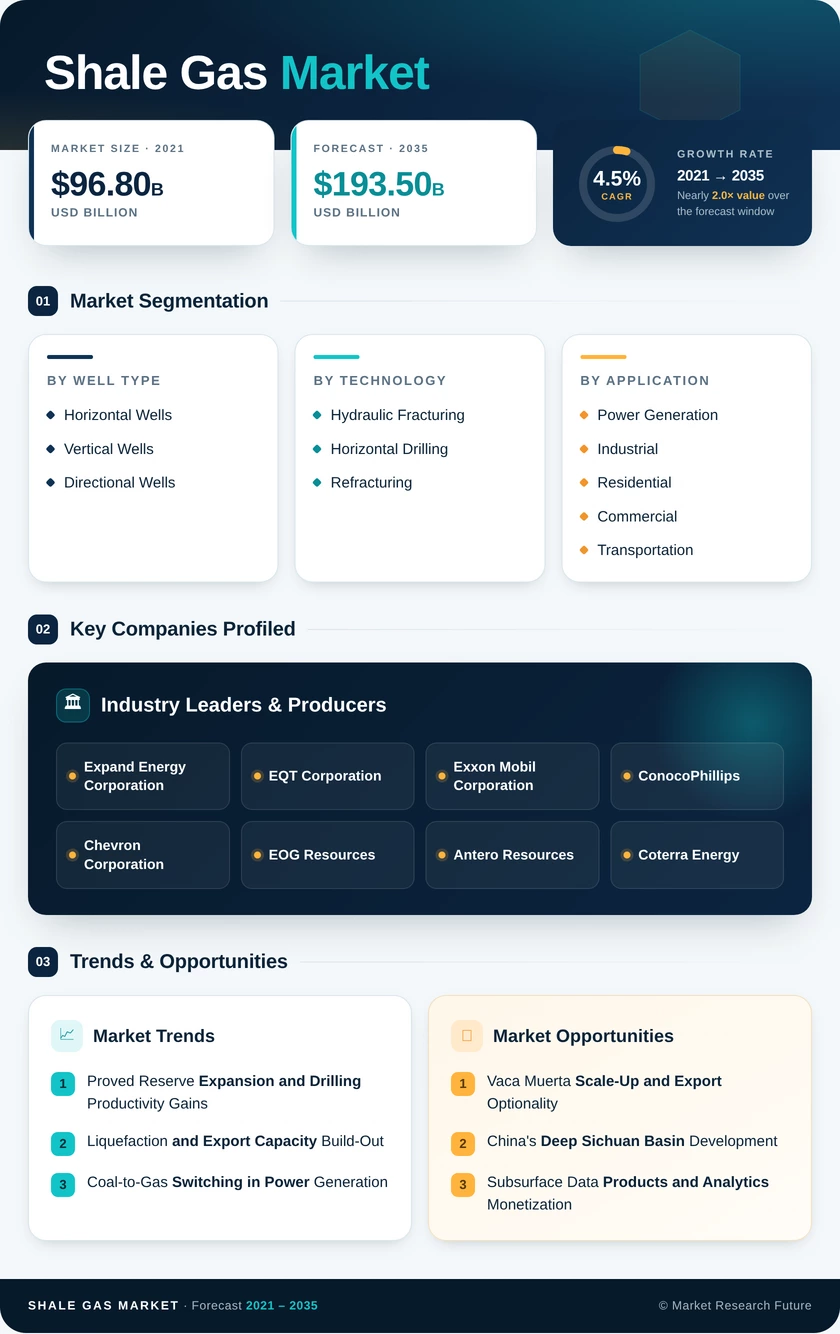
Shale Gas Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)4.5%
2025 Market SizeUSD 124.6 Billion
2035 Market SizeUSD 193.5 Billion
Key Players
Expand Energy Corporation
EQT Corporation
Exxon Mobil Corporation
ConocoPhillips
Chevron Corporation
EOG Resources
Opportunities
  • Vaca Muerta Scale-Up and Export Optionality
  • China's Deep Sichuan Basin Development
  • Subsurface Data Products and Analytics Monetization
  1. 1 Market Summary | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Well Type | |
    2. 2.2 By Technology | |
    3. 2.3 By Application | |
    4. 2.4 By Distribution Channel | |
    5. 2.5 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Current & Forecast Market Size (2026–2035) | |
    3. 3.3 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Proved Reserve Expansion and Drilling Productivity Gains | |
    2. 4.2 Liquefaction and Export Capacity Build-Out | |
    3. 4.3 Coal-to-Gas Switching in Power Generation | |
    4. 4.4 Multi-Well Pad Design and Completion Cost Deflation | |
    5. 4.5 Midstream Takeaway Capacity Additions | |
    6. 4.6 Petrochemical Feedstock Demand from NGL-Rich Plays | |
    7. 4.7 Electricity Load Growth from Data Centres and Electrification | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Commodity Price Volatility Below Breakeven | |
    2. 5.2 Methane Compliance and Monitoring Cost | |
    3. 5.3 Water Sourcing and Produced-Water Disposal Limits | |
    4. 5.4 Capital Discipline and Shareholder Return Mandates | |
    5. 5.5 Permitting Barriers and Social Licence Outside North America | |
  6. 6 Opportunities | |
    1. 6.1 Vaca Muerta Scale-Up and Export Optionality | |
    2. 6.2 China's Deep Sichuan Basin Development | |
    3. 6.3 Subsurface Data Products and Analytics Monetization | |
    4. 6.4 Produced-Water Treatment and Reuse Ventures | |
    5. 6.5 Certified Low-Carbon Gas and Differentiated Offtake | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 United States | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Rest of North America | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 France | | |
      3. 7.2.3 United Kingdom | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 NORDIC | | |
      7. 7.2.7 Turkey | | |
      8. 7.2.8 Russia | | |
      9. 7.2.9 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 Australia | | |
      5. 7.3.5 Malaysia | | |
      6. 7.3.6 Thailand | | |
      7. 7.3.7 Indonesia | | |
      8. 7.3.8 Vietnam | | |
      9. 7.3.9 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Chile | | |
      4. 7.4.4 Colombia | | |
      5. 7.4.5 Rest of South America | |
    5. 7.5 Middle East and Africa | | |
      1. 7.5.1 United Arab Emirates | | |
      2. 7.5.2 Saudi Arabia | | |
      3. 7.5.3 Qatar | | |
      4. 7.5.4 South Africa | | |
      5. 7.5.5 Nigeria | | |
      6. 7.5.6 Egypt | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Autonomous Drilling and Closed-Loop Completion Control | |
    2. 8.2 Contract Structure and the LNG Demand Pull | |
    3. 8.3 Measurement, Reporting and Verification as Commercial Infrastructure | |
    4. 8.4 Inventory Depletion and the Refracturing Response | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Well Type | | |
      1. 9.1.1 Horizontal Wells | | |
      2. 9.1.2 Vertical Wells | | |
      3. 9.1.3 Directional Wells | |
    2. 9.2 By Technology | | |
      1. 9.2.1 Hydraulic Fracturing | | |
      2. 9.2.2 Horizontal Drilling | | |
      3. 9.2.3 Refracturing | |
    3. 9.3 By Application | | |
      1. 9.3.1 Power Generation | | |
      2. 9.3.2 Industrial | | |
      3. 9.3.3 Residential and Commercial | | |
      4. 9.3.4 Transportation | |
    4. 9.4 By Distribution Channel | | |
      1. 9.4.1 Pipeline | | |
      2. 9.4.2 Liquefied Natural Gas (LNG) | | |
      3. 9.4.3 Compressed Natural Gas (CNG) | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 Expand Energy Corporation | | |
      2. 10.3.2 EQT Corporation | | |
      3. 10.3.3 Exxon Mobil Corporation | | |
      4. 10.3.4 ConocoPhillips | | |
      5. 10.3.5 Chevron Corporation | | |
      6. 10.3.6 EOG Resources | | |
      7. 10.3.7 Antero Resources | | |
      8. 10.3.8 Coterra Energy | | |
      9. 10.3.9 Devon Energy | | |
      10. 10.3.10 Range Resources | | |
      11. 10.3.11 PetroChina Company Limited | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
    1. 12.1 Study Period & Base Year | |
    2. 12.2 Data Sources & Citations | |
    3. 12.3 Abbreviations | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions | | LIST OF TABLES | |
  15. TABLE 1 Global Shale Gas Market Size & Forecast (USD Billion), 2021–2035 | |
  16. TABLE 2 Global Shale Gas Market – Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis – Global Shale Gas Market, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis – Global Shale Gas Market, 2026–2035 | |
  19. TABLE 5 Global Shale Gas Market Size, by Region, 2021–2035 (USD Billion) | |
  20. TABLE 6 North America Shale Gas Market Size, by Country, 2021–2035 (USD Billion) | |
  21. TABLE 7 Europe Shale Gas Market Size, by Country, 2021–2035 (USD Billion) | |
  22. TABLE 8 Asia-Pacific Shale Gas Market Size, by Country, 2021–2035 (USD Billion) | |
  23. TABLE 9 South America Shale Gas Market Size, by Country, 2021–2035 (USD Billion) | |
  24. TABLE 10 Middle East and Africa Shale Gas Market Size, by Country, 2021–2035 (USD Billion) | |
  25. TABLE 11 Global Shale Gas Market Size, by Well Type, 2021–2035 (USD Billion) | |
  26. TABLE 12 Global Shale Gas Market Size, by Technology, 2021–2035 (USD Billion) | |
  27. TABLE 13 Global Shale Gas Market Size, by Application, 2021–2035 (USD Billion) | |
  28. TABLE 14 Global Shale Gas Market Size, by Distribution Channel, 2021–2035 (USD Billion) | |
  29. TABLE 15 Competitive Benchmarking Matrix – Global Shale Gas Market, 2026 | |
  30. TABLE 16 Company Profiles – Key Players, Global Shale Gas Market | |
  31. TABLE 17 Recent Developments & Strategic Announcements, 2023–2025 | |
  32. TABLE 18 Report Scope & Methodology Summary | |
  33. TABLE 19 Detailed Sources and Citations Index | |
  34. TABLE 20 North America Shale Gas Market Size, by Well Type, 2021–2035 (USD Billion) | |
  35. TABLE 21 North America Shale Gas Market Size, by Application, 2021–2035 (USD Billion) | |
  36. TABLE 22 Asia-Pacific Shale Gas Market Size, by Technology, 2021–2035 (USD Billion) | |
  37. TABLE 23 South America Shale Gas Market Size, by Distribution Channel, 2021–2035 (USD Billion) | |
  38. TABLE 24 Europe Shale Gas Market Size, by Application, 2021–2035 (USD Billion) | | LIST OF FIGURES | |
  39. FIGURE 1 Global Shale Gas Market Dynamics – Drivers, Restraints and Opportunities | |
  40. FIGURE 2 Industry Value Chain Analysis – Wellhead to End Use | |
  41. FIGURE 3 Porter's Five Forces Analysis – Global Shale Gas Market | |
  42. FIGURE 4 Global Shale Gas Market Size Trend, 2021–2035 (USD Billion) | |
  43. FIGURE 5 Year-over-Year Growth Trend, 2022–2035 (%) | |
  44. FIGURE 6 Market Share by Well Type, 2026 vs 2035 (%) | |
  45. FIGURE 7 Market Share by Technology, 2026 vs 2035 (%) | |
  46. FIGURE 8 Market Share by Application, 2026 vs 2035 (%) | |
  47. FIGURE 9 Market Share by Distribution Channel, 2026 vs 2035 (%) | |
  48. FIGURE 10 Regional Market Share Distribution, 2026 (%) | |
  49. FIGURE 11 Regional Market Share Distribution, 2035 (%) | |
  50. FIGURE 12 Country-Level Growth Comparison – Selected Markets, 2026–2035 (CAGR %) | |
  51. FIGURE 13 Competitive Landscape – Estimated Revenue Share Ranges, 2026 | |
  52. FIGURE 14 Strategic Positioning Matrix – Key Players | |
  53. FIGURE 15 Driver Impact Contribution to Forecast CAGR (pp)

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Well TypeHorizontal Wells; Vertical Wells; Directional WellsHorizontal Wells (82.4% share)Directional Wells (5.1% CAGR)
By TechnologyHydraulic Fracturing; Horizontal Drilling; RefracturingHydraulic Fracturing (61.3% share)Horizontal Drilling (5.3% CAGR)
By ApplicationPower Generation; Industrial; Residential and Commercial; TransportationPower Generation (38.6% share)Transportation (6.2% CAGR)
By Distribution ChannelPipeline; Liquefied Natural Gas (LNG); Compressed Natural Gas (CNG)Pipeline (71.8% share)Liquefied Natural Gas (LNG) (6.8% CAGR)


Market Segmentation Overview

By Well Type

Sub-SegmentKey Trend
Horizontal WellsLaterals routinely exceed 3,000 metres with 60–90 completion stages
Vertical WellsRetained for shallow naturally fractured intervals and legacy production
Directional WellsDeviated trajectories serve acreage where surface placement is restricted


Horizontal Wells lead this dimension because reservoir contact, not resource presence, sets recovery in low-permeability shale — a single extended lateral replaces the output of dozens of vertical penetrations. Directional Wells grow fastest, driven by Chinese Sichuan operators and European tight-gas programmes where mountainous terrain, protected land or dense population prevents drilling directly above the target interval. Vertical Wells continue to decline as a share of new activity, surviving mainly on legacy production and shallow redevelopment where the lateral cost premium cannot be recovered.

By Technology

Sub-SegmentKey Trend
Hydraulic FracturingProppant intensity and stage counts continue to rise per lateral metre
Horizontal DrillingAutomated directional systems cut drilling days by 15–20% per well
RefracturingWide-spacing legacy wellbores targeted for economic recovery uplift


Hydraulic Fracturing dominates technology-attributable spend because completion now consumes roughly 60% of total well cost, and stage density has escalated faster than any other engineering variable. Horizontal Drilling grows fastest as operators extend laterals to amortize pad infrastructure across more reservoir, with automation reducing the time penalty that once limited lateral length. Refracturing is the smallest of the three but offers the highest return per dollar, targeting Barnett and early Haynesville wellbores completed before modern cluster spacing became standard practice.

By Application

Sub-SegmentKey Trend
Power GenerationCoal retirement schedules and firm capacity requirements sustain baseload demand
IndustrialAmmonia, methanol and ethylene producers site plants for feedstock proximity
Residential and CommercialHeating load growth limited by efficiency standards and electrification policy
TransportationMarine bunkering expands under IMO sulphur and carbon intensity rules


Power Generation is the largest application because utility procurement runs on long horizons and gas remains the most permittable firm capacity in most North American and Asian markets. Transportation grows fastest, driven by shipowners converting to LNG bunkering, though its absolute contribution stays modest against Industrial demand, which is the stickiest segment in the mix — crackers and ammonia plants represent multi-decade assets that cannot relocate away from their feedstock. Residential and Commercial expands slowest, constrained by building efficiency codes and electrification mandates in mature heating markets.

By Distribution Channel

Sub-SegmentKey Trend
PipelineBasis differentials tighten as trunkline and compression capacity commissions
Liquefied Natural Gas (LNG)Export train commissioning shifts producer pricing toward international benchmarks
Compressed Natural Gas (CNG)Fleet fuelling and remote power applications sustain a specialized niche


Pipeline carries the overwhelming majority of shale volumes and will continue to, since domestic and cross-border trunkline delivery is the lowest-cost route wherever capacity exists. Liquefied Natural Gas (LNG) grows fastest as Gulf Coast, Canadian, and eventually Argentine liquefaction converts stranded basin supply into internationally priced cargoes, changing which basins command premium netbacks. Compressed Natural Gas (CNG) remains a specialized channel serving heavy-duty fleets and off-grid power, viable only where liquefaction economics do not justify the capital.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.