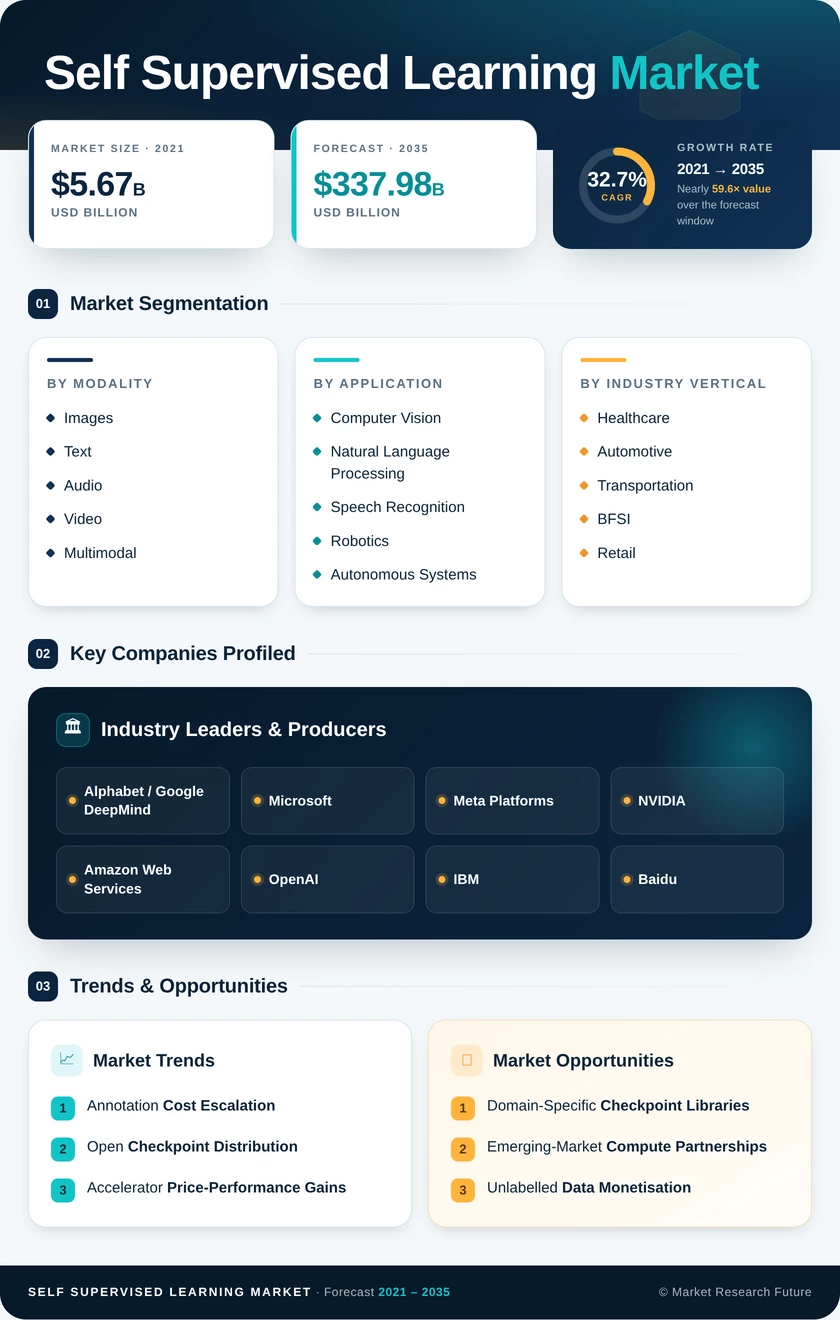
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Modality | Images; Text; Audio; Video; Multimodal | Images (32.15% share) | Multimodal (32.26% CAGR) |
| By Application | Computer Vision; Natural Language Processing; Speech Recognition; Robotics and Autonomous Systems; Recommendation Systems | Natural Language Processing (37.05% share) | Robotics and Autonomous Systems (32.06% CAGR) |
| By Industry Vertical | Healthcare; Automotive and Transportation; BFSI; Retail and E-commerce; Manufacturing; IT and Telecommunications; Others | Healthcare (USD 3.68 Billion) | Automotive and Transportation (32.09% CAGR) |
| By Deployment Mode | Cloud; On-Premises; Edge | Cloud (60.00% share) | Edge (34.25% CAGR) |
| By Component | Frameworks and Libraries; Pre-Trained Models; Services and Integration; Hardware Accelerators | Pre-Trained Models (40.47% share) | Frameworks and Libraries (32.34% CAGR) |
Market Segmentation Overview
By Modality
| Sub-Segment | Key Trend |
| Images | Contrastive pre-training now standard in inspection and clinical screening workflows |
| Text | Retrieval-oriented encoders embedded across enterprise document systems |
| Audio | Unlabelled broadcast archives extending coverage to low-resource languages |
| Video | Temporal pretext tasks maturing for summarisation and moderation |
| Multimodal | Shared embedding spaces replacing separate per-modality encoders |
Images remain the largest modality because manufacturers and hospitals already held large image archives before pre-training became viable, and augmentation-based objectives work reliably on that data. Multimodal expands fastest as buyers consolidate search, captioning, and moderation onto a single backbone, cutting the number of pipelines they must version and monitor. Text sits between the two, growing steadily on retrieval workloads. Video and audio remain smaller but are becoming cheaper as storage and temporal-objective research improve.
By Application
| Sub-Segment | Key Trend |
| Computer Vision | Defect detection and driver assistance moving to pre-trained backbones |
| Natural Language Processing | Retrieval and summarisation embedded in mainstream enterprise software |
| Speech Recognition | Unlabelled archives unlocking previously uncommercial languages |
| Robotics and Autonomous Systems | Interaction logs displacing manually scripted control policies |
| Recommendation Systems | Clickstream objectives raising cross-sell performance without explicit labels |
Natural Language Processing leads on sheer corpus availability, and the near-universal enterprise need for document retrieval. Robotics and Autonomous Systems is the fastest-growing application because deployed fleets generate training data continuously, so each installation compounds the operator's advantage. Computer Vision remains a large and stable second, anchored by regulated inspection and clinical use cases where accuracy requirements justify the fine-tuning effort. Speech Recognition growth is regulatory- and coverage-driven rather than compute-driven.
By Industry Vertical
| Sub-Segment | Key Trend |
| Healthcare | Expert annotation cost driving label-efficient screening adoption |
| Automotive and Transportation | Fleet-scale footage archives feeding perception adaptation |
| BFSI | Transaction embeddings replacing rule-based fraud thresholds |
| Retail and E-commerce | Catalogue enrichment and behavioural recommendation |
| Manufacturing | Vibration and thermal signatures supporting failure prediction |
| IT and Telecommunications | Log and network telemetry anomaly detection at scale |
| Others | Energy, agriculture, and public-sector sensor applications |
Healthcare holds the largest vertical position because radiologist annotation is among the most expensive labelling in any industry, so label efficiency delivers immediate payback. Automotive and Transportation grows fastest: dash-cam and lidar archives accumulate as an operational by-product, giving OEMs a training corpus they do not have to buy. IT and Telecommunications adoption is broad but lower-margin, while Manufacturing conversion lags on legacy data infrastructure rather than on model availability.
By Deployment Mode
| Sub-Segment | Key Trend |
| Cloud | Elastic accelerator capacity for burst pre-training workloads |
| On-Premises | Residency and control requirements in regulated environments |
| Edge | Transformer-optimised silicon enabling on-device inference |
Cloud dominates deployment because pre-training requires burst accelerator capacity that very few buyers can justify owning outright. Edge grows fastest as data-residency rules and latency budgets push inference toward the point of capture, and as consumer and industrial silicon gains transformer-optimised units. On-Premises holds a durable base among banks, hospitals, and defence buyers whose corpora cannot leave controlled environments. The settled pattern is hybrid: centralised pre-training, distributed serving.
By Component
| Sub-Segment | Key Trend |
| Frameworks and Libraries | Scaffolding for bespoke pretext task and objective design |
| Pre-Trained Models | Ready checkpoints compressing time to first production result |
| Services and Integration | Domain adaptation, MLOps engineering, evaluation harnesses |
| Hardware Accelerators | Throughput and power efficiency setting the training cost floor |
Pre-Trained Models capture the largest component share because buying a checkpoint moves budget from unpredictable pre-training toward fine-tuning, where outcomes are easier to forecast. Frameworks and Libraries grow fastest as teams in life sciences and energy outgrow generic checkpoints and build domain-specific objectives themselves. Services and Integration remain a substantial line because pipeline and evaluation engineering is consistently under-scoped. Hardware Accelerators set the economics beneath all three.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA