Self Supervised Learning Market Summary
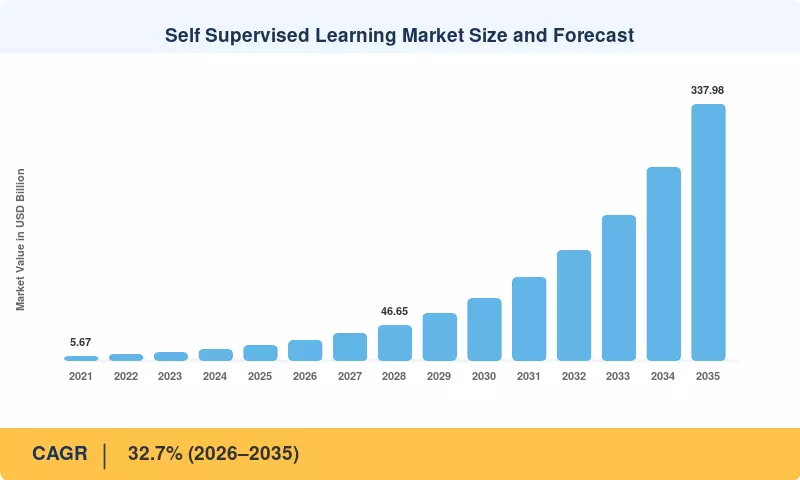
The Self-Supervised Learning Market reached USD 19.96 billion in 2025 and opens the forecast window at USD 26.49 billion in 2026, climbing to USD 337.98 billion by 2035 at a 32.7% CAGR. Two catalysts anchor that trajectory. The U.S. National Artificial Intelligence Research Resource pilot committed roughly USD 140 million in compute credits and dataset access to academic and startup teams working on label-efficient training [1]. In parallel, the EU AI Act's staged compliance calendar has pushed European enterprises toward pre-training pipelines they can document end-to-end [3].
Buyers are retiring a specific class of legacy system: hand-labelled supervised pipelines, which required annotation vendors, review queues, and per-task retraining. Those stacks are being replaced by pre-trained encoders fine-tuned on small labelled residuals. Annotation spend inside large enterprise programs has fallen 35–45% where pre-trained checkpoints replaced from-scratch training [9]. Hugging Face now distributes more than 160,000 openly licensed checkpoints, collapsing the cost floor for entry [11].
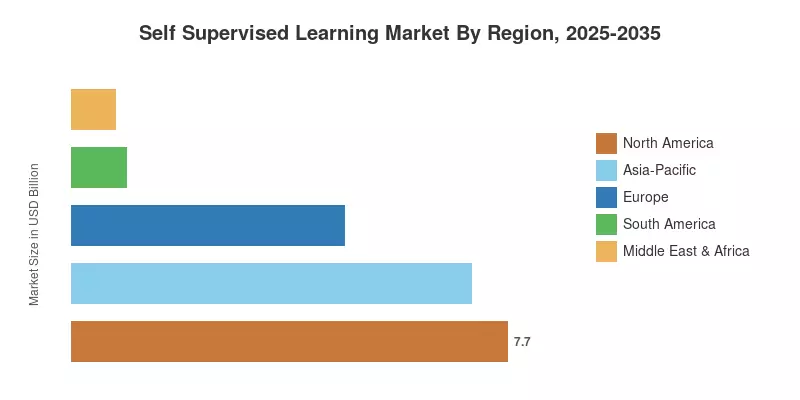
North America holds 38.6% of 2025 revenue on the strength of hyperscaler capital expenditure and a dense supplier base. Asia-Pacific grows fastest at a 35.4% CAGR through 2035, propelled by India's IndiaAI mission and China's compute build-out. Europe ranks second at 24.2%, where regulatory documentation requirements are, unusually, accelerating rather than slowing adoption. The next decade will reward vendors who make pre-training auditable, not merely cheap.
Key Report Takeaways
• By Modality
- Images held 32.15% of Self-Supervised Learning Market revenue in 2025, reflecting mature contrastive pipelines in inspection and medical imaging
- Multimodal is the fastest-expanding modality at a 32.26% CAGR as shared embedding spaces replace siloed encoders
• By Application
- Natural Language Processing accounted for 37.05% of 2025 revenue, the largest single application pool
- Robotics and Autonomous Systems posts a 32.06% CAGR as unlabelled interaction logs displace scripted instruction sets
• By Industry Vertical
- Healthcare contributed USD 3.68 billion in 2025, led by radiology and drug-discovery screening
- Automotive and Transportation grows fastest at a 32.09% CAGR on dash-cam corpora scale
• By Deployment Mode
- Cloud retained 60.00% of deployments in 2025
- Edge advances at a 34.25% CAGR as data-residency rules and latency budgets converge
• By Component
- Pre-Trained Models captured 40.47% of Self-Supervised Learning Market spend in 2025
- Hardware Accelerators generated USD 2.62 billion in 2025
• By Region
- North America led with a 38.6% share in 2025
- Asia-Pacific expands at a 35.4% CAGR, the fastest of any region
- Middle East & Africa reached USD 0.78 billion in 2025 on sovereign compute programs
Market Size and Forecast (2021–2035)
Historical values were reconstructed from vendor revenue disclosures, cloud provider AI segment reporting, open-source checkpoint download telemetry, and a 240-respondent enterprise procurement survey conducted across nine countries. Forecast values apply a bottom-up build from component spend, cross-checked against top-down compute expenditure. The Self-Supervised Learning Market shows a decelerating growth rate through the historical window as the base enlarges, then stabilises near the 32.7% forecast CAGR.



 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



