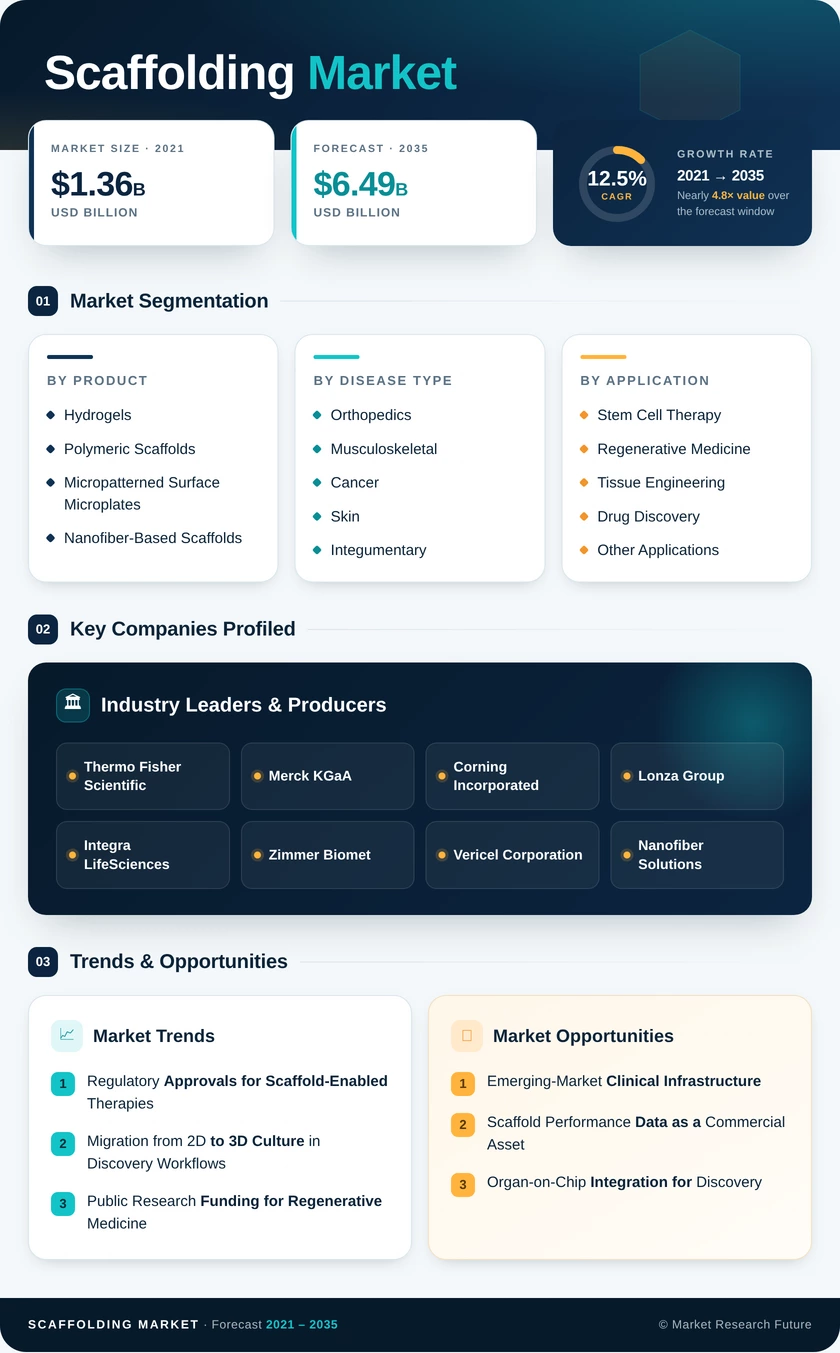
Scaffolding Market (2026 - 2035)

ID: MRFR/PCM/3470-CR 206 Pages Chitranshi Jaiswal Last Updated: September 18, 2026
Scaffolding Market Research Report Information By Product (Hydrogels, Polymeric Scaffolds, Micropatterned Surface Microplates, and Nanofiber-Based Scaffolds), By Disease Type (Orthopedics, Musculoskeletal, Cancer, Skin and Integumentary, Dental, Cardiology and Vascular, Neurology, and Other Disease Types), By Application (Stem Cell Therapy, Regenerative Medicine and Tissue Engineering, Drug Discovery, and Other Applications), and By End User (Biotechnology and Pharmaceutical Organizations, Research Laboratories and Institutes, Hospitals and Diagnostic Centers, and Other End Users) – Forecast Till 2035.
Scaffolding Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)12.5%
2025 Market SizeUSD 2.01 Billion
2035 Market SizeUSD 6.49 Billion
Key Players
Thermo Fisher Scientific
Merck KGaA
Corning Incorporated
Lonza Group
Integra LifeSciences
Zimmer Biomet
Opportunities
  • Emerging-Market Clinical Infrastructure
  • Scaffold Performance Data as a Commercial Asset
  • Organ-on-Chip Integration for Discovery
  1. 1 Market Summary | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Product | |
    2. 2.2 By Disease Type | |
    3. 2.3 By Application | |
    4. 2.4 By End User | |
    5. 2.5 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2024) | |
    2. 3.2 Base Year Estimate (2025) | |
    3. 3.3 Forecast Market Size (2026–2035) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Regulatory Approvals for Scaffold-Enabled Therapies | |
    2. 4.2 Migration from 2D to 3D Culture in Discovery Workflows | |
    3. 4.3 Public Research Funding for Regenerative Medicine | |
    4. 4.4 Ageing Populations and Musculoskeletal Disease Burden | |
    5. 4.5 Bioprinting and Melt Electrowriting Process Maturity | |
    6. 4.6 Hospital-Based Cell Therapy Infrastructure Build-Out | |
    7. 4.7 Asia-Pacific Biomaterial Manufacturing Localisation | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 GMP-Grade Biomaterial Cost Structure | |
    2. 5.2 Regulatory Heterogeneity Across Jurisdictions | |
    3. 5.3 Batch Reproducibility and Scale-Up Limits | |
    4. 5.4 Reimbursement Uncertainty for Scaffold-Based Procedures | |
    5. 5.5 Shortage of Trained Bioprocess Personnel | |
  6. 6 Opportunities | |
    1. 6.1 Emerging-Market Clinical Infrastructure | |
    2. 6.2 Scaffold Performance Data as a Commercial Asset | |
    3. 6.3 Organ-on-Chip Integration for Discovery | |
    4. 6.4 Xeno-Free and Animal-Free Supply Chains | |
    5. 6.5 Point-of-Care Manufacturing Partnerships | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 Middle East and Africa | | |
      1. 7.4.1 Saudi Arabia | | |
      2. 7.4.2 UAE | | |
      3. 7.4.3 South Africa | | |
      4. 7.4.4 Egypt | | |
      5. 7.4.5 Rest of MEA | |
    5. 7.5 South America | | |
      1. 7.5.1 Brazil | | |
      2. 7.5.2 Argentina | | |
      3. 7.5.3 Rest of South America | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Computational Design and Automated Fabrication | |
    2. 8.2 Consolidation Around Integrated Platform Suppliers | |
    3. 8.3 Decentralised and Point-of-Care Production | |
    4. 8.4 Sustainability and Animal-Free Sourcing | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Product | | |
      1. 9.1.1 Hydrogels | | |
      2. 9.1.2 Polymeric Scaffolds | | |
      3. 9.1.3 Micropatterned Surface Microplates | | |
      4. 9.1.4 Nanofiber-Based Scaffolds | |
    2. 9.2 By Disease Type | | |
      1. 9.2.1 Orthopedics | | |
      2. 9.2.2 Musculoskeletal | | |
      3. 9.2.3 Cancer | | |
      4. 9.2.4 Skin and Integumentary | | |
      5. 9.2.5 Dental | | |
      6. 9.2.6 Cardiology and Vascular | | |
      7. 9.2.7 Neurology | | |
      8. 9.2.8 Other Disease Types | |
    3. 9.3 By Application | | |
      1. 9.3.1 Stem Cell Therapy | | |
      2. 9.3.2 Regenerative Medicine and Tissue Engineering | | |
      3. 9.3.3 Drug Discovery | | |
      4. 9.3.4 Other Applications | |
    4. 9.4 By End User | | |
      1. 9.4.1 Biotechnology and Pharmaceutical Organizations | | |
      2. 9.4.2 Research Laboratories and Institutes | | |
      3. 9.4.3 Hospitals and Diagnostic Centers | | |
      4. 9.4.4 Other End Users | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions | | LIST OF TABLES | |
  15. TABLE 1 Global Scaffolding Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Global Scaffolding Market — Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Global Scaffolding Market — Driver Impact Analysis, 2026–2035 | |
  18. TABLE 4 Global Scaffolding Market — Restraint Impact Analysis, 2026–2035 | |
  19. TABLE 5 Global Scaffolding Market Size, by Region, 2021–2035 (USD Billion) | |
  20. TABLE 6 North America Scaffolding Market Size, by Country, 2021–2035 (USD Billion) | |
  21. TABLE 7 Europe Scaffolding Market Size, by Country, 2021–2035 (USD Billion) | |
  22. TABLE 8 Asia-Pacific Scaffolding Market Size, by Country, 2021–2035 (USD Billion) | |
  23. TABLE 9 Middle East and Africa Scaffolding Market Size, by Country, 2021–2035 (USD Billion) | |
  24. TABLE 10 South America Scaffolding Market Size, by Country, 2021–2035 (USD Billion) | |
  25. TABLE 11 Global Scaffolding Market Size, by Product, 2021–2035 (USD Billion) | |
  26. TABLE 12 Global Scaffolding Market Size, by Disease Type, 2021–2035 (USD Billion) | |
  27. TABLE 13 Global Scaffolding Market Size, by Application, 2021–2035 (USD Billion) | |
  28. TABLE 14 Global Scaffolding Market Size, by End User, 2021–2035 (USD Billion) | |
  29. TABLE 15 Competitive Benchmarking Matrix — Global Scaffolding Market, 2026 | |
  30. TABLE 16 Company Profiles — Key Players, Global Scaffolding Market | |
  31. TABLE 17 Recent Developments & Strategic Announcements, 2023–2025 | |
  32. TABLE 18 Report Scope & Methodology Summary | |
  33. TABLE 19 Detailed Sources and Citations | | LIST OF FIGURES | |
  34. FIGURE 1 Global Scaffolding Market — Market Dynamics Overview | |
  35. FIGURE 2 Global Scaffolding Market — Industry Value Chain Analysis | |
  36. FIGURE 3 Global Scaffolding Market — Porter's Five Forces Analysis | |
  37. FIGURE 4 Global Scaffolding Market Size Trend, 2021–2035 (USD Billion) | |
  38. FIGURE 5 Market Share by Product, 2025 (%) | |
  39. FIGURE 6 Market Share by Disease Type, 2025 (%) | |
  40. FIGURE 7 Market Share by Application, 2025 (%) | |
  41. FIGURE 8 Market Share by End User, 2025 (%) | |
  42. FIGURE 9 Regional Market Share, 2025 (%) | |
  43. FIGURE 10 Regional CAGR Comparison, 2026–2035 (%) | |
  44. FIGURE 11 Competitive Landscape — Estimated Revenue Share Ranges, 2026 | |
  45. FIGURE 12 Fastest Growing Segments by CAGR, 2026–2035

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By ProductHydrogels; Polymeric Scaffolds; Micropatterned Surface Microplates; Nanofiber-Based ScaffoldsHydrogels (33.3% share, 2025)Nanofiber-Based Scaffolds (16.3% CAGR)
By Disease TypeOrthopedics; Musculoskeletal; Cancer; Skin and Integumentary; Dental; Cardiology and Vascular; Neurology; Other Disease TypesOrthopedics (25.1% share, 2025)Neurology (14.6% CAGR)
By ApplicationStem Cell Therapy; Regenerative Medicine and Tissue Engineering; Drug Discovery; Other ApplicationsRegenerative Medicine and Tissue Engineering (38.4% share, 2025)Stem Cell Therapy (15.6% CAGR)
By End UserBiotechnology and Pharmaceutical Organizations; Research Laboratories and Institutes; Hospitals and Diagnostic Centers; Other End UsersBiotechnology and Pharmaceutical Organizations (49.2% share, 2025)Hospitals and Diagnostic Centers (15.3% CAGR)


Market Segmentation Overview

By Product

Sub-SegmentKey Trend
HydrogelsTunable crosslinking chemistries expand the stiffness range addressable by a single platform.
Polymeric ScaffoldsDegradation profiles matched to tissue remodelling schedules in load-bearing repair.
Micropatterned Surface MicroplatesStandardised formats aligned to automated high-throughput screening lines
Nanofiber-Based ScaffoldsMelt electrowriting delivers sub-micron architectural control at commercial throughput.


Hydrogels lead this dimension on 33.3% share because buyers can adjust mechanical properties without retraining laboratory staff or replacing handling protocols. Nanofiber-based scaffolds grow fastest at 16.3% CAGR as fabrication control improves enough to reproduce extracellular matrix geometry at clinically relevant volumes, which matters most in bone and nerve repair. Polymeric scaffolds hold their position where degradation timing must be engineered rather than tuned, and micropatterned surface microplates remain tied to screening automation rather than therapeutic use.

By Disease Type

Sub-SegmentKey Trend
OrthopedicsBone-void filler protocols with established surgeon familiarity and coding precedent
MusculoskeletalMultiphasic constructs targeting tendon and ligament attachment sites
CancerMatrix-based tumour microenvironment models improving screening predictivity.
Skin and IntegumentaryBurn and chronic wound reconstruction driving resorbable membrane demand.
DentalGuided bone regeneration membranes in implant site preparation
Cardiology and VascularResorbable vascular patches and graft scaffolds entering clinical use.
NeurologyConductive nerve conduits combining structural guidance with growth-factor release
Other Disease TypesOphthalmic and urologic reconstruction niches with small but stable volume


Orthopedics dominates at 25.1% share, a position built on surgeon familiarity and reimbursement precedent rather than technical superiority. Neurology grows fastest at 14.6% CAGR because custom-printed nerve conduits address peripheral injuries where autograft supply is structurally limited, and conductive polymer integration has moved from laboratory demonstration to catalogue product. Cancer applications expand through research spending rather than therapy revenue, while dental and skin indications track procedure volume in largely private-pay settings.

By Application

Sub-SegmentKey Trend
Stem Cell TherapyXeno-free media raising derivation efficiency and expanding usable cell yields.
Regenerative Medicine and Tissue EngineeringClinical translation of engineered constructs into routine surgical practice
Drug DiscoveryOrgan-on-chip adoption creating demand for tissue-specific matrix formulations.
Other ApplicationsDiagnostics, cosmetics testing, and veterinary reconstruction use cases


Regenerative medicine and tissue engineering holds a 38.4% share because it captures the constructs already validated in clinical practice, giving it the largest installed procedure base. Stem cell therapy grows fastest at 15.6% CAGR as coated electrospun meshes improve mesenchymal cell viability and paracrine secretion, pushing cartilage and cardiac programmes toward pivotal trials. Drug discovery behaves differently from both: its demand tracks pharmaceutical research headcount and screening throughput, which makes it the steadiest consumable stream in the dimension.

By End User

Sub-SegmentKey Trend
Biotechnology and Pharmaceutical OrganizationsSimultaneous purchasing across discovery, development, and pilot manufacturing
Research Laboratories and InstitutesGrant-funded protocol development that shapes downstream commercial standards
Hospitals and Diagnostic CentersGMP suites and robotic handling enabling on-site preparation at moderate volume
Other End UsersContract manufacturers, veterinary clinics, and cosmetics testing laboratories


Biotechnology and pharmaceutical organizations account for 49.2% of demand because they purchase across every stage at once, from screening consumables to pilot-scale clinical material. Hospitals and diagnostic centers grow fastest at 15.3% CAGR as reimbursement clarity and automated closed systems make on-site preparation economically viable without full centralised manufacturing. Research laboratories and institutes buy in smaller quantities but exert outsized influence, since the protocols they publish become the qualification baseline commercial buyers later specify in supply contracts.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.