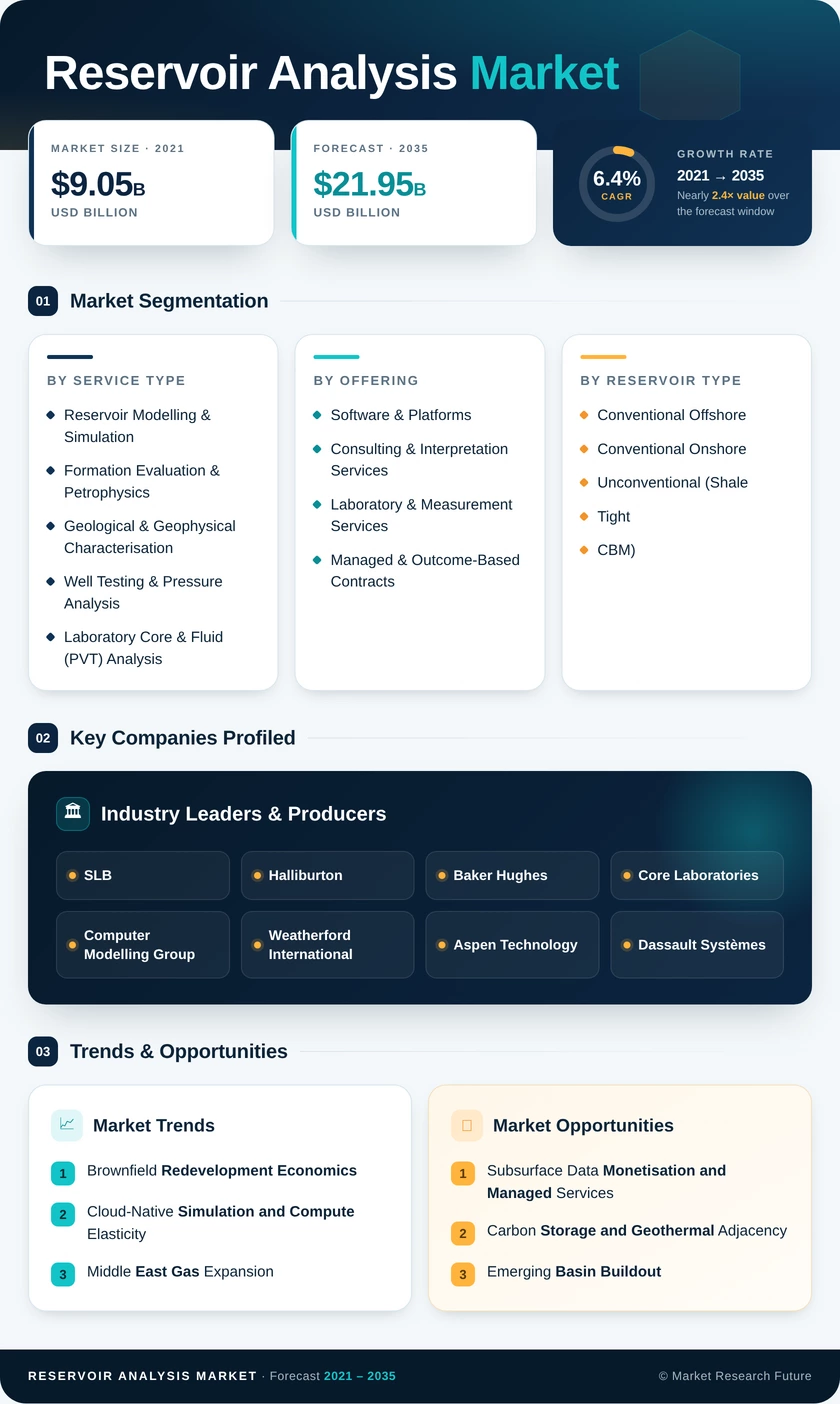
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Service Type | Reservoir Modelling & Simulation; Formation Evaluation & Petrophysics; Geological & Geophysical Characterisation; Well Testing & Pressure Analysis; Laboratory Core & Fluid (PVT) Analysis; Reservoir Monitoring & Surveillance | Reservoir Modelling & Simulation | Reservoir Monitoring & Surveillance |
| By Offering | Software & Platforms; Consulting & Interpretation Services; Laboratory & Measurement Services; Managed & Outcome-Based Contracts | Consulting & Interpretation Services | Managed & Outcome-Based Contracts |
| By Reservoir Type | Conventional Offshore; Conventional Onshore; Unconventional (Shale, Tight, CBM); Carbon Storage & Geothermal | Conventional Offshore | Carbon Storage & Geothermal |
| By End User | National Oil Companies; International Oil Companies; Independent E&P Operators; Oilfield Service Providers | National Oil Companies | Independent E&P Operators |
| By Region | North America; Europe; Asia-Pacific; Middle East & Africa; South America | North America | Middle East & Africa |
Market Segmentation Overview
By Service Type
| Sub-Segment | Key Trend |
| Reservoir Modelling & Simulation | GPU acceleration and ensemble-based uncertainty workflows replace deterministic single-case studies |
| Formation Evaluation & Petrophysics | Machine-learning log prediction fills gaps in sparsely cored intervals |
| Geological & Geophysical Characterisation | Seismic reprocessing of legacy volumes delivers cheaper resolution than new acquisition |
| Well Testing & Pressure Analysis | Permanent gauges shift interpretation from discrete tests to continuous deconvolution |
| Laboratory Core & Fluid (PVT) Analysis | Digital rock physics supplements, but does not replace, physical measurement |
| Reservoir Monitoring & Surveillance | Fibre-optic sensing and 4D seismic feed recurring interpretation contracts |
Service-type demand is bifurcating. High-fidelity simulation and laboratory measurement remain project-shaped and expert-dependent, while surveillance and evaluation increasingly settle into subscription rhythms tied to production operations rather than capital sanction dates.
By Offering
| Sub-Segment | Key Trend |
| Software & Platforms | Perpetual licences give way to committed-consumption cloud agreements |
| Consulting & Interpretation Services | Specialist boutiques win where majors lack basin-specific depth |
| Laboratory & Measurement Services | Regional laboratory capacity expands near Middle East and Guyana activity centres |
| Managed & Outcome-Based Contracts | Multi-year subsurface function outsourcing addresses operator staffing gaps |
Buying behaviour is drifting toward recurring commercial structures. Operators want predictable annual costs and guaranteed access to scarce expertise, and vendors want revenue visibility — an alignment that favours managed contracts over one-off study procurement.
By Reservoir Type
| Sub-Segment | Key Trend |
| Conventional Offshore | Deepwater project economics justify the deepest characterisation budgets per well |
| Conventional Onshore | Mature waterflood and enhanced recovery screening dominates study demand |
| Unconventional (Shale, Tight, CBM) | Spacing optimisation and refrac candidate ranking drive repeat analytical cycles |
| Carbon Storage & Geothermal | Containment modelling and multi-decade monitoring plans create new deliverable formats |
Reservoir type largely determines study intensity. A single deepwater development can absorb more analytical spend than an entire onshore field programme, while unconventional plays generate volume through repetition rather than depth.
By End User
| Sub-Segment | Key Trend |
| National Oil Companies | In-house subsurface centres of excellence backed by long-tenor vendor partnerships |
| International Oil Companies | Portfolio-wide toolchain standardisation to cut integration overhead |
| Independent E&P Operators | Cloud pricing opens advanced tooling to teams without dedicated simulation groups |
| Oilfield Service Providers | Bundled characterisation inside integrated project management contracts |
End-user behaviour splits along capability lines. Organisations with deep internal benches buy tools and data; those without buy answers — and the second group is growing faster, which reshapes how vendors package and price what they sell.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA