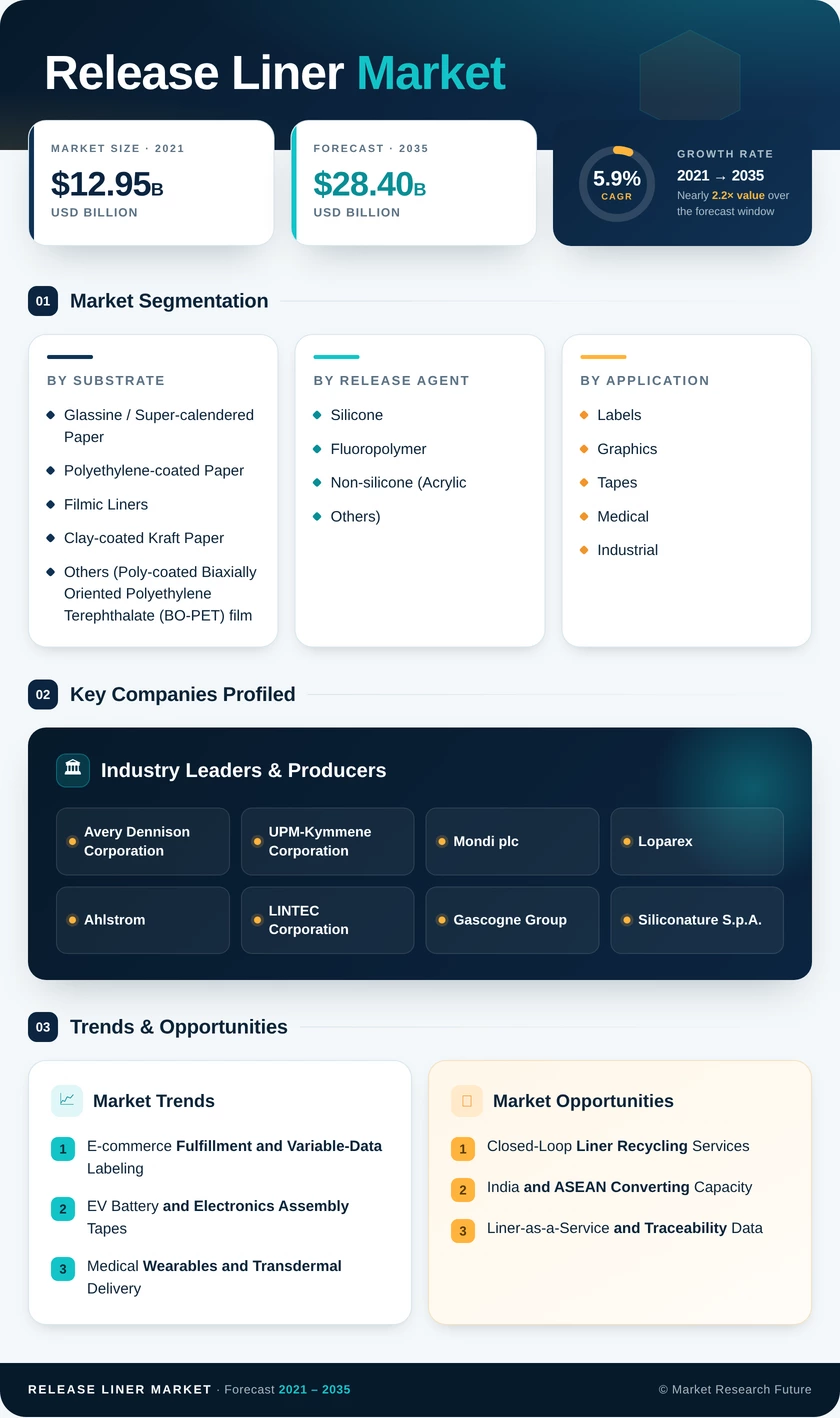
Release Liner Market (2026 - 2035)

ID: MRFR/CnM/4780-CR 128 Pages Chitranshi Jaiswal Last Updated: October 17, 2026
Release Liner Market Research Report Information By Substrate (Glassine / Super-calendered Paper, Polyethylene-coated Paper, Filmic Liners, Clay-coated Kraft Paper, and Others (Poly-coated Biaxially Oriented Polyethylene Terephthalate (BO-PET) film, etc.)), By Release Agent (Silicone, Fluoropolymer, and Non-silicone (Acrylic, Others)), By Application (Labels, Graphics, Tapes, Medical, Industrial, and Other Applications (Hygiene Products, etc.)), and By End-use Industry (Food and Beverage, Healthcare and Pharmaceuticals, Personal Care and Cosmetics, Automotive and Transportation, Electronics, Building and Construction, and Other End-user Industries (Agriculture, etc.)) – Forecast Till 2035
Release Liner Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.9%
2025 Market SizeUSD 16.01 Billion
2035 Market SizeUSD 28.40 Billion
Key Players
Avery Dennison Corporation
UPM-Kymmene Corporation
Mondi plc
Loparex
Ahlstrom
LINTEC Corporation
Opportunities
  • Closed-Loop Liner Recycling Services
  • India and ASEAN Converting Capacity
  • Liner-as-a-Service and Traceability Data
  1. 1 Market Summary | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Substrate | |
    2. 2.2 By Release Agent | |
    3. 2.3 By Application | |
    4. 2.4 By End-use Industry | |
    5. 2.5 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 E-commerce Fulfillment and Variable-Data Labeling | |
    2. 4.2 EV Battery and Electronics Assembly Tapes | |
    3. 4.3 Medical Wearables and Transdermal Delivery | |
    4. 4.4 Asia-Pacific Converting Capacity Expansion | |
    5. 4.5 Food Safety and Traceability Labeling Rules | |
    6. 4.6 High-Speed, Low-Energy Silicone Cure | |
    7. 4.7 Liner Recycling and Circularity Programs | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Pulp and Silicone Feedstock Price Volatility | |
    2. 5.2 Liner Waste Disposal Costs and Recyclability Mandates | |
    3. 5.3 PFAS Restrictions on Fluoropolymer Release Agents | |
    4. 5.4 Linerless Label Substitution | |
    5. 5.5 High Energy Costs and European Mill Rationalization | |
  6. 6 Opportunities | |
    1. 6.1 Closed-Loop Liner Recycling Services | |
    2. 6.2 India and ASEAN Converting Capacity | |
    3. 6.3 Liner-as-a-Service and Traceability Data | |
    4. 6.4 PFAS-Free High-Performance Release Chemistry | |
    5. 6.5 Medical Wearables and Diagnostic Strips | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 Asia-Pacific | | |
      1. 7.1.1 China | | |
      2. 7.1.2 Japan | | |
      3. 7.1.3 India | | |
      4. 7.1.4 South Korea | | |
      5. 7.1.5 ASEAN Countries | | |
      6. 7.1.6 Rest of Asia-Pacific | |
    2. 7.2 North America | | |
      1. 7.2.1 United States | | |
      2. 7.2.2 Canada | | |
      3. 7.2.3 Mexico | |
    3. 7.3 Europe | | |
      1. 7.3.1 Germany | | |
      2. 7.3.2 United Kingdom | | |
      3. 7.3.3 France | | |
      4. 7.3.4 Italy | | |
      5. 7.3.5 Spain | | |
      6. 7.3.6 Russia | | |
      7. 7.3.7 NORDIC Countries | | |
      8. 7.3.8 Rest of Europe | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East and Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 South Africa | | |
      3. 7.5.3 Rest of Middle East and Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Downgauging and Thin-Film Engineering | |
    2. 8.2 Circularity Compliance and Digital Product Passports | |
    3. 8.3 Electrification and Electronics Supply Chains | |
    4. 8.4 Automation and Inline Quality Analytics | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Substrate | | |
      1. 9.1.1 Glassine / Super-calendered Paper | | |
      2. 9.1.2 Polyethylene-coated Paper | | |
      3. 9.1.3 Filmic Liners | | |
      4. 9.1.4 Clay-coated Kraft Paper | | |
      5. 9.1.5 Others (Poly-coated Biaxially Oriented Polyethylene Terephthalate (BO-PET) film, etc.) | |
    2. 9.2 By Release Agent | | |
      1. 9.2.1 Silicone | | |
      2. 9.2.2 Fluoropolymer | | |
      3. 9.2.3 Non-silicone (Acrylic, Others) | |
    3. 9.3 By Application | | |
      1. 9.3.1 Labels | | |
      2. 9.3.2 Graphics | | |
      3. 9.3.3 Tapes | | |
      4. 9.3.4 Medical | | |
      5. 9.3.5 Industrial | | |
      6. 9.3.6 Other Applications (Hygiene Products, etc.) | |
    4. 9.4 By End-use Industry | | |
      1. 9.4.1 Food and Beverage | | |
      2. 9.4.2 Healthcare and Pharmaceuticals | | |
      3. 9.4.3 Personal Care and Cosmetics | | |
      4. 9.4.4 Automotive and Transportation | | |
      5. 9.4.5 Electronics | | |
      6. 9.4.6 Building and Construction | | |
      7. 9.4.7 Other End-user Industries (Agriculture, etc.) | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis | |
    2. 10.2 Competitive Benchmarking Table | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 Avery Dennison Corporation | | |
      2. 10.3.2 UPM-Kymmene Corporation | | |
      3. 10.3.3 Mondi plc | | |
      4. 10.3.4 Loparex | | |
      5. 10.3.5 Ahlstrom | | |
      6. 10.3.6 LINTEC Corporation | | |
      7. 10.3.7 3M Company | | |
      8. 10.3.8 Gascogne Group | | |
      9. 10.3.9 Siliconature S.p.A. | | |
      10. 10.3.10 Polyplex Corporation | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Global Market Snapshot, 2025–2035 | |
  16. TABLE 2 Global Market Size and Forecast, by Revenue (USD Billion), 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis, 2026–2035 | |
  18. TABLE 4 Restraints Impact Analysis, 2026–2035 | |
  19. TABLE 5 Global Market Share, by Region, 2025 | |
  20. TABLE 6 Asia-Pacific Market, by Country, 2025 | |
  21. TABLE 7 North America Market, by Country, 2025 | |
  22. TABLE 8 Europe Market, by Country, 2025 | |
  23. TABLE 9 South America Market, by Country, 2025 | |
  24. TABLE 10 Middle East and Africa Market, by Country, 2025 | |
  25. TABLE 11 Global Market, by Substrate, 2025 | |
  26. TABLE 12 Global Market, by Release Agent, 2025 | |
  27. TABLE 13 Global Market, by Application, 2025 | |
  28. TABLE 14 Global Market, by End-use Industry, 2025 | |
  29. TABLE 15 Competitive Benchmarking Table, 2025 | |
  30. TABLE 16 Report Scope and Methodology | |
  31. TABLE 17 Detailed Sources and Citations | |
  32. TABLE 18 Segmentation Quick Reference | | LIST OF FIGURES | |
  33. FIGURE 1 Market Dynamics Overview (Drivers, Restraints, Opportunities) | |
  34. FIGURE 2 Industry Value Chain Analysis | |
  35. FIGURE 3 Porter's Five Forces Analysis | |
  36. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Billion) | |
  37. FIGURE 5 Year-over-Year Growth Trend, 2021–2035 | |
  38. FIGURE 6 Market Share by Substrate, 2025 | |
  39. FIGURE 7 Market Share by Release Agent, 2025 | |
  40. FIGURE 8 Market Share by Application, 2025 | |
  41. FIGURE 9 Market Share by End-use Industry, 2025 | |
  42. FIGURE 10 Regional Market Share, 2025 | |
  43. FIGURE 11 Country-Level Market Comparison, 2025 | |
  44. FIGURE 12 Competitive Landscape Positioning Matrix, 2025

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By SubstrateGlassine / Super-calendered Paper; Polyethylene-coated Paper; Filmic Liners; Clay-coated Kraft Paper; Others (Poly-coated Biaxially Oriented Polyethylene Terephthalate (BO-PET) film, etc.)Glassine / Super-calendered Paper (34.2% share)Others (Poly-coated Biaxially Oriented Polyethylene Terephthalate (BO-PET) film, etc.) (7.6% CAGR)
By Release AgentSilicone; Fluoropolymer; Non-silicone (Acrylic, Others)Silicone (75.0% share)Fluoropolymer (6.9% CAGR)
By ApplicationLabels; Graphics; Tapes; Medical; Industrial; Other Applications (Hygiene Products, etc.)Labels (56.0% share)Medical (7.1% CAGR)
By End-use IndustryFood and Beverage; Healthcare and Pharmaceuticals; Personal Care and Cosmetics; Automotive and Transportation; Electronics; Building and Construction; Other End-user Industries (Agriculture, etc.)Food and Beverage (26.8% share)Healthcare and Pharmaceuticals (7.2% CAGR)
By RegionAsia-Pacific; North America; Europe; South America; Middle East and AfricaAsia-Pacific (41.8%)Asia-Pacific (41.8%)

Market Segmentation Overview

By Substrate

Sub-SegmentKey Trend
Glassine / Super-calendered PaperLower-grammage, barrier-enhanced grades for recyclable labels
Polyethylene-coated PaperMoisture resistance for chilled-food and outdoor labels
Filmic LinersThin PET and BOPP for electronics and automotive laminates
Clay-coated Kraft PaperStable demand in tapes, graphics and industrial rolls
Others (Poly-coated Biaxially Oriented Polyethylene Terephthalate (BO-PET) film, etc.)PTFE-coated cloth and composites for high-heat uses

Glassine / Super-calendered Paper leads at a 34.2% share because its smooth, dense surface supports fast die-cutting and food-contact compliance. Others (Poly-coated Biaxially Oriented Polyethylene Terephthalate (BO-PET) film, etc.) grow fastest at a 7.6% CAGR as composite molding and electronics require thermal stability that cellulosic papers cannot provide. Filmic Liners gain from the same shift, while Clay-coated Kraft Paper holds its position in tapes.

By Release Agent

Sub-SegmentKey Trend
SiliconeSolventless and UV platinum cure at higher line speeds
FluoropolymerHigh-temperature composites amid PFAS scrutiny
Non-silicone (Acrylic, Others)Silicone-free electronics and PFAS-free replacements

Silicone holds a 75.0% share thanks to versatile cure chemistries and low coat weights. Fluoropolymer expands fastest at a 6.9% CAGR in aerospace composites and aggressive tapes, though PFAS restrictions limit its packaging use. Non-silicone (Acrylic, Others) benefits where siloxane migration would contaminate sensitive electronic components.

By Application

Sub-SegmentKey Trend
LabelsAutomated fulfillment demands tight caliper control
GraphicsRemovable decals face direct-print substitution
TapesBattery and smartphone assembly specify flame-retardant liners
MedicalSterilization-stable liners for wearables and dressings
IndustrialComposite molding and gasket production
Other Applications (Hygiene Products, etc.)Hygiene closures shifting to PFAS-free release coatings

Labels lead at a 56.0% share because parcel and product labeling runs on high-speed applicators that need flat, uniform liners. Medical grows fastest at a 7.1% CAGR as wearables and transdermal systems require low-extractable liners that survive sterilization. Tapes add demand from battery assembly, while Graphics faces pressure from direct-print alternatives.

By End-use Industry

Sub-SegmentKey Trend
Food and BeverageTraceability and food-contact compliance in labels
Healthcare and PharmaceuticalsBreathable dressing and wearable qualification
Personal Care and CosmeticsOptically flawless liners for decorated packaging
Automotive and TransportationBattery bonding and EMI shielding tapes
ElectronicsAnti-static film liners for flexible circuits
Building and ConstructionMembrane roofing and glazing tapes
Other End-user Industries (Agriculture, etc.)Agri-input labels and crop film tapes

Food and Beverage leads with a 26.8% share, driven by labels and bakery sheets subject to food-contact and traceability rules. Healthcare and Pharmaceuticals grows fastest at a 7.2% CAGR as dressing and wearable programs move through qualification. Automotive and Transportation follows on battery tape demand, while Electronics depends on anti-static film liners.


Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.