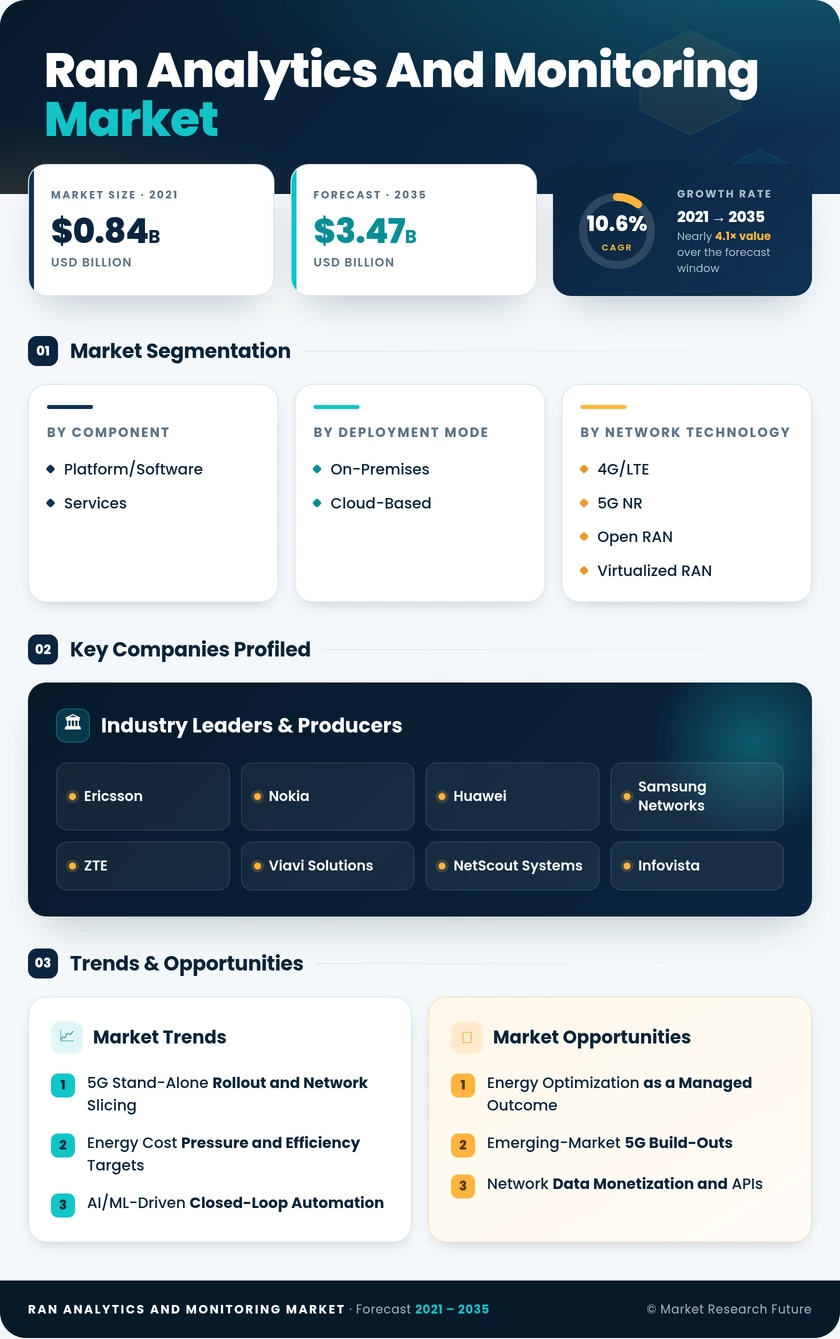
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|
| By Component | Platform/Software; Services | Platform/Software (64.3% share) | Services (12.4% CAGR) |
| By Deployment Mode | On-Premises; Cloud-Based | Cloud-Based (11.8% CAGR) | Cloud-Based (11.8% CAGR) |
| By Network Technology | 4G/LTE; 5G NR; Open RAN and Virtualized RAN | 4G/LTE (47.2% share) | 5G NR (14.1% CAGR) |
| By Application | Performance Management; Fault and Event Management; Energy and Capacity Optimization; Mobility and Interference Optimization; Network Slice Assurance | Performance Management (34.5% share) | Energy and Capacity Optimization (15.2% CAGR) |
| By End User | Tier-1 Mobile Network Operators; Tier-2 and Regional Operators; Mobile Virtual Network Operators; Private Enterprise Networks; Tower Companies and Neutral-Host Providers | Tier-1 Mobile Network Operators (49.6% share) | Private Enterprise Networks (13.5% CAGR) |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | North America (36.8% share) | Asia-Pacific (12.9% CAGR) |
Market Segmentation Overview
| Sub-Segment | Key Trend |
|---|
| Platform/Software | Cloud-native analytics engines with embedded AI models |
| Services | Outcome-based integration and lifecycle management contracts |
Platform/Software leads because Tier-1 operators want direct control of data models, dashboards and machine-learning pipelines. Services grow faster as multi-vendor counter normalization and continuous model retraining outstrip in-house engineering capacity. Integrators and vendors are responding with managed offerings priced against measurable network outcomes.
| Sub-Segment | Key Trend |
|---|
| On-Premises | Retained for low-latency control and data-residency compliance |
| Cloud-Based | Auto-scaling telemetry ingestion and hyperscaler AI integration |
Cloud-Based deployment leads and grows fastest because telemetry volumes from dense 5G grids favor elastic infrastructure. On-Premises persists where GDPR or national localization rules require subscriber-linked data to stay in-country. Hybrid policy frameworks spanning edge and cloud are becoming a key vendor differentiator.
| Sub-Segment | Key Trend |
|---|
| 4G/LTE | Continued optimization of a large installed base |
| 5G NR | Slice-aware assurance and stand-alone feature monitoring |
| Open RAN and Virtualized RAN | Standards-based telemetry through O1, E2 and A1 interfaces |
4G/LTE holds the largest share because most operational cells still carry LTE layers requiring tuning and fault management. 5G NR grows fastest as stand-alone cores introduce slicing and energy features that need new analytics modules. Open RAN and Virtualized RAN, while smaller, supply the richest standardized data for edge machine learning.
| Sub-Segment | Key Trend |
|---|
| Performance Management | Unified KPI dashboards across vendors and generations |
| Fault and Event Management | AI-based alarm correlation and automated root-cause analysis |
| Energy and Capacity Optimization | Automated sleep modes and power-aware scheduling |
| Mobility and Interference Optimization | Handover tuning for dense small-cell layers |
| Network Slice Assurance | Per-slice SLA verification for enterprise contracts |
Performance Management remains the leading application and the usual entry point for platform purchases. Energy and Capacity Optimization grows fastest because electricity costs and efficiency targets deliver a short, verifiable payback. Network Slice Assurance follows closely as operators begin selling guaranteed-performance 5G slices to industrial customers.
| Sub-Segment | Key Trend |
|---|
| Tier-1 Mobile Network Operators | Large-scale automation and proprietary analytics stacks |
| Tier-2 and Regional Operators | Subscription-based, vendor-managed platforms |
| Mobile Virtual Network Operators | Experience monitoring on host network infrastructure |
| Private Enterprise Networks | Simplified, prescriptive tools integrated with OT systems |
| Tower Companies and Neutral-Host Providers | Multi-tenant visibility and shared-site SLAs |
Tier-1 Mobile Network Operators dominate spending because their multi-vendor estates and autonomy programs require full-featured platforms. Private Enterprise Networks grow fastest as factories, ports and mines deploy dedicated 5G without round-the-clock network staff. Tower Companies and Neutral-Host Providers add a further growth pocket, needing to prove service levels to every tenant operator.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA