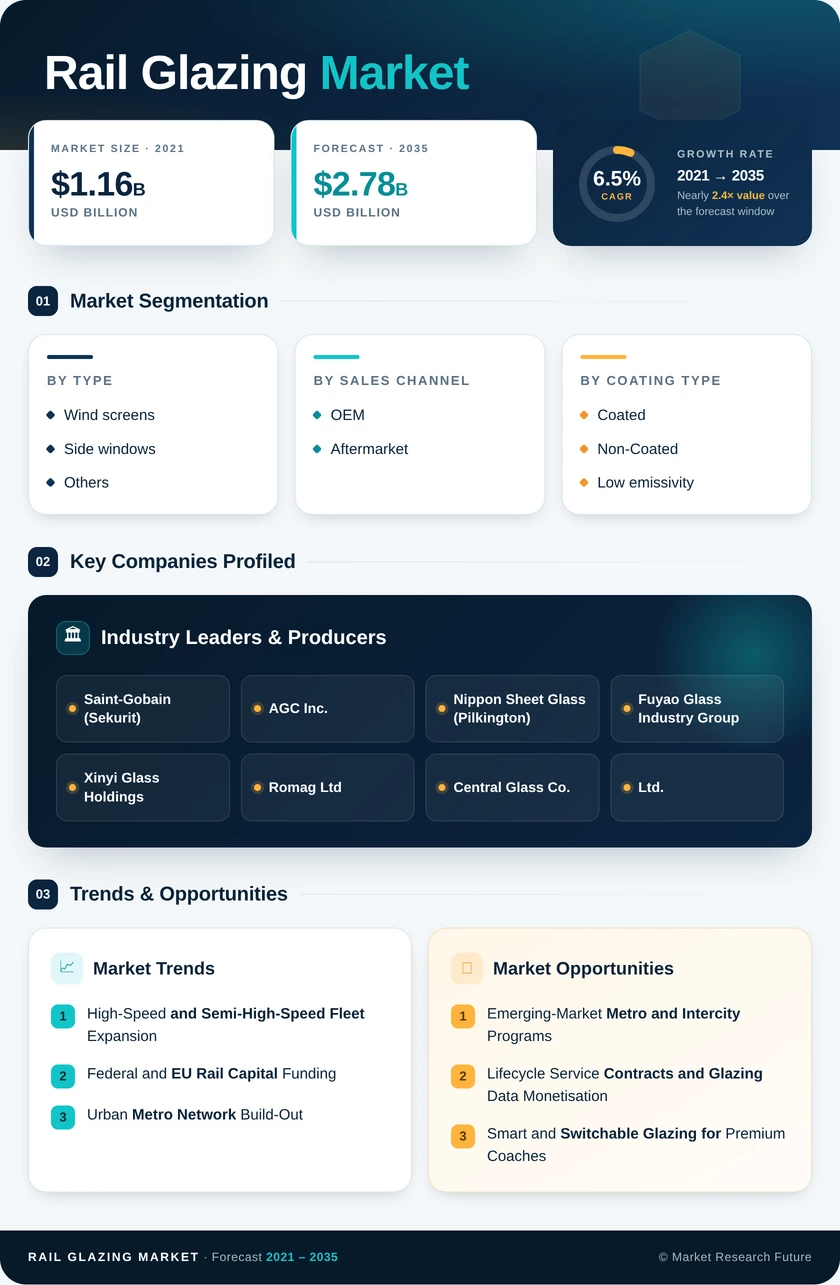
Rail Glazing Market (2026 - 2035)

ID: MRFR/AT/41987-HCR 128 Pages Abbas Raut Last Updated: October 21, 2026
Rail Glazing Market Research Report By Type (Wind Screens, Side Windows, Others), By Sales Channel (OEM, Aftermarket), By Coating Type (Coated, Non-Coated, Low Emissivity) - Forecast to 2035
Rail Glazing Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.5%
2025 Market SizeUSD 1.48 Billion
2035 Market SizeUSD 2.78 Billion
Key Players
Saint-Gobain
AGC Inc.
Nippon Sheet Glass
Fuyao Glass Industry Group
Xinyi Glass Holdings
Romag Ltd
Opportunities
  • Emerging-Market Metro and Intercity Programs
  • Lifecycle Service Contracts and Glazing Data Monetisation
  • Smart and Switchable Glazing for Premium Coaches
  1. 1 Market Summary | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Type | |
    2. 2.2 By Sales Channel | |
    3. 2.3 By Coating Type | |
    4. 2.4 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 High-Speed and Semi-High-Speed Fleet Expansion | |
    2. 4.2 Federal and EU Rail Capital Funding | |
    3. 4.3 Urban Metro Network Build-Out | |
    4. 4.4 Stricter Windscreen and Fire-Safety Certification | |
    5. 4.5 Fleet Refurbishment and Life-Extension Programs | |
    6. 4.6 Energy-Efficiency Targets for HVAC Loads | |
    7. 4.7 Premium and Long-Distance Tourism Rail | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 High Raw-Material and Energy Costs | |
    2. 5.2 Lengthy Certification and Homologation Cycles | |
    3. 5.3 Project Delays and Public Budget Constraints | |
    4. 5.4 Substitution by Polycarbonate and Polymer Glazing | |
    5. 5.5 Supplier Concentration and Long Lead Times | |
  6. 6 Opportunities | |
    1. 6.1 Emerging-Market Metro and Intercity Programs | |
    2. 6.2 Lifecycle Service Contracts and Glazing Data Monetisation | |
    3. 6.3 Smart and Switchable Glazing for Premium Coaches | |
    4. 6.4 Connectivity-Ready Coated Glass | |
    5. 6.5 Lightweight Glazing for Battery and Hydrogen Trains | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 United States | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Rest of North America | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 United Kingdom | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 India | | |
      2. 7.3.2 China | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of MEA | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Connected and Switchable Glazing Becomes Standard | |
    2. 8.2 High-Speed Build-Out Redefines Performance Benchmarks | |
    3. 8.3 Decarbonisation and Lightweighting | |
    4. 8.4 Circular Materials and ESG Disclosure | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Type | | |
      1. 9.1.1 Wind screens | | |
      2. 9.1.2 Side windows | | |
      3. 9.1.3 Others | |
    2. 9.2 By Sales Channel | | |
      1. 9.2.1 OEM | | |
      2. 9.2.2 Aftermarket | |
    3. 9.3 By Coating Type | | |
      1. 9.3.1 Coated | | |
      2. 9.3.2 Non-Coated | | |
      3. 9.3.3 Low emissivity | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis | |
    2. 10.2 Competitive Benchmarking Matrix | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Global Market Summary Snapshot, 2025–2035 | |
  16. TABLE 2 Global Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis, 2026–2035 | |
  18. TABLE 4 Restraints Impact Analysis, 2026–2035 | |
  19. TABLE 5 Regional Summary, 2025 | |
  20. TABLE 6 North America, by Country, 2025 | |
  21. TABLE 7 Europe, by Country, 2025 | |
  22. TABLE 8 Asia-Pacific, by Country, 2025 | |
  23. TABLE 9 South America, by Country, 2025 | |
  24. TABLE 10 Middle East & Africa, by Country, 2025 | |
  25. TABLE 11 Global Market Size, by Type, 2021–2035 (USD Billion) | |
  26. TABLE 12 Global Market Size, by Sales Channel, 2021–2035 (USD Billion) | |
  27. TABLE 13 Global Market Size, by Coating Type, 2021–2035 (USD Billion) | |
  28. TABLE 14 Competitive Benchmarking Matrix, 2025 | |
  29. TABLE 15 Report Scope and Methodology | |
  30. TABLE 16 Detailed Sources and Citations | | LIST OF FIGURES | |
  31. FIGURE 1 Market Dynamics Overview – Drivers, Restraints and Opportunities | |
  32. FIGURE 2 Industry Value Chain Analysis | |
  33. FIGURE 3 Porter's Five Forces Analysis | |
  34. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Billion) | |
  35. FIGURE 5 Market Share, by Type, 2025 (%) | |
  36. FIGURE 6 Market Share, by Sales Channel, 2025 (%) | |
  37. FIGURE 7 Market Share, by Coating Type, 2025 (%) | |
  38. FIGURE 8 Regional Market Share, 2025 (%) | |
  39. FIGURE 9 Country-Level Share Within Asia-Pacific, 2025 (%) | |
  40. FIGURE 10 Competitive Landscape – Estimated Revenue Share Ranges, 2025

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By TypeWind screens; Side windows; OthersSide windows (54.0% share)Wind screens (7.1% CAGR)
By Sales ChannelOEM; AftermarketOEM (67.5% share)Aftermarket (7.3% CAGR)
By Coating TypeCoated; Non-Coated; Low emissivityCoated (46.0% share)Low emissivity (8.2% CAGR)
By RegionNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaAsia-Pacific (41.5% share)Asia-Pacific (41.5% share)

Market Segmentation Overview

By Type

Sub-SegmentKey Trend
Wind screensShift to heated, multi-ply laminated cab glass with defined sensor zones
Side windowsBonded flush glazing replacing gasketed designs on new fleets
OthersPanoramic roof panels and glazed partitions in premium coaches

Side windows lead on volume because every passenger car carries dozens of panes, and bonded flush designs have become the default on new high-speed and metro stock. Wind screens grow fastest since EN 15152 impact ratings, heating elements and camera zones for driver assistance raise unit value far above side glazing. Others gain from panoramic and tourism coach designs that enlarge glazed area per vehicle.

By Sales Channel

Sub-SegmentKey Trend
OEMMulti-year platform contracts tied to trainset certification
AftermarketFramework agreements bundling spares, inventory and fitting

OEM supply leads because glazing is certified as part of vehicle authorisation, locking suppliers into a platform for its production run. Aftermarket grows faster as operators choose life extension over replacement and as breakage from stone strikes and vandalism creates recurring demand. Long lead times for custom windscreens push operators toward stocked-spares arrangements that favour incumbent OEM suppliers.

By Coating Type

Sub-SegmentKey Trend
CoatedSolar-control layers standard on air-conditioned rolling stock
Non-CoatedRetained in cost-sensitive commuter fleets and freight cabs
Low emissivityRF-transparent, laser-patterned coatings enabling onboard connectivity

Coated glazing leads as solar-control layers have become baseline specification for air-conditioned passenger fleets. Low emissivity grows fastest because it reduces HVAC energy use, and frequency-selective patterning now resolves the mobile-signal attenuation that once limited its adoption. Non-Coated products hold their position where price and certified impact resistance outweigh thermal performance, such as commuter stock and locomotive cabs.


Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.