Pump Jack Market (2026 - 2035)

ID: MRFR/EnP/6972-HCR 111 Pages Priya Nagrale Last Updated: September 15, 2026
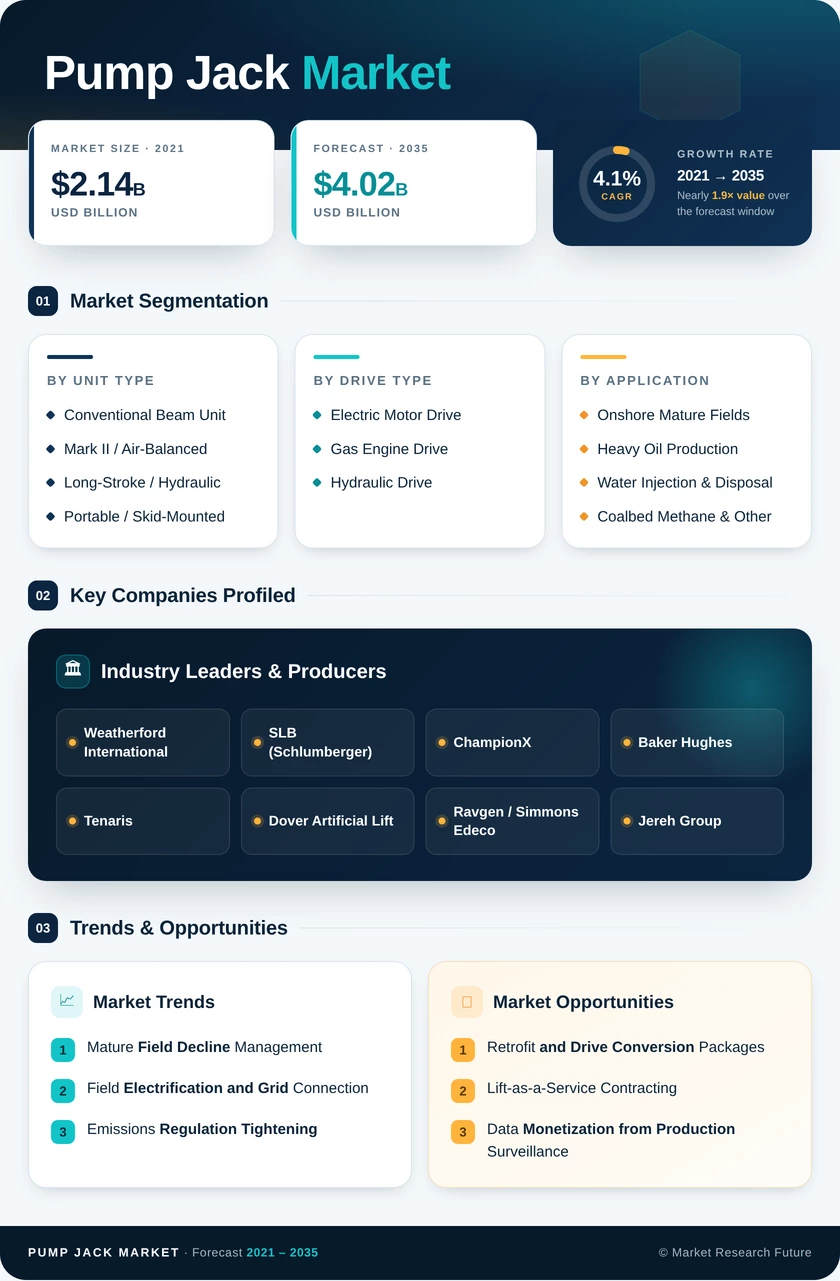
Pump Jack Market Research Report By Unit Type (Conventional Beam Unit, Mark II / Air-Balanced, Long-Stroke / Hydraulic, Portable / Skid-Mounted), By Drive Type (Electric Motor Drive, Gas Engine Drive, Hydraulic Drive), By Application (Onshore Mature Fields, Heavy Oil Production, Water Injection & Disposal, Coalbed Methane & Other) - Forecast to 2035
Pump Jack Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)4.1%
2025 Market SizeUSD 2.71 Billion
2035 Market SizeUSD 4.02 Billion
Key Players
Weatherford International
SLB
ChampionX
Baker Hughes
Tenaris
Dover Artificial Lift
Opportunities
  • Retrofit and Drive Conversion Packages
  • Lift-as-a-Service Contracting
  • Data Monetization from Production Surveillance
  1. 1 Market Summary | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Technology | |
    2. 2.2 By Sector | |
    3. 2.3 By Geography | |
  3. 3 Market Size & Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Current & Forecast Market Size (2026–2035) | |
    3. 3.3 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Mature Field Decline Management | |
    2. 4.2 Field Electrification and Grid Connection | |
    3. 4.3 Emissions Regulation Tightening | |
    4. 4.4 Digital Lift Optimization | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Competing Artificial Lift Technologies | |
    2. 5.2 Price Volatility and Capital Discipline | |
    3. 5.3 Orphan Well Plugging Programs | |
  6. 6 Opportunities | |
    1. 6.1 Retrofit and Drive Conversion Packages | |
    2. 6.2 Lift-as-a-Service Contracting | |
    3. 6.3 Data Monetization from Production Surveillance | |
    4. 6.4 Emerging Market Brownfield Redevelopment | |
    5. 6.5 Enhanced Oil Recovery Support | |
  7. 7 Regional Market Share & Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 United States | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Asia-Pacific | | |
      1. 7.2.1 China | | |
      2. 7.2.2 India | | |
      3. 7.2.3 Indonesia | |
    3. 7.3 Middle East & Africa | | |
      1. 7.3.1 Oman | | |
      2. 7.3.2 Saudi Arabia | | |
      3. 7.3.3 Nigeria | |
    4. 7.4 Europe | | |
      1. 7.4.1 Romania | | |
      2. 7.4.2 Germany | | |
      3. 7.4.3 United Kingdom | |
    5. 7.5 South America | | |
      1. 7.5.1 Argentina | | |
      2. 7.5.2 Colombia | | |
      3. 7.5.3 Brazil | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Autonomous Well Operations | |
    2. 8.2 Electrification Supercycle | |
    3. 8.3 ESG Disclosure and Asset Retirement Accounting | |
    4. 8.4 Supply Chain Regionalization | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Unit Type | | |
      1. 9.1.1 Conventional Beam Unit | | |
      2. 9.1.2 Mark II / Air-Balanced | | |
      3. 9.1.3 Long-Stroke / Hydraulic | | |
      4. 9.1.4 Portable / Skid-Mounted | |
    2. 9.2 By Drive Type | | |
      1. 9.2.1 Electric Motor Drive | | |
      2. 9.2.2 Gas Engine Drive | | |
      3. 9.2.3 Hydraulic Drive | |
    3. 9.3 By Application | | |
      1. 9.3.1 Onshore Mature Fields | | |
      2. 9.3.2 Heavy Oil Production | | |
      3. 9.3.3 Water Injection & Disposal | | |
      4. 9.3.4 Coalbed Methane & Other | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Share Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope & Methodology | |
  13. 13 Detailed Sources & Citations | |
  14. 14 Frequently Asked Questions | | LIST OF TABLES | | LIST OF FIGURES

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Unit TypeConventional Beam Unit; Mark II / Air-Balanced; Long-Stroke / Hydraulic; Portable / Skid-MountedConventional Beam UnitLong-Stroke / Hydraulic
By Drive TypeElectric Motor Drive; Gas Engine Drive; Hydraulic DriveElectric Motor DriveHydraulic Drive
By ApplicationOnshore Mature Fields; Heavy Oil Production; Water Injection & Disposal; Coalbed Methane & OtherOnshore Mature FieldsHeavy Oil Production
By RegionNorth America; Asia-Pacific; Middle East & Africa; Europe; South AmericaNorth AmericaMiddle East & Africa


Market Segmentation Overview

By Unit Type

Sub-SegmentKey Trend
Conventional Beam UnitReplacement-driven demand; universal parts availability sustains volume leadership
Mark II / Air-BalancedPreferred for deeper wells where peak torque reduction cuts gearbox wear
Long-Stroke / HydraulicFastest expansion as deviated and high-volume wells outgrow conventional geometry
Portable / Skid-MountedNiche growth tied to well testing and temporary production programs


Unit geometry choices increasingly follow wellbore profile rather than tradition. Operators running large deviated inventories are specifying longer strokes at the design stage, while conventional units hold the low-cost shallow-well tier.

By Drive Type

Sub-SegmentKey Trend
Electric Motor DriveGrid expansion and operating cost advantage drive continued share gains
Gas Engine DriveDeclining share; retained only where grid access is absent
Hydraulic DriveGrowth in space-constrained, urban, and offshore-adjacent installations


Drive selection has become the single biggest lever on lifetime operating cost. Utility infrastructure buildout in the Permian and Alberta is converting formerly stranded sites, and each conversion typically triggers a full surface equipment refresh.

By Application

Sub-SegmentKey Trend
Onshore Mature FieldsLargest installed base; decline management sustains replacement volume
Heavy Oil ProductionHigh-viscosity duty accelerates equipment wear and premium specification
Water Injection & DisposalRising produced water volumes in shale basins expand service well demand
Coalbed Methane & OtherSteady dewatering demand in select Asia-Pacific and North American basins


Application mix is shifting toward duty cycles that stress equipment harder. Heavy oil and disposal service wells shorten replacement intervals, which lifts aftermarket revenue even where new-well activity stays flat.



Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.