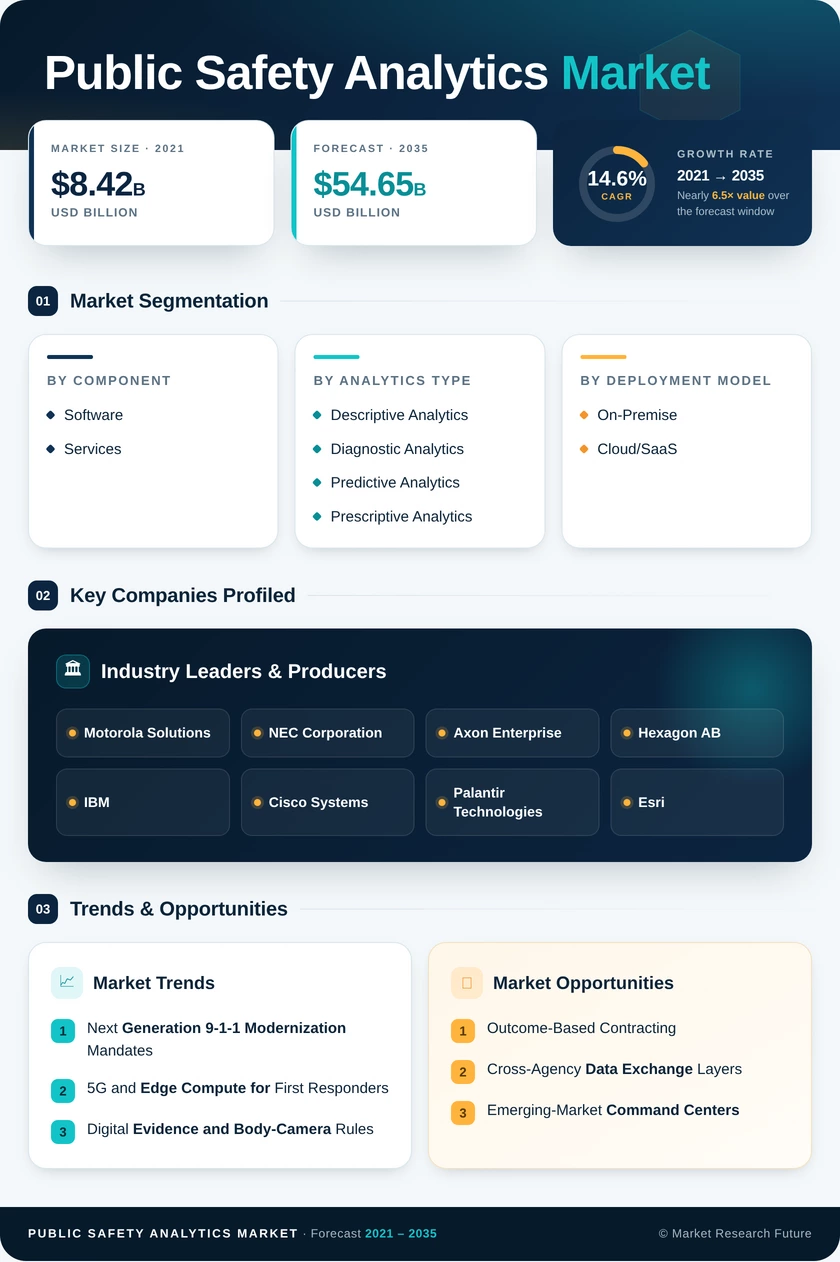
Market Segmentation Analysis
By Component
9.1.1 Software
9.1.2 Services
By Analytics Type
9.2.1 Descriptive Analytics
9.2.2 Diagnostic Analytics
9.2.3 Predictive Analytics
9.2.4 Prescriptive Analytics
By Deployment Model
9.3.1 On-Premise
9.3.2 Cloud/SaaS
By Application
9.4.1 Person-of-Interest Screening
9.4.2 Surveillance
9.4.3 Incident Detection
9.4.4 Pattern Recognition
9.4.5 Resource Optimisation
By End-User
9.5.1 Law Enforcement
9.5.2 Emergency Medical Services
9.5.3 Firefighting
9.5.4 Transportation & Critical Infrastructure
9.5.5 Other End-Users
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Component | Software; Services | Software (58.7% share, 2025) | Services (16.0% CAGR) |
| By Analytics Type | Descriptive Analytics; Diagnostic Analytics; Predictive Analytics; Prescriptive Analytics | Predictive Analytics (36.3% share, 2025) | Prescriptive Analytics (15.4% CAGR) |
| By Deployment Model | On-Premise; Cloud/SaaS | On-Premise (54.3% share, 2025) | Cloud/SaaS (15.6% CAGR) |
| By Application | Person-of-Interest Screening; Surveillance; Incident Detection; Pattern Recognition; Resource Optimisation | Surveillance (29.9% share, 2025) | Resource Optimisation (15.3% CAGR) |
| By End-User | Law Enforcement; Emergency Medical Services; Firefighting; Transportation & Critical Infrastructure; Other End-Users | Law Enforcement (30.9% share, 2025) | Transportation & Critical Infrastructure (15.4% CAGR) |
Market Segmentation Overview
By Component
| Sub-Segment | Key Trend |
| Software | Record Management and investigation suites bundled with geospatial overlays |
| Services | Managed model maintenance and legacy data migration under multi-year contracts |
Software holds the leading position because Record Management modules sit directly on statutory reporting obligations, which protects them during budget review in a way that discretionary analytical tooling is not protected. Services grow fastest at a 16.0% CAGR because agencies buy analytical capability they cannot staff — model retraining, evidentiary data hygiene, and court-defensible documentation all require skills that county IT departments rarely hold. Vendors increasingly retain rotating data scientists shared across several jurisdictions, and that pooling is what makes the services economics work for small buyers.
By Analytics Type
| Sub-Segment | Key Trend |
| Descriptive Analytics | Statutory incident and crime reporting automation |
| Diagnostic Analytics | Clearance-rate root-cause and after-action review |
| Predictive Analytics | Hourly-refreshed hot-spot forecasting for patrol allocation |
| Prescriptive Analytics | Ambulance and apparatus repositioning recommendations |
Predictive Analytics leads with 36.3% of 2025 revenue because hot-spot forecasting was the first capability agencies could defend to elected officials with a countable metric. Prescriptive Analytics grows fastest at 15.4% because a forecast alone still leaves the commander deciding where to stage units, and fire departments working against the six-minute NFPA response benchmark need a recommendation rather than a probability surface. Descriptive Analytics stays structurally stable given mandatory federal reporting, while Diagnostic Analytics expands where prosecutors require documented investigative reasoning.
By Deployment Model
| Sub-Segment | Key Trend |
| On-Premise | Evidence custody retained inside agency-controlled infrastructure. |
| Cloud/SaaS | Burst inference for video workloads under FedRAMP High authorization |
On-Premise retains 54.3% of spending because criminal evidence carries custody and residency obligations that many jurisdictions read as prohibiting multitenant storage outright. Cloud/SaaS grows fastest at 15.6% as the pool of FedRAMP High authorized providers widens and as video inference volumes make fixed local capacity uneconomic to size. The practical settlement is hybrid: master evidence files stay on agency servers while redaction, transcription, and inference burst outward, trimming five-year ownership cost by roughly 18%.
By Application
| Sub-Segment | Key Trend |
| Person-of-Interest Screening | Watchlist matching at ports, borders, and major venues |
| Surveillance | Automated review of body-worn and fixed camera footage |
| Incident Detection | Sensor and acoustic alerting integrated into dispatch. |
| Pattern Recognition | Serial-offense linkage and criminal network analysis |
| Resource Optimisation | Real-time apparatus and patrol repositioning |
Surveillance dominates with 29.9% of 2025 revenue because camera mandates created a review workload no department can staff manually, making automation a compliance necessity rather than an efficiency choice. Resource Optimisation grows fastest at 15.3% since repositioning platforms produce a measurable response-time improvement near 8%, which finance officers can audit. Person-of-Interest Screening advances more slowly under public scrutiny, while Incident Detection benefits from falling acoustic and environmental sensor costs.
By End-User
| Sub-Segment | Key Trend |
| Law Enforcement | Case management, evidence tracking, community-facing dashboards |
| Emergency Medical Services | Overdose hot-spot routing funded through public-health grants |
| Firefighting | Engine placement tuned against response-time benchmarks. |
| Transportation & Critical Infrastructure | Anomaly detection across airports, rail hubs, and utilities |
| Other End-Users | Campus, corrections, and event-security operations |
Law Enforcement remains the largest buyer at 30.9% of 2025 spending, though its share dilutes as adjacent departments enter with independent funding. Transportation & Critical Infrastructure expands fastest at 15.4% because those operators face security obligations without the community-consent friction policing encounters, and they fund from operating revenue rather than tax appropriations. Emergency Medical Services adoption accelerated once public-health grants began covering routing software, and Firefighting follows a slower but steady path tied to accreditation benchmarks.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA