Polystyrene Market (2026 - 2035)

ID: MRFR/CnM/1905-CR 135 Pages Anshula Mandaokar Last Updated: October 14, 2026
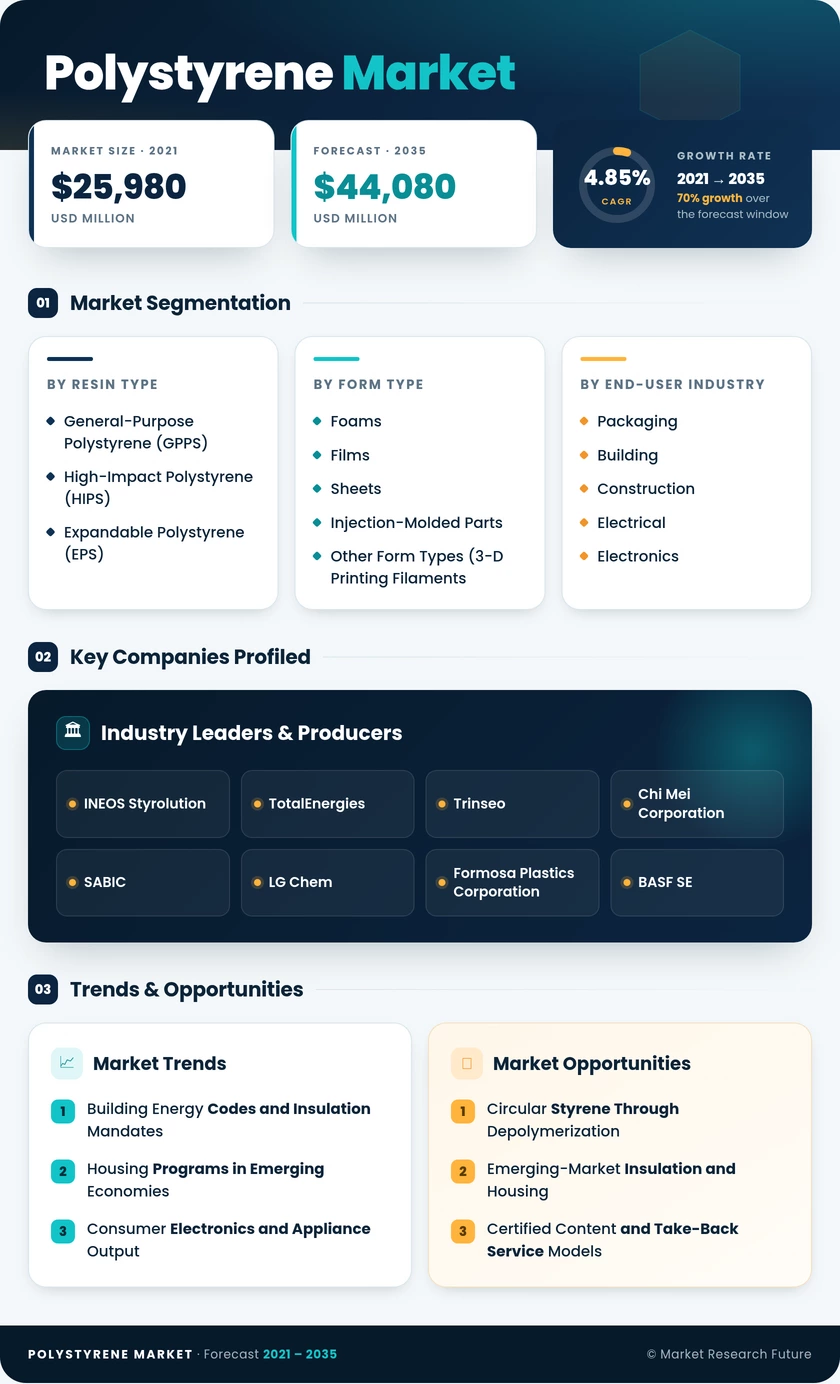
Polystyrene Market Research Report Information By Resin Type (General-Purpose Polystyrene (GPPS), High-Impact Polystyrene (HIPS), and Expandable Polystyrene (EPS)), By Form Type (Foams, Films and Sheets, Injection-Molded Parts, and Other Form Types (3-D Printing Filaments, etc.)), and By End-user Industry (Packaging, Building and Construction, Electrical and Electronics, Consumer Goods, and Other End user Industries (Automotive and Transportation, Medical Devices)) – Forecast Till 2035.
Polystyrene Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)4.85%
2025 Market SizeUSD 27,450 Million
2035 Market SizeUSD 44,080 Million
Key Players
INEOS Styrolution
TotalEnergies
Trinseo
Chi Mei Corporation
SABIC
LG Chem
Opportunities
  • Circular Styrene Through Depolymerization
  • Emerging-Market Insulation and Housing
  • Certified Content and Take-Back Service Models
  1. 1 Market Summary | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Resin Type | |
    2. 2.2 By Form Type | |
    3. 2.3 By End-user Industry | |
    4. 2.4 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Building Energy Codes and Insulation Mandates | |
    2. 4.2 Housing Programs in Emerging Economies | |
    3. 4.3 Consumer Electronics and Appliance Output | |
    4. 4.4 Food-Contact Packaging Innovation | |
    5. 4.5 Cold-Chain Pharmaceutical Shipping | |
    6. 4.6 Chemical Recycling Scale-Up | |
    7. 4.7 Automotive Interior Cost Substitution | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Single-Use Foam Bans | |
    2. 5.2 Feedstock Price Volatility | |
    3. 5.3 Low Recycling Rates and Producer Fees | |
    4. 5.4 Substitution by Alternative Resins and Fiber | |
    5. 5.5 Styrene Health Classification Scrutiny | |
  6. 6 Opportunities | |
    1. 6.1 Circular Styrene Through Depolymerization | |
    2. 6.2 Emerging-Market Insulation and Housing | |
    3. 6.3 Certified Content and Take-Back Service Models | |
    4. 6.4 Specialty Films and 3-D Printing Filaments | |
    5. 6.5 Medical and Cold-Chain Packaging | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 Asia-Pacific | | |
      1. 7.1.1 China | | |
      2. 7.1.2 India | | |
      3. 7.1.3 Japan | | |
      4. 7.1.4 South Korea | | |
      5. 7.1.5 Rest of Asia-Pacific | |
    2. 7.2 North America | | |
      1. 7.2.1 United States | | |
      2. 7.2.2 Canada | | |
      3. 7.2.3 Mexico | |
    3. 7.3 Europe | | |
      1. 7.3.1 Germany | | |
      2. 7.3.2 United Kingdom | | |
      3. 7.3.3 France | | |
      4. 7.3.4 Italy | | |
      5. 7.3.5 Rest of Europe | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle-East and Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 South Africa | | |
      3. 7.5.3 Rest Middle-East and Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Circular Feedstock and Mass-Balance Accounting | |
    2. 8.2 Building Decarbonization | |
    3. 8.3 Asian Capacity Rationalization | |
    4. 8.4 Digitalized Process Control | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Resin Type | | |
      1. 9.1.1 General-Purpose Polystyrene (GPPS) | | |
      2. 9.1.2 High-Impact Polystyrene (HIPS) | | |
      3. 9.1.3 Expandable Polystyrene (EPS) | |
    2. 9.2 By Form Type | | |
      1. 9.2.1 Foams | | |
      2. 9.2.2 Films and Sheets | | |
      3. 9.2.3 Injection-Molded Parts | | |
      4. 9.2.4 Other Form Types (3-D Printing Filaments, etc.) | |
    3. 9.3 By End-user Industry | | |
      1. 9.3.1 Packaging | | |
      2. 9.3.2 Building and Construction | | |
      3. 9.3.3 Electrical and Electronics | | |
      4. 9.3.4 Consumer Goods | | |
      5. 9.3.5 Other End user Industries (Automotive and Transportation, Medical Devices) | |
  10. 10 Competitive Landscape | |
  11. 11 Recent News and Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Global Polystyrene Industry Summary, 2025 and 2035 | |
  16. TABLE 2 Global Market Size and Forecast, by Value (USD Million), 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis, 2026–2035 | |
  18. TABLE 4 Restraints Impact Analysis, 2026–2035 | |
  19. TABLE 5 Regional Summary, 2025 | |
  20. TABLE 6 Asia-Pacific Market, by Country, 2025 | |
  21. TABLE 7 North America Market, by Country, 2025 | |
  22. TABLE 8 Europe Market, by Country, 2025 | |
  23. TABLE 9 South America Market, by Country, 2025 | |
  24. TABLE 10 Middle-East and Africa Market, by Country, 2025 | |
  25. TABLE 11 Market Segmentation, by Resin Type, 2025 | |
  26. TABLE 12 Market Segmentation, by Form Type, 2025 | |
  27. TABLE 13 Market Segmentation, by End-user Industry, 2025 | |
  28. TABLE 14 Competitive Benchmarking Matrix, 2025 | |
  29. TABLE 15 Report Scope and Methodology | |
  30. TABLE 16 Detailed Sources and Citations | |
  31. TABLE 17 Segmentation Quick Reference | |
  32. TABLE 18 Segmentation Overview, by Resin Type | |
  33. TABLE 19 Segmentation Overview, by Form Type | |
  34. TABLE 20 Segmentation Overview, by End-user Industry | | LIST OF FIGURES | |
  35. FIGURE 1 Market Dynamics Overview (Drivers, Restraints, Opportunities) | |
  36. FIGURE 2 Industry Value Chain Analysis | |
  37. FIGURE 3 Porter's Five Forces Analysis | |
  38. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Million) | |
  39. FIGURE 5 Share by Resin Type, 2025 (%) | |
  40. FIGURE 6 Share by Form Type, 2025 (%) | |
  41. FIGURE 7 Share by End-user Industry, 2025 (%) | |
  42. FIGURE 8 Regional Share, 2025 (%) | |
  43. FIGURE 9 Country-Level Share within Asia-Pacific, 2025 (%) | |
  44. FIGURE 10 Competitive Landscape Positioning Map, 2025 | |
  45. FIGURE 11 Estimated Revenue Share Ranges of Key Players, 2025

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Resin TypeGeneral-Purpose Polystyrene (GPPS); High-Impact Polystyrene (HIPS); Expandable Polystyrene (EPS)Expandable Polystyrene (EPS) (48.6% share)General-Purpose Polystyrene (GPPS) (5.9% CAGR)
By Form TypeFoams; Films and Sheets; Injection-Molded Parts; Other Form Types (3-D Printing Filaments, etc.)Foams (64.1% share)Films and Sheets (5.4% CAGR)
By End-user IndustryPackaging; Building and Construction; Electrical and Electronics; Consumer Goods; Other End user Industries (Automotive and Transportation, Medical Devices)Packaging (47.3% share)Other End user Industries (Automotive and Transportation, Medical Devices) (5.6% CAGR)
By RegionAsia-Pacific; North America; Europe; South America; Middle-East and AfricaAsia-Pacific (52.4% share)Asia-Pacific (52.4% share)

Market Segmentation Overview

By Resin Type

Sub-SegmentKey Trend
General-Purpose Polystyrene (GPPS)Clear food-contact cups and trays sustain above-average growth
High-Impact Polystyrene (HIPS)Appliance and electronics housings track Asian production cycles
Expandable Polystyrene (EPS)Insulation codes offset foodservice bans

Expandable Polystyrene (EPS) leads because building codes keep raising R-value requirements and expandable boards deliver the lowest cost per unit of thermal resistance. General-Purpose Polystyrene (GPPS) grows fastest since its clarity and forming speed remain difficult to match in dairy and dessert packs. High-Impact Polystyrene (HIPS) sits between the two, with volumes moving in step with Chinese appliance and electronics output.

By Form Type

Sub-SegmentKey Trend
FoamsShare drifts lower as foodservice bans spread
Films and SheetsBarrier trays and blister packs lift demand
Injection-Molded PartsSteady use in appliances and vehicle interiors
Other Form Types (3-D Printing Filaments, etc.)Premium filaments for models and education

Foams dominate because insulation boards and cushioning packs consume large tonnages per application. Films and Sheets grow fastest as ready-meal producers and pharmaceutical packagers specify thermoformed barrier formats. Injection-Molded Parts and Other Form Types (3-D Printing Filaments, etc.) add smaller but higher-value volume tied to appliance design cycles and filament demand.

By End-user Industry

Sub-SegmentKey Trend
PackagingShift from foodservice foam toward food-contact and protective packs
Building and ConstructionRenovation mandates and housing programs drive board demand
Electrical and ElectronicsDevice housings follow Asian manufacturing output
Consumer GoodsPrice-sensitive toys and household items
Other End user Industries (Automotive and Transportation,Medical Devices)Interior trim, device casings and cold-chain shippers

Packaging remains the largest end use, though its growth slows as bans remove foodservice foam in North America and Europe. Other End user Industries (Automotive and Transportation,Medical Devices) grow fastest because HIPS replaces ABS in non-visible vehicle trim and medical buyers need validated, sterilization-compatible casings and shippers. Building and Construction ranks second, supported by insulation mandates that are less exposed to single-use regulation.


Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.