SEGMENTATION QUICK REFERENCE
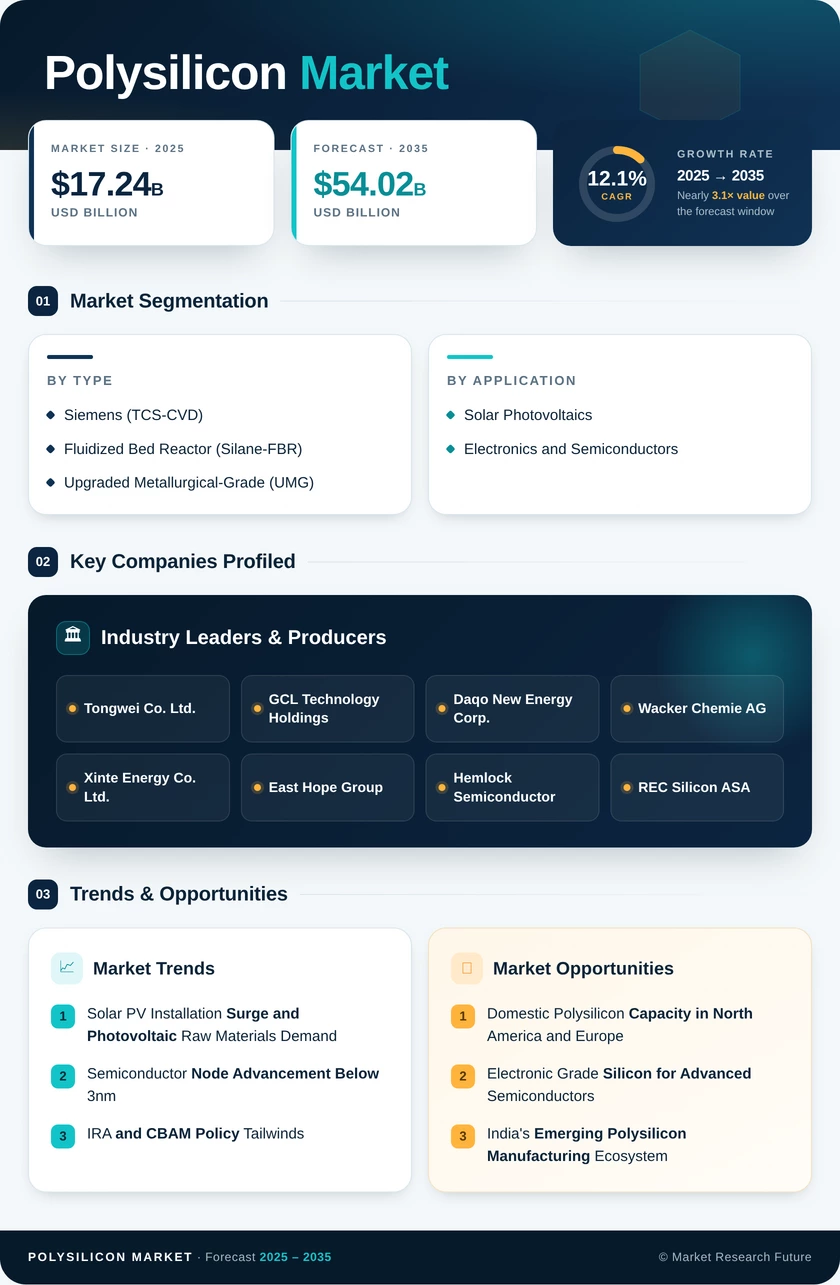
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Production Process | Siemens (TCS-CVD), Fluidized Bed Reactor (Silane-FBR), Upgraded Metallurgical-Grade (UMG) | Siemens (TCS-CVD) | Fluidized Bed Reactor (Silane-FBR) |
| By End-User Industry | Solar Photovoltaics, Electronics and Semiconductors | Solar Photovoltaics | Electronics and Semiconductors |
| By Geography | Asia-Pacific, North America, Europe, South America, the Middle East & Africa | Asia-Pacific | Asia-Pacific |
MARKET SEGMENTATION OVERVIEW
By Production Process
| Sub-Segment | Key Trend |
| Siemens (TCS-CVD) | Retains dominance in electronic-grade silicon, facing energy cost pressure from FBR |
| Fluidized Bed Reactor (Silane-FBR) | Rapid capacity expansion; 20–25% energy savings, driving cost-floor disruption |
| Upgraded Metallurgical-Grade (UMG) | Niche cost-sensitive applications; limited to lower-purity photovoltaic segments |
The Siemens process underpins the vast majority of global polysilicon supply, particularly for semiconductor and high-purity solar applications. FBR granular polysilicon is gaining ground rapidly, driven by GCL Polysilicon Market's commercialization success and the process's compatibility with continuous Czochralski ingot pulling for N-type solar cell manufacturing.
By End-User Industry
| Sub-Segment | Key Trend |
| Solar Photovoltaics | N-type cell transition increasing purity specifications; >420 GW annual installations |
| Electronics and Semiconductors | Sub-3nm node fabrication driving premium 11N+ purity demand at 8–15× price premium |
Solar Photovoltaics remains the volume driver of the global polysilicon market, with the transition from PERC to TOPCon and HJT architectures sustaining demand growth. Electronics and Semiconductors, while smaller in volume, deliver outsized value contribution as advanced chip fabrication expands in the United States, Europe, and East Asia.
By Geography
| Sub-Segment | Key Trend |
| Asia-Pacific | Chinese cost leadership; India emerging as a greenfield production hub |
| North America | IRA-driven reshoring; semiconductor supply chain sovereignty |
| Europe | CBAM carbon-premium advantage; Wacker Chemie anchoring domestic supply |
| South America | Nascent upstream development; Brazil metallurgical silicon base |
| Middle East & Africa | Low-cost solar-powered refining opportunity; Vision 2030 investments |
Asia-Pacific dominates both production and consumption, with China accounting for over 80% of regional capacity. Western markets are leveraging policy incentives to develop competitive domestic supply chains. At the same time, the Middle East represents a frontier opportunity for low-cost, low-carbon polysilicon refining co-located with abundant solar resources.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA