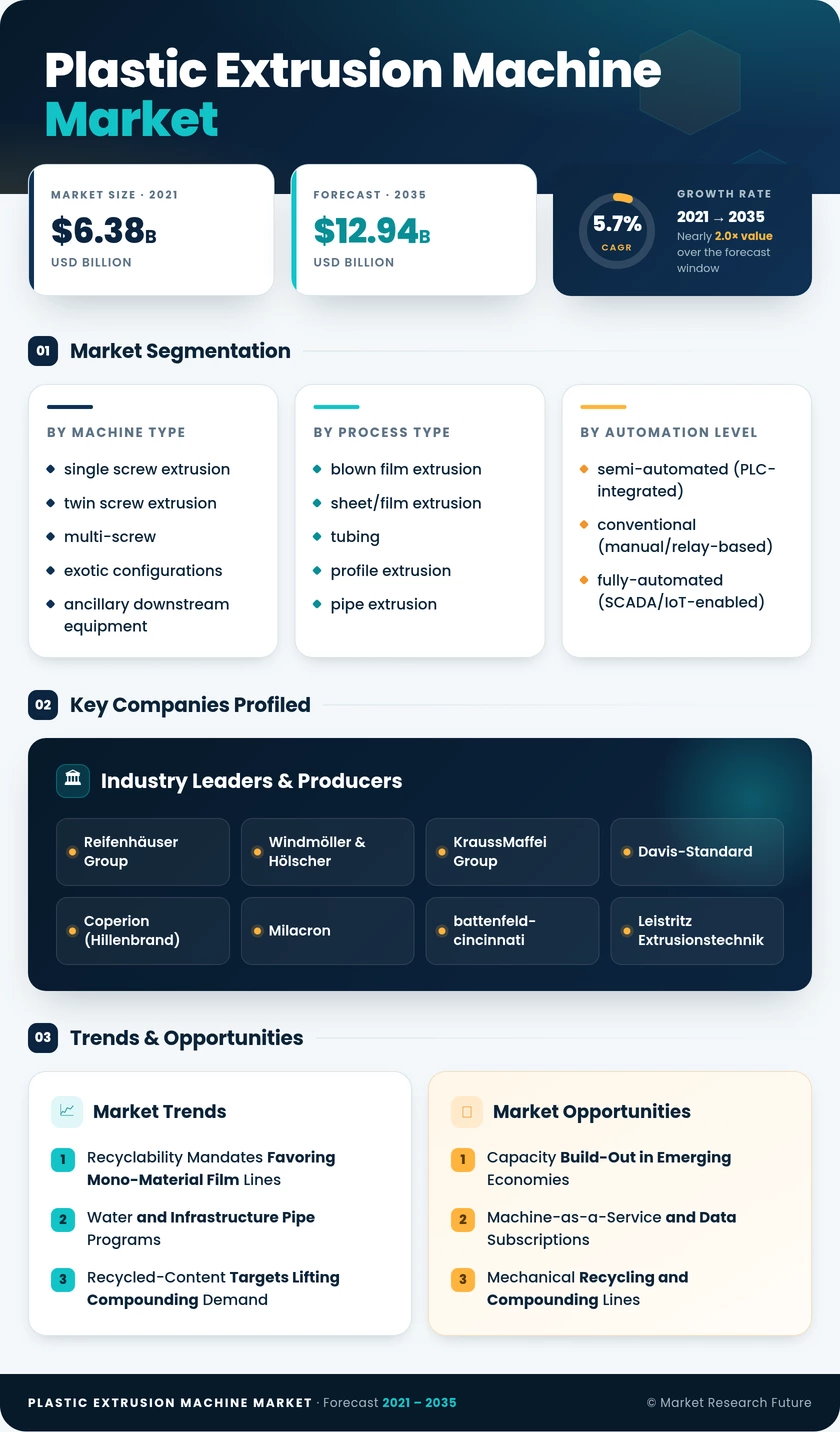
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Machine Type | single screw extrusion; twin screw extrusion; multi-screw and exotic configurations; ancillary downstream equipment | single screw extrusion (49.6% share) | twin screw extrusion (5.8% CAGR) |
| By Process Type | blown film extrusion; sheet/film extrusion; tubing and profile extrusion; pipe extrusion; extrusion coating and lamination; other process types | blown film extrusion (30.1% share) | extrusion coating and lamination (6.0% CAGR) |
| By Automation Level | semi-automated (PLC-integrated); conventional (manual/relay-based); fully-automated (SCADA/IoT-enabled) | semi-automated (42.9% share) | fully-automated (6.1% CAGR) |
| By End-user Industry | Packaging; Building and Construction; Automotive and Transportation; Electrical and Electronics; Consumer Goods and Appliances; Medical and Healthcare; Agriculture; Other End-user Industries | Packaging (37.3% share) | Medical and Healthcare (6.5% CAGR) |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | Asia-Pacific (47.2% share) | Asia-Pacific (6.4% CAGR) |
Market Segmentation Overview
By Machine Type
| Sub-Segment | Key Trend |
|---|---|
| single screw extrusion | Retains pipe and profile dominance on low maintenance needs |
| twin screw extrusion | Gains share through recycled and bio-based compounding. |
| multi-screw and exotic configurations | Serves high-output rigid PVC and specialty compounds |
| ancillary downstream equipment | Grows with every new line and with automation upgrades |
Single-screw extrusion leads with a 49.6% share because pipe and profile plants value its simple maintenance and steady output. Twin-screw extrusion grows fastest at 5.8% CAGR, since modular screw elements can degas and mix contaminated recycled flake that single-screw designs process inconsistently. Ancillary downstream equipment rides on both, as haul-offs, cutters, and winders are purchased with each new line.
By Process Type
| Sub-Segment | Key Trend |
|---|---|
| blown film extrusion | Shifting to seven-plus layer mono-material structures |
| sheet/film extrusion | Supports thermoformed trays and cast film |
| tubing and profile extrusion | Balances construction profiles with medical tubing |
| pipe extrusion | Anchored by water infrastructure programs |
| Extrusion coating and lamination | Replaces solvent-based laminates with co-extruded barriers |
| Other process types | Covers fiber, filament, and foam lines |
Blown film extrusion holds the largest share at 30.1% because flexible packaging dominates polyethylene demand. Extrusion coating and lamination grows fastest at 6.0% CAGR as EU recyclability grades push brands from mixed laminates to all-PE barrier structures. Pipe extrusion provides counter-cyclical stability through multi-year water programs in India and the United States.
By Automation Level
| Sub-Segment | Key Trend |
|---|---|
| semi-automated (PLC-integrated) | Default choice for mid-sized converters |
| conventional (manual/relay-based) | Persists in low labor-cost regions under export pressure |
| fully-automated (SCADA/IoT-enabled) | Expands with predictive maintenance and audit requirements |
Semi-automated PLC-integrated lines lead with a 42.9% share because they deliver reliable control without the integration cost of full SCADA systems. Fully-automated SCADA/IoT-enabled lines grow fastest at 6.1% CAGR, as converters facing labor shortages and zero-defect audits adopt edge analytics and bundled cloud monitoring. Conventional relay-based lines keep a foothold in Vietnam and Africa, though export customers' demand for logged process data steadily erodes it.
By End-user Industry
| Sub-Segment | Key Trend |
|---|---|
| Packaging | Redesign toward recyclable mono-materials |
| Building and Construction | Pipe and window profile demand from infrastructure |
| Automotive and Transportation | EV cable insulation and lightweight seals |
| Electrical and Electronics | Wire coating and battery separator films |
| Consumer Goods and Appliances | Appliance profiles and household products |
| Medical and Healthcare | Cleanroom micro-extrusion of catheters and tubing |
| Agriculture | Mulch film and drip irrigation pipe |
| Other End-user Industries | Filament, fibers, and niche applications |
Packaging leads with a 37.3% share, reflecting food and e-commerce demand now being reshaped by recyclability rules. Medical and Healthcare grows fastest at 6.5% CAGR because minimally invasive devices require micron-tolerance tubing produced on validated, cleanroom-compatible machines. Building and Construction remains the second-largest end use, supported by pipe and profile orders tied to public infrastructure spending.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA