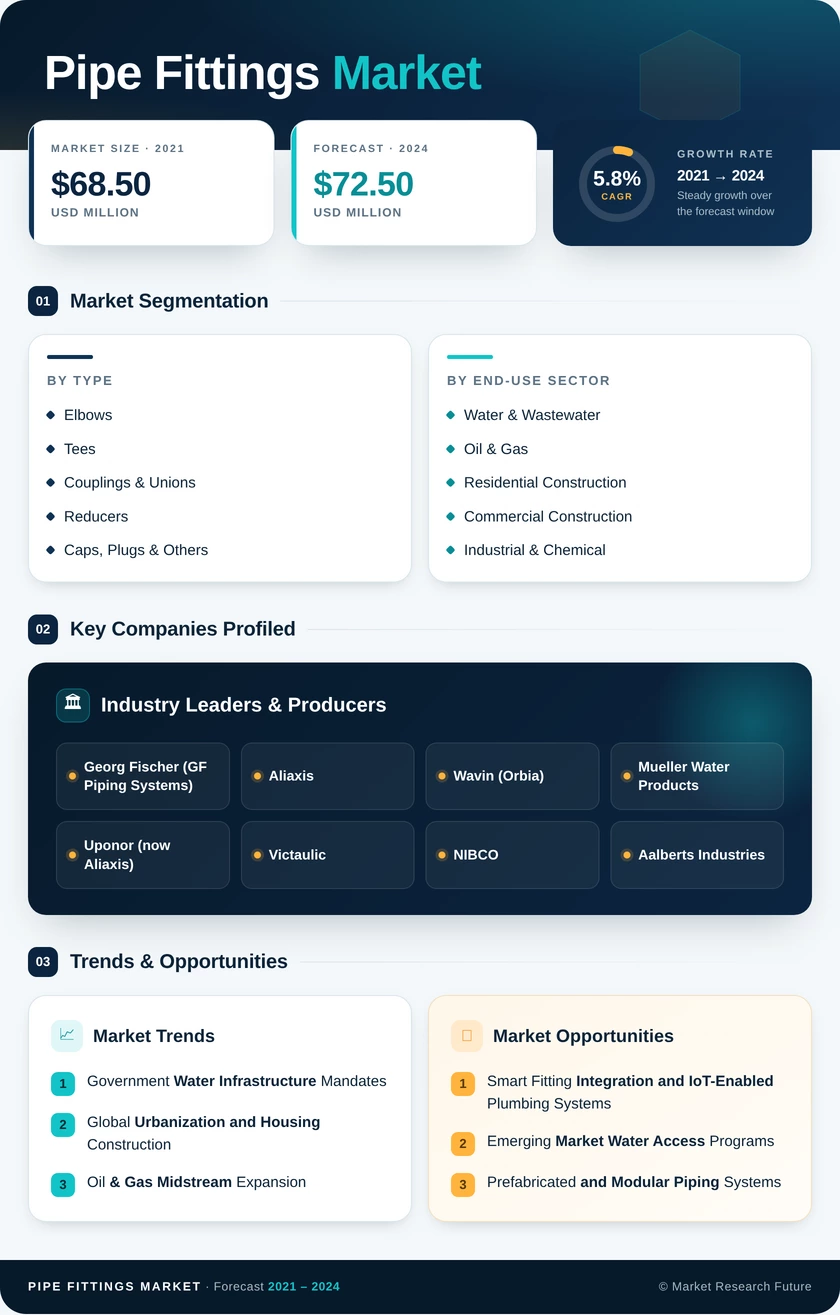
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Material Type | Plastic (PVC/CPVC/HDPE/PP), Steel (Carbon & Stainless), Copper, Cast Iron, Others (Brass, Composite, Ductile Iron) | Plastic (~38% share) | Steel (CAGR ~4.9%) |
| By Fitting Type | Elbows, Tees, Couplings & Unions, Reducers, Caps/Plugs & Others | Elbows (~26% share) | Tees (CAGR ~5.9%) |
| By End-Use Sector | Water & Wastewater, Oil & Gas, Residential Construction, Commercial Construction, Industrial & Chemical | Water & Wastewater (~31% share) | Oil & Gas (CAGR ~6.4%) |
Market Segmentation Overview
By Material Type
| Sub-Segment | Key Trend |
| Plastic (PVC/CPVC/HDPE/PP) | Corrosion resistance and lower lifecycle costs driving residential and municipal adoption |
| Steel (Carbon & Stainless) | Sustained demand from oil & gas, power generation, and high-pressure industrial systems |
| Copper | Stable demand in HVAC and medical gas; antimicrobial properties supporting healthcare use |
| Cast Iron | Legacy installed base in gravity drainage; gradual replacement by ductile iron and polymer |
| Others (Brass, Composite, Ductile Iron) | Composite fittings gaining traction in offshore and corrosive chemical environments |
Material selection in the pipe fittings market is driven by a combination of application requirements, installed cost, lifecycle performance, and regional code compliance. Plastic fittings continue to gain share in volume terms, while metal fittings retain dominance in high-value, high-specification applications where pressure ratings and temperature tolerance dictate material choice.
By Fitting Type
| Sub-Segment | Key Trend |
| Elbows | Standardized 90° and 45° configurations remain universal across all piping applications |
| Tees | Increasing complexity of distribution networks drives branch connection demand |
| Couplings & Unions | Modular and prefabricated piping systems elevate coupling and union consumption |
| Reducers | Flow optimization engineering and system efficiency mandates sustain reducer specification |
| Caps, Plugs & Others | Testing, commissioning, and temporary isolation requirements ensure baseline demand |
Fitting type demand within the pipe fittings market correlates directly with the complexity and scale of piping networks being constructed or rehabilitated. Elbows and tees together account for over 45% of unit sales, reflecting their indispensable role in routing piping around structural elements and creating distribution branches.
By End-Use Sector
| Sub-Segment | Key Trend |
| Water & Wastewater | Government-mandated universal access programs and aging network replacement |
| Oil & Gas | Midstream pipeline expansion and LNG terminal construction at scale |
| Residential Construction | Mass housing programs across Asia-Pacific and emerging markets |
| Commercial Construction | Data center, healthcare, and hospitality facility buildouts |
| Industrial & Chemical | Pharmaceutical, semiconductor, and food processing facility expansion |
End-use demand in the pipe fittings market is shifting toward infrastructure and institutional sectors as government spending commitments create multi-year procurement pipelines. While residential construction generates the highest fitting unit volumes, oil & gas and industrial applications deliver higher revenue per fitting due to stringent material specifications and certification requirements.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA