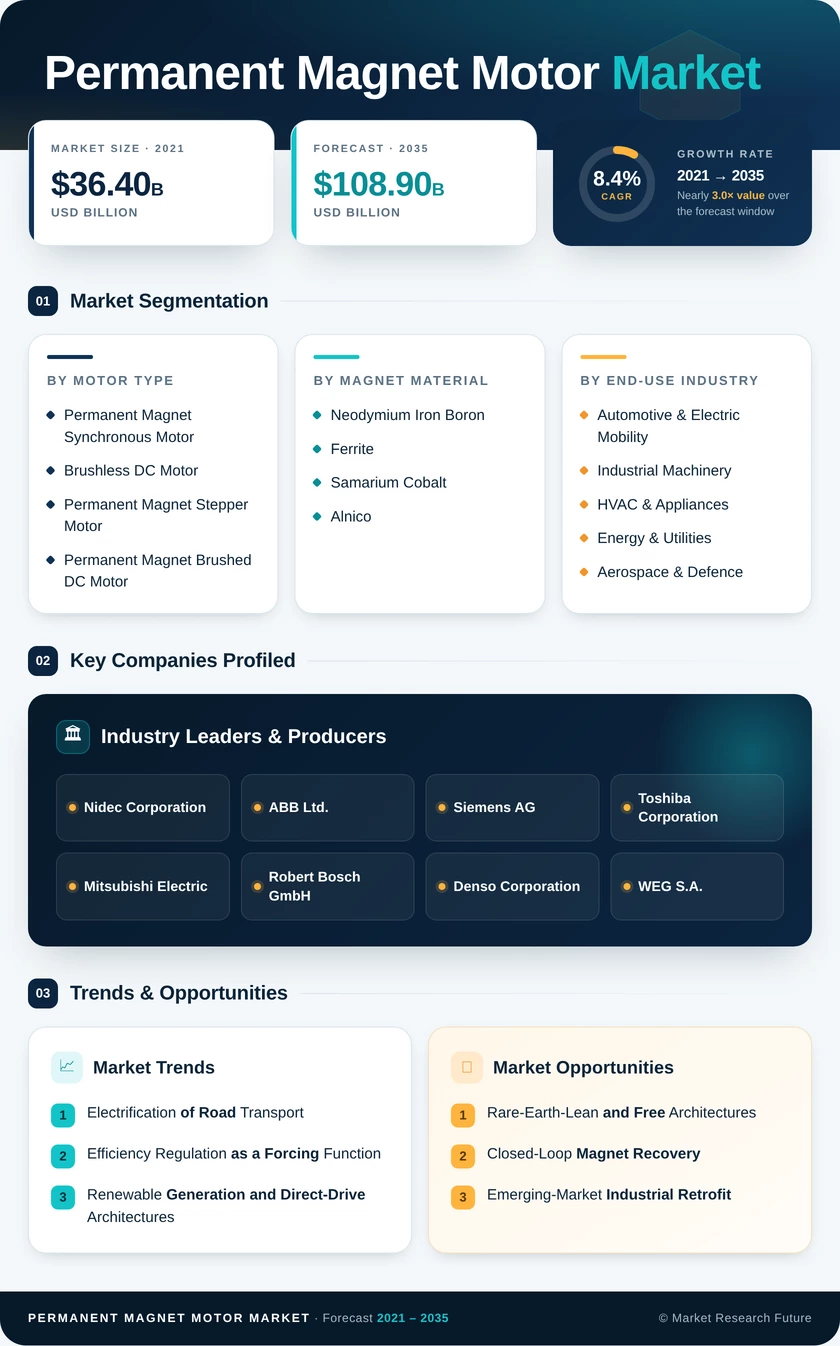
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Motor Type | Permanent Magnet Synchronous Motor; Brushless DC Motor; Permanent Magnet Stepper Motor; Permanent Magnet Brushed DC Motor | Permanent Magnet Synchronous Motor | Brushless DC Motor |
| By Magnet Material | Neodymium Iron Boron; Ferrite; Samarium Cobalt; Alnico | Neodymium Iron Boron | Samarium Cobalt |
| By End-Use Industry | Automotive & Electric Mobility; Industrial Machinery; HVAC & Appliances; Energy & Utilities; Aerospace & Defence; Medical & Others | Automotive & Electric Mobility | HVAC & Appliances |
| By Region | Asia-Pacific; Europe; North America; Middle East & Africa; South America | Asia-Pacific | Middle East & Africa |
Market Segmentation Overview
By Motor Type
| Sub-Segment | Key Trend |
| Permanent Magnet Synchronous Motor | Scales from kilowatt industrial duty to multi-megawatt direct-drive generators without architectural change |
| Brushless DC Motor | Displacing shaded-pole and universal motors across appliances and building ventilation |
| Permanent Magnet Stepper Motor | Steady niche demand in instrumentation, printing and laboratory automation |
| Permanent Magnet Brushed DC Motor | Persisting in automotive auxiliaries and power tools where cost outweighs efficiency |
Commutation choice increasingly follows drive electronics economics rather than motor cost alone. As integrated controllers fall in price, brushless architectures capture applications that brushed designs held on cost grounds for decades.
By Magnet Material
| Sub-Segment | Key Trend |
| Neodymium Iron Boron | Default choice for power density; exposed to quota and price volatility |
| Ferrite | Regaining share in cost-sensitive and supply-hedged designs |
| Samarium Cobalt | Preferred where junction temperatures exceed neodymium tolerance |
| Alnico | Confined to legacy replacement and specialty sensing applications |
Material selection has become a strategic decision rather than an engineering default. Procurement risk now sits alongside remanence and coercivity in the specification conversation, and reduced-rare-earth topologies are moving from research to production programmes.
By End-Use Industry
| Sub-Segment | Key Trend |
| Automotive & Electric Mobility | Largest volume pool; multi-year programme awards with intense pricing pressure |
| Industrial Machinery | Efficiency mandates driving compressed replacement cycles. |
| HVAC & Appliances | Building energy codes accelerating brushless conversion |
| Energy & Utilities | Offshore direct-drive generators concentrating high magnet content |
| Aerospace & Defence | More-electric aircraft actuation creating certification-gated premium demand. |
| Medical & Others | Imaging, infusion and surgical robotics requiring precision and low acoustic noise. |
Demand concentration in automotive brings scale but compresses margins, which is why several suppliers deliberately balance exposure with industrial and energy portfolios. Regulatory pull in HVAC and industrial segments provides the steadier revenue base beneath the electrification headline.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA