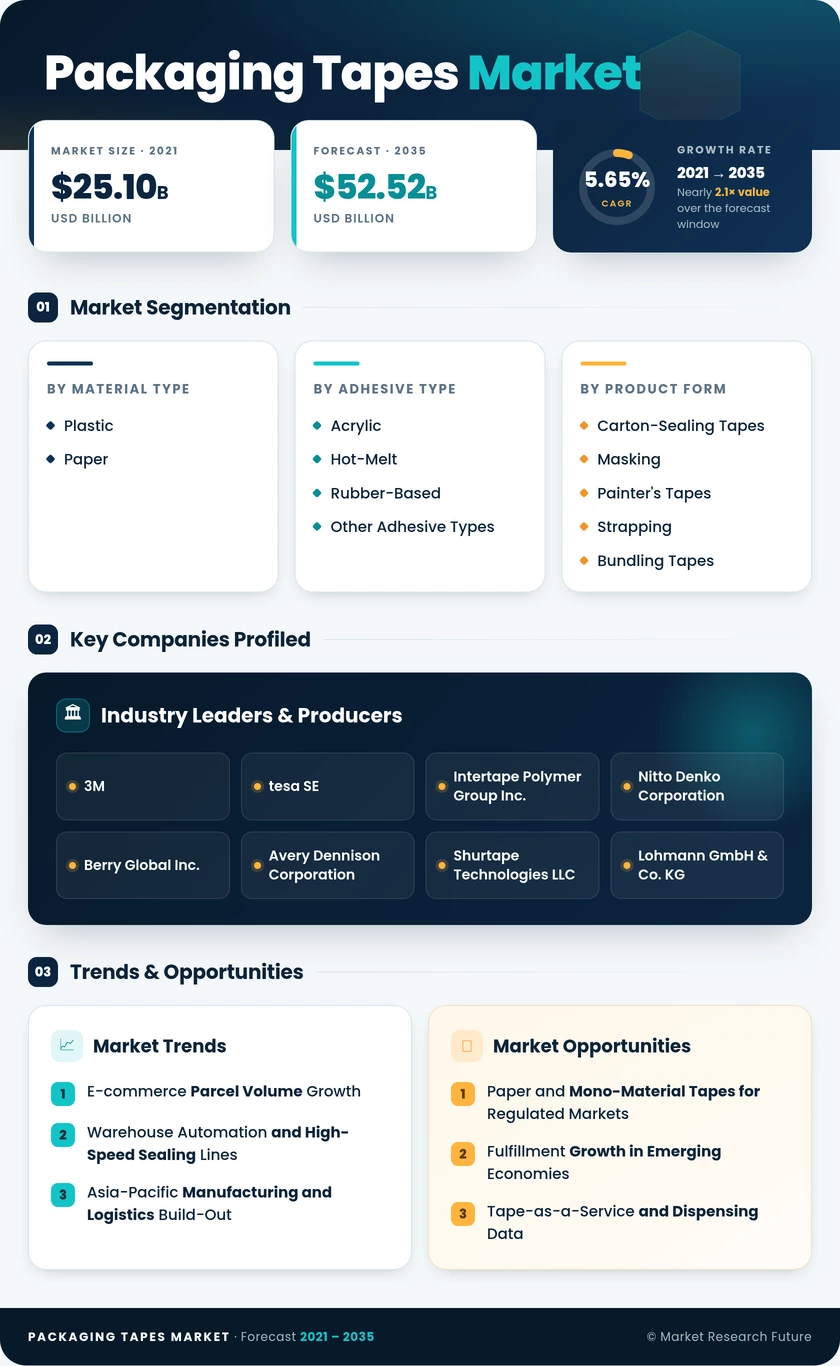
Packaging Tapes Market (2026 - 2035)

ID: MRFR/PCM/0897-HCR 115 Pages Varsha More Last Updated: November 20, 2026
Packaging Tapes Market Research Report Information By Material Type (Plastic and Paper), By Adhesive Type (Acrylic, Hot-Melt, Rubber-Based, and Other Adhesive Types), By Product Form (Carton-Sealing Tapes, Masking and Painter's Tapes, and Strapping and Bundling Tapes), By End-User Industry (E-commerce, Food and Beverage, Retail, and Other End-User Industries), And By Region (North America, Europe, Asia-Pacific, and Rest of the World) – Market Forecast Till 2035.
Packaging Tapes Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.65%
2025 Market SizeUSD 30.21 Billion
2035 Market SizeUSD 52.52 Billion
Key Players
3M
tesa SE
Intertape Polymer Group Inc.
Nitto Denko Corporation
Berry Global Inc.
Avery Dennison Corporation
Opportunities
  • Paper and Mono-Material Tapes for Regulated Markets
  • Fulfillment Growth in Emerging Economies
  • Tape-as-a-Service and Dispensing Data
  1. 1 Market Summary | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Material Type | |
    2. 2.2 By Adhesive Type | |
    3. 2.3 By Product Form | |
    4. 2.4 By End-user Industry | |
    5. 2.5 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 E-commerce Parcel Volume Growth | |
    2. 4.2 Warehouse Automation and High-Speed Sealing Lines | |
    3. 4.3 Asia-Pacific Manufacturing and Logistics Build-Out | |
    4. 4.4 Recyclability Mandates Favoring Paper and Mono-Material Tapes | |
    5. 4.5 Cold-Chain Food and Pharmaceutical Distribution | |
    6. 4.6 Omnichannel Retail Replenishment | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Resin and Energy Price Volatility | |
    2. 5.2 Plastic Taxes and EPR Fees on Film-Backed Tapes | |
    3. 5.3 Packaging Right-Sizing and Tape-Light Designs | |
    4. 5.4 VOC and Solvent Emission Limits | |
    5. 5.5 Price Competition from Fragmented Regional Converters | |
  6. 6 Opportunities | |
    1. 6.1 Paper and Mono-Material Tapes for Regulated Markets | |
    2. 6.2 Fulfillment Growth in Emerging Economies | |
    3. 6.3 Tape-as-a-Service and Dispensing Data | |
    4. 6.4 Certified Cold-Chain and Pharmaceutical Grades | |
    5. 6.5 Printed Security and Authentication Tapes | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 Asia-Pacific | | |
      1. 7.1.1 China | | |
      2. 7.1.2 India | | |
      3. 7.1.3 Japan | | |
      4. 7.1.4 South Korea | | |
      5. 7.1.5 Rest of Asia-Pacific | |
    2. 7.2 North America | | |
      1. 7.2.1 United States | | |
      2. 7.2.2 Canada | | |
      3. 7.2.3 Mexico | |
    3. 7.3 Europe | | |
      1. 7.3.1 Germany | | |
      2. 7.3.2 United Kingdom | | |
      3. 7.3.3 France | | |
      4. 7.3.4 Italy | | |
      5. 7.3.5 Rest of Europe | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle-East and Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 South Africa | | |
      3. 7.5.3 Rest of Middle-East and Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 AI-Guided Converting and Sealing Lines | |
    2. 8.2 Circular Packaging Rules Redraw Material Choices | |
    3. 8.3 Parcel Economy Matures Toward Right-Sized Packaging | |
    4. 8.4 Bio-Based Adhesives and Energy-Cost Exposure | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Material Type | | |
      1. 9.1.1 Plastic | | |
      2. 9.1.2 Paper | |
    2. 9.2 By Adhesive Type | | |
      1. 9.2.1 Acrylic | | |
      2. 9.2.2 Hot-Melt | | |
      3. 9.2.3 Rubber-Based | | |
      4. 9.2.4 Other Adhesive Types | |
    3. 9.3 By Product Form | | |
      1. 9.3.1 Carton-Sealing Tapes | | |
      2. 9.3.2 Masking and Painter's Tapes | | |
      3. 9.3.3 Strapping and Bundling Tapes | |
    4. 9.4 By End-user Industry | | |
      1. 9.4.1 E-commerce | | |
      2. 9.4.2 Food and Beverage | | |
      3. 9.4.3 Retail | | |
      4. 9.4.4 Other End-user Industries | |
  10. 10 Competitive Landscape | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Global Market Size and Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Driver Impact Analysis, 2026–2035 | |
  17. TABLE 3 Restraints Impact Analysis, 2026–2035 | |
  18. TABLE 4 Regional Summary, by Share of 2025 Revenue | |
  19. TABLE 5 Asia-Pacific Market, by Country, 2025 | |
  20. TABLE 6 North America Market, by Country, 2025 | |
  21. TABLE 7 Europe Market, by Country, 2025 | |
  22. TABLE 8 South America Market, by Country, 2025 | |
  23. TABLE 9 Middle-East and Africa Market, by Country, 2025 | |
  24. TABLE 10 Global Market, by Material Type, 2025 | |
  25. TABLE 11 Global Market, by Adhesive Type, 2025 | |
  26. TABLE 12 Global Market, by Product Form, 2025 | |
  27. TABLE 13 Global Market, by End-user Industry, 2025 | |
  28. TABLE 14 Competitive Benchmarking Matrix, 2025 | |
  29. TABLE 15 Report Scope and Methodology | |
  30. TABLE 16 Detailed Sources and Citations | | LIST OF FIGURES | |
  31. FIGURE 1 Market Dynamics Overview (Drivers, Restraints, Opportunities) | |
  32. FIGURE 2 Industry Value Chain Analysis | |
  33. FIGURE 3 Porter's Five Forces Analysis | |
  34. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Billion) | |
  35. FIGURE 5 Market Share by Material Type, 2025 | |
  36. FIGURE 6 Market Share by Adhesive Type, 2025 | |
  37. FIGURE 7 Market Share by Product Form, 2025 | |
  38. FIGURE 8 Market Share by End-user Industry, 2025 | |
  39. FIGURE 9 Regional Market Share, 2025 | |
  40. FIGURE 10 Competitive Landscape and Estimated Revenue Share Ranges, 2025

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Material TypePlastic; PaperPlastic (67.4%)Paper (6.38% CAGR)
By Adhesive TypeAcrylic; Hot-Melt; Rubber-Based; Other Adhesive TypesAcrylic (41.5%)Rubber-Based (6.19% CAGR)
By Product FormCarton-Sealing Tapes; Masking and Painter's Tapes; Strapping and Bundling TapesStrapping and Bundling Tapes (55.2%)Carton-Sealing Tapes (6.42% CAGR)
By End-user IndustryE-commerce; Food and Beverage; Retail; Other End-user IndustriesRetail (49.2%)E-commerce (6.47% CAGR)
By RegionAsia-Pacific; North America; Europe; South America; Middle-East and AfricaAsia-Pacific (41.6%)Asia-Pacific (41.6%)

Market Segmentation Overview

By Material Type

Sub-SegmentKey Trend
PlasticOriented polypropylene replaces PVC; recycled-content films qualify under plastic taxes
PaperRepulpable kraft backings with humidity-resistant coatings gain approvals

Plastic leads with a 67.4% share because polypropylene film delivers strength and clarity at the lowest cost per metre. Paper grows fastest at a 6.38% CAGR, since EU and Californian recyclability rules penalize film backings that contaminate corrugate recycling. Coating improvements that let paper tapes survive humid warehouses are removing the main technical objection buyers had.

By Adhesive Type

Sub-SegmentKey Trend
AcrylicWater-based grades meet solvent limits and bond to recycled fibre
Hot-MeltInstant tack keeps it standard on high-speed automated lines
Rubber-BasedStyrenic block copolymers and bio-based blends extend cold-chain reach
Other Adhesive TypesSilicone and specialty chemistries serve high-temperature niches

Acrylic holds 41.5% because water-based formulations comply with VOC rules and stick reliably to rough, recycled board. Rubber-Based adhesives grow fastest at a 6.19% CAGR, keeping tack below -20 °C where acrylics stiffen. Hot-Melt keeps its high-volume base on automated lines, where instant grab matters more than long-term ageing performance.

By Product Form

Sub-SegmentKey Trend
Carton-Sealing TapesNarrower rolls and machine-grade tolerances for automated parcel lines
Masking and Painter's TapesSteady demand from construction refinishing and surface protection
Strapping and Bundling TapesFilament and mono-oriented constructions secure palletized freight

Strapping and Bundling Tapes lead with 55.2%, as industrial shippers rely on reinforced constructions to stop load shift on appliance, steel, and export pallets. Carton-Sealing Tapes grow fastest at a 6.42% CAGR on rising parcel counts. Even with narrower roll widths cutting usage per seal, total demand keeps rising.

By End-user Industry

Sub-SegmentKey Trend
E-commerceGrocery, same-day, and quick-commerce orders multiply sealing events
Food and BeverageChilled and frozen chains require temperature-certified tapes
RetailBranded and tamper-evident rolls for store replenishment and pickup
Other End-user IndustriesElectronics, automotive, and pharmaceutical logistics buy specialty grades

Retail leads with a 49.2% share, because store replenishment, shelf preparation, and back-room boxing use more tape than parcel shipping in mature economies. E-commerce grows fastest at a 6.47% CAGR, as grocery and quick-commerce orders add sealing events per household. Food and Beverage buyers are shifting their spend toward tapes certified for cold-chain shipping.


Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.