Packaging Machinery Market (2026 - 2035)

ID: MRFR/PCM/0693-CR 111 Pages Snehal Singh Last Updated: September 18, 2026
Packaging Machinery Market Research Report Information By Machine-Type (Filling, Labeling, Form-Fill-Seal, Cartoning, Wrapping, Palletizing, Bottling Line, Others), By End-Use (Beverages, Food, Chemicals, Personal Care, Pharmaceuticals, Others) And By Region (North America, Europe, Asia-Pacific, And Rest Of The World) –Market Forecast Till 2035
Packaging Machinery Market
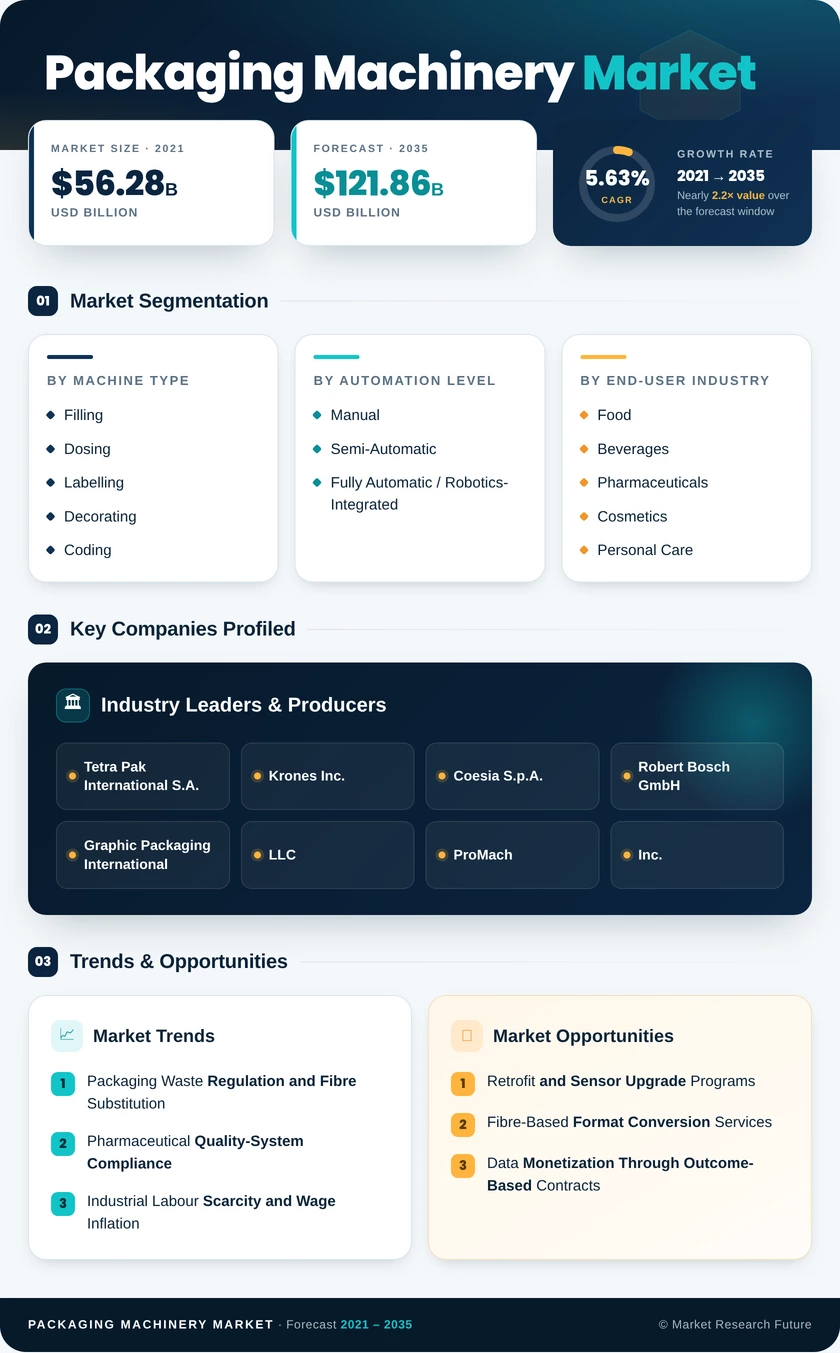
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.63%
2025 Market SizeUSD 69.42 Billion
2035 Market SizeUSD 121.86 Billion
Key Players
Tetra Pak International S.A.
Krones Inc.
Coesia S.p.A.
Robert Bosch GmbH
Graphic Packaging International, LLC
ProMach, Inc.
Opportunities
  • Retrofit and Sensor Upgrade Programs
  • Fibre-Based Format Conversion Services
  • Data Monetization Through Outcome-Based Contracts
  1. 1 Market Summary | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Machine Type | |
    2. 2.2 By Automation Level | |
    3. 2.3 By End-User Industry | |
    4. 2.4 By Technology Platform | |
    5. 2.5 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2024) | |
    2. 3.2 Base Year Assessment (2025) | |
    3. 3.3 Forecast Market Size (2026–2035) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Packaging Waste Regulation and Fibre Substitution | |
    2. 4.2 Pharmaceutical Quality-System Compliance | |
    3. 4.3 Industrial Labour Scarcity and Wage Inflation | |
    4. 4.4 SKU Proliferation and Rapid Changeover Demand | |
    5. 4.5 Emerging-Market Food Processing Capacity | |
    6. 4.6 Traceability and Serialization Mandates | |
    7. 4.7 Cold-Chain and Shelf-Life Extension Investment | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 High Capital Intensity and Financing Costs | |
    2. 5.2 Controls Engineering and Maintenance Skills Gap | |
    3. 5.3 Format Uncertainty Delaying Capex Decisions | |
    4. 5.4 Cybersecurity Exposure on Connected Lines | |
    5. 5.5 Fragmented Supplier Base and Integration Risk | |
  6. 6 Opportunities | |
    1. 6.1 Retrofit and Sensor Upgrade Programs | |
    2. 6.2 Fibre-Based Format Conversion Services | |
    3. 6.3 Data Monetization Through Outcome-Based Contracts | |
    4. 6.4 Africa and Gulf Industrial Localization | |
    5. 6.5 Pharmaceutical Small-Batch and Personalized Therapy Lines | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 United States | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 United Kingdom | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Russia | | |
      7. 7.2.7 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 Australia and New Zealand | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 Middle East and Africa | | |
      1. 7.4.1 Middle East | | |
      2. 7.4.2 United Arab Emirates | | |
      3. 7.4.3 Saudi Arabia | | |
      4. 7.4.4 Turkey | | |
      5. 7.4.5 Rest of Middle East | | |
      6. 7.4.6 Africa | | |
      7. 7.4.7 South Africa | | |
      8. 7.4.8 Nigeria | | |
      9. 7.4.9 Egypt | | |
      10. 7.4.10 Rest of Africa | |
    5. 7.5 South America | | |
      1. 7.5.1 Brazil | | |
      2. 7.5.2 Argentina | | |
      3. 7.5.3 Rest of South America | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Autonomous Line Operation | |
    2. 8.2 Servitization and Platform Economics | |
    3. 8.3 Energy Efficiency as a Purchase Criterion | |
    4. 8.4 Circularity Reporting and Machine Data | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Machine Type | | |
      1. 9.1.1 Filling and Dosing | | |
      2. 9.1.2 Labelling, Decorating, and Coding | | |
      3. 9.1.3 Case Handling | | |
      4. 9.1.4 Bottling Line | | |
      5. 9.1.5 Cartoning | | |
      6. 9.1.6 Palletizing and Depalletizing | | |
      7. 9.1.7 Wrapping and Bundling | | |
      8. 9.1.8 Blister / Thermoforming / Skin / Vacuum Packaging | | |
      9. 9.1.9 Other Machine Type | |
    2. 9.2 By Automation Level | | |
      1. 9.2.1 Manual | | |
      2. 9.2.2 Semi-Automatic | | |
      3. 9.2.3 Fully Automatic / Robotics-Integrated | |
    3. 9.3 By End-User Industry | | |
      1. 9.3.1 Food | | |
      2. 9.3.2 Beverages | | |
      3. 9.3.3 Pharmaceuticals | | |
      4. 9.3.4 Cosmetics and Personal Care | | |
      5. 9.3.5 Industrial Chemicals | | |
      6. 9.3.6 Other End-use Industry | |
    4. 9.4 By Technology Platform | | |
      1. 9.4.1 General Packaging (Conventional) | | |
      2. 9.4.2 Modified Atmosphere Packaging (MAP) | | |
      3. 9.4.3 Vacuum Packaging | | |
      4. 9.4.4 Aseptic Packaging Lines | | |
      5. 9.4.5 Intelligent / Connected (QR / RFID-Enabled) Packaging Lines | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | |
  11. 11 Recent News and Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions | | LIST OF TABLES | |
  15. TABLE 1 Global Packaging Machinery Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Global Packaging Machinery Market — Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 | |
  19. TABLE 5 Global Packaging Machinery Market Size, by Region, 2021–2035 (USD Billion) | |
  20. TABLE 6 North America Packaging Machinery Market Size, by Country, 2021–2035 (USD Billion) | |
  21. TABLE 7 Europe Packaging Machinery Market Size, by Country, 2021–2035 (USD Billion) | |
  22. TABLE 8 Asia-Pacific Packaging Machinery Market Size, by Country, 2021–2035 (USD Billion) | |
  23. TABLE 9 Middle East and Africa Packaging Machinery Market Size, by Country, 2021–2035 (USD Billion) | |
  24. TABLE 10 South America Packaging Machinery Market Size, by Country, 2021–2035 (USD Billion) | |
  25. TABLE 11 Global Packaging Machinery Market Size, by Machine Type, 2021–2035 (USD Billion) | |
  26. TABLE 12 Global Packaging Machinery Market Size, by Automation Level, 2021–2035 (USD Billion) | |
  27. TABLE 13 Global Packaging Machinery Market Size, by End-User Industry, 2021–2035 (USD Billion) | |
  28. TABLE 14 Global Packaging Machinery Market Size, by Technology Platform, 2021–2035 (USD Billion) | |
  29. TABLE 15 North America Packaging Machinery Market Size, by Machine Type, 2021–2035 (USD Billion) | |
  30. TABLE 16 North America Packaging Machinery Market Size, by Automation Level, 2021–2035 (USD Billion) | |
  31. TABLE 17 North America Packaging Machinery Market Size, by End-User Industry, 2021–2035 (USD Billion) | |
  32. TABLE 18 North America Packaging Machinery Market Size, by Technology Platform, 2021–2035 (USD Billion) | |
  33. TABLE 19 Europe Packaging Machinery Market Size, by Machine Type, 2021–2035 (USD Billion) | |
  34. TABLE 20 Europe Packaging Machinery Market Size, by Automation Level, 2021–2035 (USD Billion) | |
  35. TABLE 21 Europe Packaging Machinery Market Size, by End-User Industry, 2021–2035 (USD Billion) | |
  36. TABLE 22 Europe Packaging Machinery Market Size, by Technology Platform, 2021–2035 (USD Billion) | |
  37. TABLE 23 Asia-Pacific Packaging Machinery Market Size, by Machine Type, 2021–2035 (USD Billion) | |
  38. TABLE 24 Asia-Pacific Packaging Machinery Market Size, by Automation Level, 2021–2035 (USD Billion) | |
  39. TABLE 25 Asia-Pacific Packaging Machinery Market Size, by End-User Industry, 2021–2035 (USD Billion) | |
  40. TABLE 26 Asia-Pacific Packaging Machinery Market Size, by Technology Platform, 2021–2035 (USD Billion) | |
  41. TABLE 27 Middle East and Africa Packaging Machinery Market Size, by Machine Type, 2021–2035 (USD Billion) | |
  42. TABLE 28 Middle East and Africa Packaging Machinery Market Size, by Automation Level, 2021–2035 (USD Billion) | |
  43. TABLE 29 Middle East and Africa Packaging Machinery Market Size, by End-User Industry, 2021–2035 (USD Billion) | |
  44. TABLE 30 Middle East and Africa Packaging Machinery Market Size, by Technology Platform, 2021–2035 (USD Billion) | |
  45. TABLE 31 South America Packaging Machinery Market Size, by Machine Type, 2021–2035 (USD Billion) | |
  46. TABLE 32 South America Packaging Machinery Market Size, by Automation Level, 2021–2035 (USD Billion) | |
  47. TABLE 33 South America Packaging Machinery Market Size, by End-User Industry, 2021–2035 (USD Billion) | |
  48. TABLE 34 South America Packaging Machinery Market Size, by Technology Platform, 2021–2035 (USD Billion) | |
  49. TABLE 35 United States Packaging Machinery Market Size, by Machine Type, 2021–2035 (USD Billion) | |
  50. TABLE 36 China Packaging Machinery Market Size, by Machine Type, 2021–2035 (USD Billion) | |
  51. TABLE 37 Germany Packaging Machinery Market Size, by Machine Type, 2021–2035 (USD Billion) | |
  52. TABLE 38 India Packaging Machinery Market Size, by End-User Industry, 2021–2035 (USD Billion) | |
  53. TABLE 39 Competitive Benchmarking Matrix — Global Packaging Machinery Market, 2026 | |
  54. TABLE 40 Company Profiles — Key Players, Global Packaging Machinery Market | |
  55. TABLE 41 Recent Developments and Strategic Announcements, 2023–2025 | |
  56. TABLE 42 Report Scope and Methodology Summary | |
  57. TABLE 43 Detailed Sources and Citations Index | | LIST OF FIGURES | |
  58. FIGURE 1 Global Packaging Machinery Market — Market Dynamics Overview | |
  59. FIGURE 2 Industry Value Chain Analysis | |
  60. FIGURE 3 Porter's Five Forces Analysis | |
  61. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Billion) | |
  62. FIGURE 5 Year-over-Year Growth Trend, 2022–2035 (%) | |
  63. FIGURE 6 Market Share by Machine Type, 2025 vs 2035 | |
  64. FIGURE 7 Market Share by Automation Level, 2025 vs 2035 | |
  65. FIGURE 8 Market Share by End-User Industry, 2025 vs 2035 | |
  66. FIGURE 9 Market Share by Technology Platform, 2025 vs 2035 | |
  67. FIGURE 10 Regional Market Share Distribution, 2025 | |
  68. FIGURE 11 Regional CAGR Comparison, 2026–2035 | |
  69. FIGURE 12 North America Country-Level Share Distribution, 2025 | |
  70. FIGURE 13 Europe Country-Level Share Distribution, 2025 | |
  71. FIGURE 14 Asia-Pacific Country-Level Share Distribution, 2025 | |
  72. FIGURE 15 Middle East and Africa Country-Level Share Distribution, 2025 | |
  73. FIGURE 16 South America Country-Level Share Distribution, 2025 | |
  74. FIGURE 17 Competitive Landscape — Estimated Revenue Share Bands, 2026 | |
  75. FIGURE 18 Strategic Positioning Matrix — Key Suppliers | |
  76. FIGURE 19 Driver and Restraint Impact Waterfall, 2026–2035

Segmentation Quick Reference

Dimension Sub-Segments Dominant Segment Fastest Growing Segment
By Machine Type Filling and Dosing; Labelling, Decorating, and Coding; Case Handling; Bottling Line; Cartoning; Palletizing and Depalletizing; Wrapping and Bundling; Blister / Thermoforming / Skin / Vacuum Packaging; Other Machine Type Filling and Dosing (21.6% share, 2025) Cartoning (8.11% CAGR)
By Automation Level Manual; Semi-Automatic; Fully Automatic / Robotics-Integrated Fully Automatic / Robotics-Integrated (58.9% share, 2025) Semi-Automatic (4.02% CAGR)
By End-User Industry Food; Beverages; Pharmaceuticals; Cosmetics and Personal Care; Industrial Chemicals; Other End-use Industry Food (27.4% share, 2025) Pharmaceuticals (6.95% CAGR)
By Technology Platform General Packaging (Conventional); Modified Atmosphere Packaging (MAP); Vacuum Packaging; Aseptic Packaging Lines; Intelligent / Connected (QR / RFID-Enabled) Packaging Lines General Packaging (Conventional) (48.2% share, 2025) Intelligent / Connected (QR / RFID-Enabled) Packaging Lines (9.12% CAGR)


Market Segmentation Overview

By Machine Type

Sub-Segment Key Trend
Filling and Dosing Multi-product heads and clean-in-place designs extend line flexibility
Labelling, Decorating, and Coding Inline verification cameras become standard as two-dimensional codes replace linear barcodes
Case Handling Retail-ready formats drive demand for tool-free case erectors
Bottling Line Lightweight PET handling requires gentler conveying and gripping systems
Cartoning Servo blank feeders accommodate recycled board dimensional variance
Palletizing and Depalletizing Vision-guided pick heads enable mixed-SKU layer building
Wrapping and Bundling Variable-format film control reduces material consumption per pallet
Blister / Thermoforming / Skin / Vacuum Packaging Mono-material barrier films demand tighter forming temperature control
Other Machine Type Custom tooling serves niche formats underserved by standard platforms


Filling and Dosing anchors this dimension because it appears on nearly every liquid, powder, and paste line regardless of what happens downstream, sustaining the 21.6% share reported in Section 9. Cartoning grows fastest at 8.11% CAGR as European recyclability rules push brand owners from film to fibre, and recycled board's dimensional variability is precisely what servo blank feeders exist to absorb. Palletizing and Depalletizing carries the labour-substitution story, since end-of-line stacking is the function buyers automate first when wage pressure builds.

By Automation Level

Sub-Segment Key Trend
Manual Persists in artisanal, low-volume, and highly variable production
Semi-Automatic Enables staged capital deployment for mid-sized processors
Fully Automatic / Robotics-Integrated Predictive maintenance and no-code recipe tools lower operating skill thresholds


Fully Automatic / Robotics-Integrated configurations hold 58.9% of revenue because hygiene requirements in dairy and pharmaceutical work rule out open manual handling, and because labour payback periods have compressed below two years in high-wage economies. Semi-Automatic lines post the fastest growth at 4.02% CAGR, driven by Asia-Pacific and South American processors who upgrade one module at a time rather than committing to a full line replacement. Manual stations are not disappearing; they simply concentrate where batch variability defeats fixed automation economics.

By End-User Industry

Sub-Segment Key Trend
Food Frequent recipe and pack changes drive rapid-changeover specifications
Beverages Premium water and functional drinks sustain bottling line investment
Pharmaceuticals Quality-system rules push validated, instrumented fill-finish equipment
Cosmetics and Personal Care Prestige brands automate decorating and precision filling
Industrial Chemicals Explosion-proof and corrosion-resistant designs command specialist suppliers
Other End-use Industry Household and pet care products adopt retail-ready secondary packing


Food leads with 27.4% of 2025 revenue on the strength of its installed base and the pace at which recipes, promotions, and pack sizes turn over, which forces replacement well before mechanical end of life. Pharmaceuticals expands fastest at 6.95% CAGR as biologics and prefilled-syringe capacity scales under the FDA quality-system framework, and buyers there pay premiums for validation support rather than raw speed. Beverages remain the steadier counterweight, tied to bottling capacity rather than regulatory deadlines.

By Technology Platform

Sub-Segment Key Trend
General Packaging (Conventional) Remains default where product stability requires no atmosphere control
Modified Atmosphere Packaging (MAP) Retailer residual-oxygen specifications drive gas-flush accuracy requirements
Vacuum Packaging Chilled protein and cheese exports depend on extended shelf life
Aseptic Packaging Lines Ambient distribution justifies high capital outlay for nutraceuticals and sterile fluids
Intelligent / Connected (QR / RFID-Enabled) Packaging Lines Inline scanners and cloud gateways capture item-level data without slowing throughput


General Packaging (Conventional) retains 48.2% of revenue because the majority of SKUs are shelf-stable enough that buyers see no reason to pay for atmosphere control. Intelligent / Connected (QR / RFID-Enabled) Packaging Lines grow fastest at 9.12% CAGR, tracking the retail migration to two-dimensional barcode scanning and brand-owner demand for item-level supply-chain visibility. Modified Atmosphere Packaging (MAP) sits between the two, sustained by retailer shelf-life specifications that increasingly determine whether a product gets listed at all.



Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.