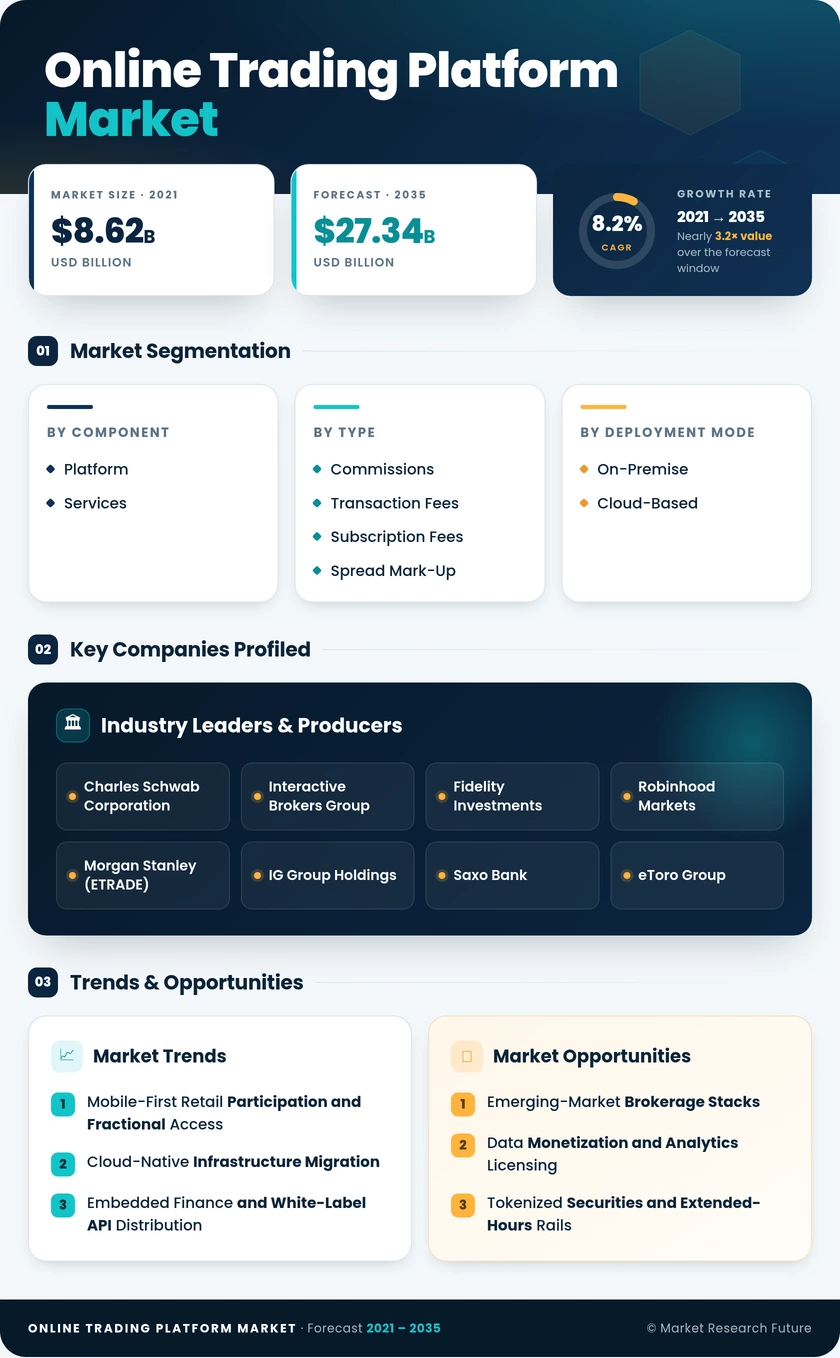
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Component | Platform, Services | Platform (72.4% revenue share, 2025) | Services (10.5% CAGR, 2026–2035) |
| By Type | Commissions, Transaction Fees, Subscription Fees, Spread Mark-Up | Transaction Fees (55.8% revenue share, 2025) | Subscription Fees (9.4% CAGR, 2026–2035) |
| By Deployment Mode | On-Premise, Cloud-Based | Cloud-Based (67.8% revenue share, 2025) | Cloud-Based (67.8% revenue share, 2025 — also fastest) |
| By Application | Institutional Investors, Retail Investors | Retail Investors (65.0% revenue share, 2025) | Retail Investors (65.0% revenue share, 2025 — also fastest) |
Market Segmentation Overview
By Component
| Sub-Segment | Key Trend |
| Platform | Execution quality converges; differentiation shifts to interface and ecosystem breadth |
| Services | Managed portfolios, tax engines, and API licensing expand recurring revenue mix |
Platform holds the larger revenue base because order routing and account infrastructure remain non-negotiable purchases for any broker. Services grow faster, however, since advisory subscriptions and licensing carry pricing power that commoditized execution has lost to fee competition. Buyers now evaluate vendors on the depth of the services layer sitting above the execution rail, not on latency alone.
By Type
| Sub-Segment | Key Trend |
| Commissions | Retained mainly where regulators mandate explicit per-trade pricing |
| Transaction Fees | Costs relocated into spreads, contract charges, and routing rebates |
| Subscription Fees | Tiered analytics and data bundles smooth revenue across quiet quarters |
| Spread Mark-Up | Crypto and foreign-exchange conversion margins widen during volatility |
Transaction Fees lead this dimension because zero-commission positioning relocated charges rather than removing them, leaving spreads and rebates as the primary monetization route. Subscription Fees expand fastest as active traders accept predictable monthly pricing for Level II data and advanced charting. Commissions continue shrinking in relative terms wherever regulators permit implicit charging, while Spread Mark-Up revenue remains the most cyclical line in the mix.
By Deployment Mode
| Sub-Segment | Key Trend |
| On-Premise | Sustained by mainframe dependencies and long capital expenditure cycles |
| Cloud-Based | Elastic capacity absorbs margin, risk, and pricing workloads during volume spikes |
Cloud-Based deployments both dominate and grow fastest, because burst compute for real-time margin and risk calculation cannot be economically provisioned on fixed hardware. On-Premise installations persist among institutional brokers whose core systems predate modern virtualization and whose replacement budgets follow multi-year cycles. Supervisory acceptance of public-cloud hosting for regulated workloads removed the last procurement objection, leaving migration a question of timing rather than direction.
By Application
| Sub-Segment | Key Trend |
| Institutional Investors | Demand for implementation-shortfall algorithms and granular post-trade analytics |
| Retail Investors | Fractional access, mobile onboarding, and social features drive trade frequency |
Retail Investors dominate revenue and set the growth pace, since low-minimum onboarding converted large populations into frequent, small-ticket participants across every major region. Institutional Investors contribute a smaller share but fund the execution research and colocation infrastructure that later becomes standard for retail-facing venues. Serving both requires architecture that handles one-dollar fractional orders and block execution on the same rail — a design constraint few vendors satisfy well.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA