Non woven Fabric Market (2026 - 2035)

ID: MRFR/CnM/1230-HCR 132 Pages Chitranshi Jaiswal Last Updated: September 18, 2026
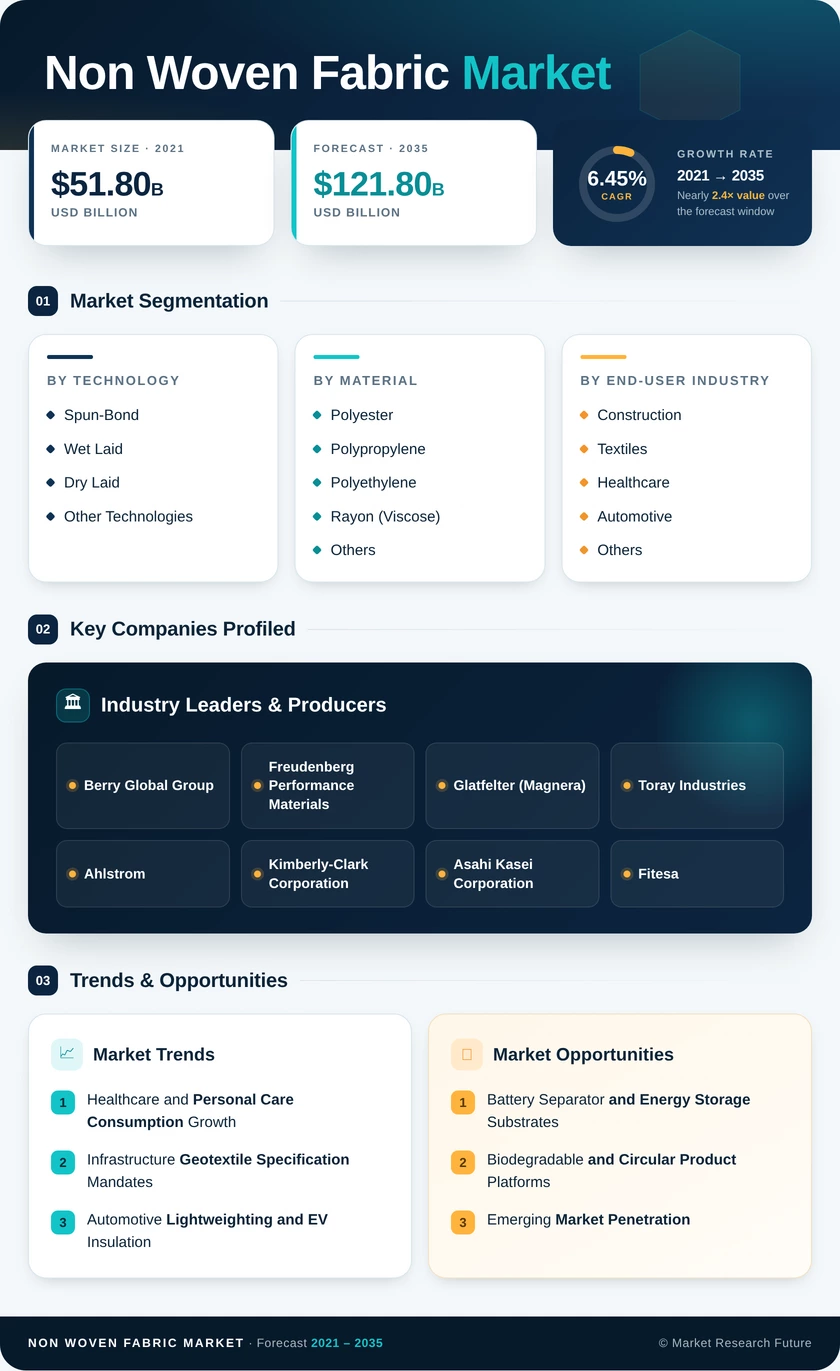
Non-woven Fabric Market Research Report Information By Technology (Spun-Bond, Dry Laid, Wet Laid, and Other Technologies), By Material (Polypropylene, Polyester, Polyethylene, Rayon (Viscose), and Others), and By End-User Industry (Healthcare, Construction, Textiles, Automotive, and Others) – Forecast Till 2035.
Non woven Fabric Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.45%
2025 Market SizeUSD 65.20 Billion
2035 Market SizeUSD 121.80 Billion
Key Players
Berry Global Group
Freudenberg Performance Materials
Glatfelter
Toray Industries
Ahlstrom
Kimberly-Clark Corporation
Opportunities
  • Battery Separator and Energy Storage Substrates
  • Biodegradable and Circular Product Platforms
  • Emerging Market Penetration
  1. 1 Market Overview | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Market Summary & Key Report Takeaways | |
    1. 2.1 Takeaways by Technology | |
    2. 2.2 Takeaways by Sector | |
    3. 2.3 Takeaways by Geography | |
  3. 3 Global Market Size & Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Current & Forecast Market Size (2026–2035) | |
    3. 3.3 Market Size by Revenue (USD Billion) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Market Dynamics — Driver Impact Analysis | |
    1. 4.1 Healthcare and Personal Care Consumption Growth | |
    2. 4.2 Infrastructure Geotextile Specification Mandates | |
    3. 4.3 Automotive Lightweighting and EV Insulation | |
    4. 4.4 Air and Liquid Filtration Standard Tightening | |
    5. 4.5 Spun-Bond Capacity Investment Cycle | |
    6. 4.6 Recycled and Bio-Based Feedstock Adoption | |
    7. 4.7 Agricultural Crop-Cover Penetration | |
  5. 5 Market Dynamics — Restraints Impact Analysis | |
    1. 5.1 Propylene Feedstock Price Volatility | |
    2. 5.2 Single-Use Plastic and Microplastic Regulation | |
    3. 5.3 Post-Pandemic Protective Capacity Overhang | |
    4. 5.4 End-of-Life and Recycling Infrastructure Gaps | |
    5. 5.5 Energy and Freight Cost Inflation | |
  6. 6 Market Opportunity Analysis | |
    1. 6.1 Battery Separator and Energy Storage Substrates | |
    2. 6.2 Biodegradable and Circular Product Platforms | |
    3. 6.3 Emerging Market Penetration | |
    4. 6.4 Roll-Level Traceability and Data-Enabled Service Models | |
    5. 6.5 Nanofiber Wound Care and Advanced Medical Applications | |
    6. 6.6 Industry Value Chain Analysis | |
    7. 6.7 Porter's Five Forces Analysis | |
  7. 7 Regional Market Share & Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of Middle East & Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Process Automation and Closed-Loop Line Control | |
    2. 8.2 Electrification and Battery Supply Chain Pull | |
    3. 8.3 Circularity Reporting and Compliance Economics | |
    4. 8.4 Capacity Rationalisation and Regional Cost Divergence | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Technology | | |
      1. 9.1.1 Spun-Bond | | |
      2. 9.1.2 Wet Laid | | |
      3. 9.1.3 Dry Laid | | |
      4. 9.1.4 Other Technologies | |
    2. 9.2 By Material | | |
      1. 9.2.1 Polyester | | |
      2. 9.2.2 Polypropylene | | |
      3. 9.2.3 Polyethylene | | |
      4. 9.2.4 Rayon (Viscose) | | |
      5. 9.2.5 Others | |
    3. 9.3 By End-User Industry | | |
      1. 9.3.1 Construction | | |
      2. 9.3.2 Textiles | | |
      3. 9.3.3 Healthcare | | |
      4. 9.3.4 Automotive | | |
      5. 9.3.5 Others | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 Berry Global Group | | |
      2. 10.3.2 Freudenberg Performance Materials | | |
      3. 10.3.3 Glatfelter (Magnera) | | |
      4. 10.3.4 Toray Industries | | |
      5. 10.3.5 Ahlstrom | | |
      6. 10.3.6 Kimberly-Clark Corporation | | |
      7. 10.3.7 Asahi Kasei Corporation | | |
      8. 10.3.8 Fitesa | | |
      9. 10.3.9 Johns Manville | | |
      10. 10.3.10 UNIFI | | |
      11. 10.3.11 Suominen Corporation | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope & Methodology | |
    1. 12.1 Study Period & Base Year | |
    2. 12.2 Data Sources & Estimation Framework | |
    3. 12.3 Abbreviations | |
  13. 13 Detailed Sources & Citations | |
  14. 14 Frequently Asked Questions | | LIST OF TABLES | |
  15. TABLE 1 Global Non Woven Fabric Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Global Non Woven Fabric Market – Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 | |
  19. TABLE 5 Global Non Woven Fabric Market Size, by Region, 2021–2035 (USD Billion) | |
  20. TABLE 6 North America Market Size, by Country, 2021–2035 (USD Billion) | |
  21. TABLE 7 Europe Market Size, by Country, 2021–2035 (USD Billion) | |
  22. TABLE 8 Asia-Pacific Market Size, by Country, 2021–2035 (USD Billion) | |
  23. TABLE 9 South America Market Size, by Country, 2021–2035 (USD Billion) | |
  24. TABLE 10 Middle East & Africa Market Size, by Country, 2021–2035 (USD Billion) | |
  25. TABLE 11 Global Market Size, by Technology, 2021–2035 (USD Billion) | |
  26. TABLE 12 Global Market Size, by Material, 2021–2035 (USD Billion) | |
  27. TABLE 13 Global Market Size, by End-User Industry, 2021–2035 (USD Billion) | |
  28. TABLE 14 North America Market Size, by Technology, 2021–2035 (USD Billion) | |
  29. TABLE 15 Europe Market Size, by Material, 2021–2035 (USD Billion) | |
  30. TABLE 16 Asia-Pacific Market Size, by End-User Industry, 2021–2035 (USD Billion) | |
  31. TABLE 17 Competitive Benchmarking Matrix, 2026 | |
  32. TABLE 18 Company Profiles – Key Players | |
  33. TABLE 19 Recent Developments & Strategic Announcements, 2023–2025 | |
  34. TABLE 20 Report Scope & Methodology Summary | |
  35. TABLE 21 Detailed Sources & Citations Index | | LIST OF FIGURES | |
  36. FIGURE 1 Market Dynamics Overview – Drivers, Restraints and Opportunities | |
  37. FIGURE 2 Industry Value Chain Analysis | |
  38. FIGURE 3 Porter's Five Forces Assessment | |
  39. FIGURE 4 Global Market Size Trend and Forecast, 2021–2035 (USD Billion) | |
  40. FIGURE 5 Year-over-Year Growth Trajectory, 2022–2035 | |
  41. FIGURE 6 Market Share by Technology, 2025 vs 2035 | |
  42. FIGURE 7 Market Share by Material, 2025 vs 2035 | |
  43. FIGURE 8 Market Share by End-User Industry, 2025 | |
  44. FIGURE 9 Regional Market Share Distribution, 2025 | |
  45. FIGURE 10 Regional CAGR Comparison, 2026–2035 | |
  46. FIGURE 11 Country-Level Growth Heat Map | |
  47. FIGURE 12 Competitive Positioning Matrix – Scale vs Specification Depth | |
  48. FIGURE 13 Top Player Revenue Share Ranges, 2026 | |
  49. FIGURE 14 Feedstock Cost Sensitivity Analysis

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By TechnologySpun-Bond, Wet Laid, Dry Laid, Other TechnologiesSpun-BondOther Technologies
By MaterialPolyester, Polypropylene, Polyethylene, Rayon (Viscose), OthersPolypropyleneRayon (Viscose)
By End-User IndustryConstruction, Textiles, Healthcare, Automotive, OthersHealthcareConstruction
By GeographyAsia-Pacific, North America, Europe, South America, Middle East & AfricaAsia-PacificAsia-Pacific


Market Segmentation Overview

By Technology

Sub-SegmentKey Trend
Spun-BondMulti-beam lines lowering basis weight while holding tensile specification.
Wet LaidMigration toward precision filtration and separator carrier grades
Dry LaidNeedle-punch loft retained for automotive trim and durable applications.
Other TechnologiesSpun-lace softness and electrospun fineness unlocking premium niches


Technology choice increasingly determines which end-uses a producer can access at all. Spun-bond economics dominate volume categories, but the fastest value creation sits in formats that commodity extrusion cannot replicate, particularly where fibre diameter or pore-size control drives performance.

By Material

Sub-SegmentKey Trend
PolyesterRecycled bottle-to-fibre streams supporting certified content claims
PolypropyleneCost leadership maintained despite propylene feedstock volatility.
PolyethyleneSteady demand in backsheet and laminate constructions
Rayon (Viscose)Regulatory-driven substitution into wipe and rinse-off categories
OthersLyocell, bicomponent and natural blends entering mainstream specifications


Material substitution is now regulation-led rather than price-led. European labelling and microplastic rules are shifting formulations toward cellulosic inputs even where those inputs carry a cost penalty, while recycled polyester gains share on the strength of verifiable traceability.

By End-User Industry

Sub-SegmentKey Trend
ConstructionGeotextile separation written into public specification standards
TextilesInterlinings and furnishing substrates competing against woven alternatives.
HealthcareAbsorbent hygiene penetration rising across South Asia and Africa.
AutomotiveBattery-pack thermal barriers adding content per vehicle
OthersAgricultural covers, packaging and industrial wiping applications


End-use concentration keeps healthcare at the centre of volume planning, yet the incremental growth story is broader. Construction offers specification-protected stability, automotive delivers value per tonne, and agricultural covers provide optionality in markets where subsidy support is expanding.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.