Microbial Fuel Cell Market (2026 - 2035)

ID: MRFR/EnP/5728-HCR 111 Pages Anshula Mandaokar Last Updated: September 15, 2026
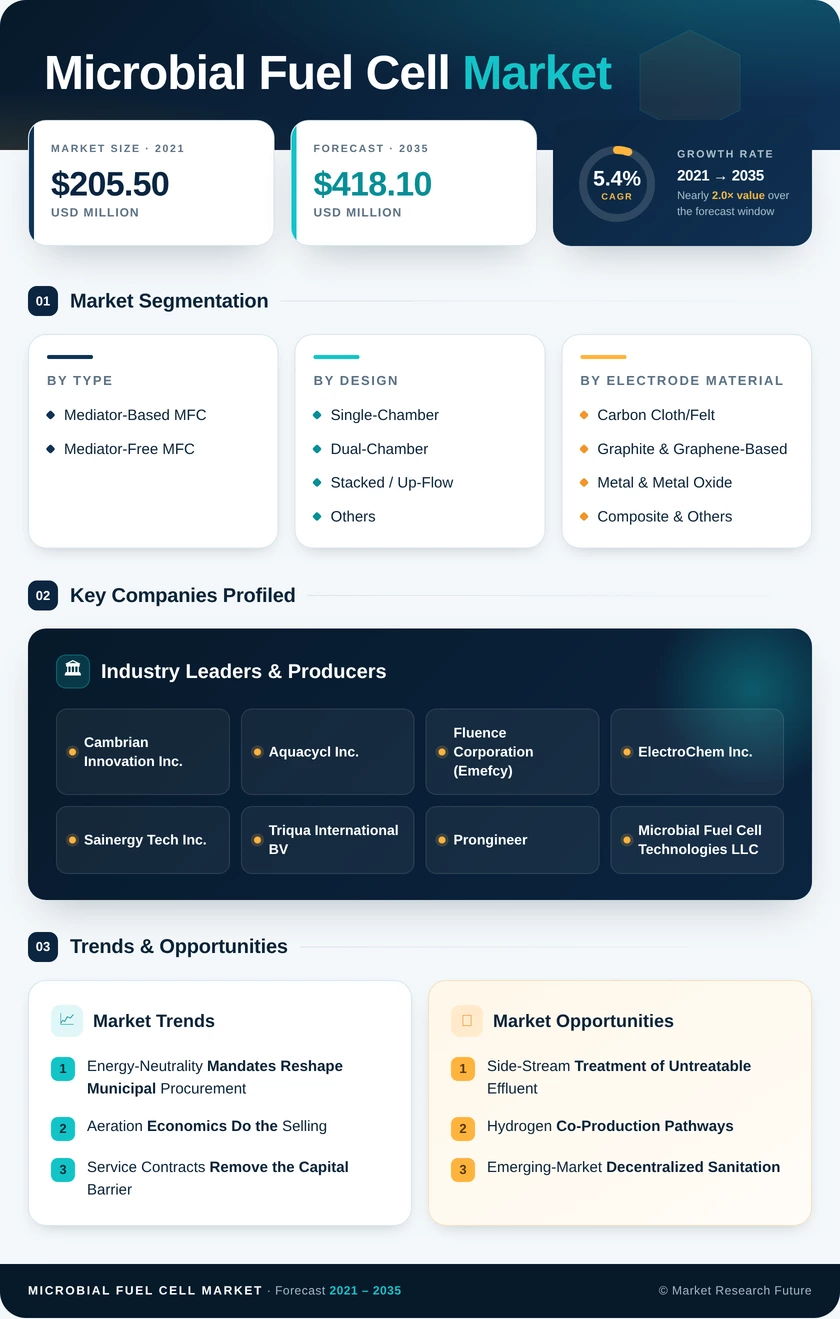
Microbial Fuel Cell Market Research Report By Type (Mediator-Based MFC, Mediator-Free MFC), By Design (Single-Chamber, Dual-Chamber, Stacked / Up-Flow, Others), By Electrode Material (Carbon Cloth/Felt, Graphite & Graphene-Based, Metal & Metal Oxide, Composite & Others), By Substrate Source (Municipal Wastewater / Industrial Effluents, Agricultural & Food Waste, Sediment & Soil Organics, Synthetic & Other Media), By Application (Wastewater Treatment & Energy Recovery, Biosensing & Environmental Monitoring, Remote & Off-Grid Power, Hydrogen & Chemical Recovery), By End-User (Industrial, Research Institutions, Municipal Utilities, Defense & Remote Operations) - Forecast to 2035
Microbial Fuel Cell Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.4%
2025 Market SizeUSD 247.1 Million
2035 Market SizeUSD 418.1 Million
Key Players
Cambrian Innovation Inc.
Aquacycl Inc.
Fluence Corporation
ElectroChem Inc.
Sainergy Tech Inc.
Triqua International BV
Opportunities
  • Side-Stream Treatment of Untreatable Effluent
  • Hydrogen Co-Production Pathways
  • Emerging-Market Decentralized Sanitation
  1. 1 Market Overview | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Market Summary & Key Takeaways | |
  3. 3 Market Size & Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Current & Forecast Market Size (2026–2035) | |
    3. 3.3 Market Size by Revenue (USD Million) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Market Dynamics — Drivers | |
    1. 4.1 Energy-Neutrality Mandates for Treatment Plants | |
    2. 4.2 Aeration Cost Escape for High-Strength Effluent | |
    3. 4.3 Corporate Water and Emissions Targets | |
    4. 4.4 Industrial Discharge Enforcement in Asia | |
    5. 4.5 Wastewater-as-a-Service Financing Models | |
    6. 4.6 Electrode and Catalyst Cost Reduction | |
    7. 4.7 Off-Grid and Remote Sensing Power Demand | |
  5. 5 Market Dynamics — Restraints | |
    1. 5.1 Low Volumetric Power Density | |
    2. 5.2 Capital Cost per Unit of Treated Flow | |
    3. 5.3 Anaerobic Digestion as Entrenched Incumbent | |
    4. 5.4 Biofilm Instability and Start-Up Variability | |
    5. 5.5 Absence of Standardized Performance Testing | |
  6. 6 Market Opportunity Analysis | |
    1. 6.1 Side-Stream Treatment of Untreatable Effluent | |
    2. 6.2 Hydrogen Co-Production Pathways | |
    3. 6.3 Emerging-Market Decentralized Sanitation | |
    4. 6.4 Data Monetization Through Treatment Analytics | |
    5. 6.5 Defense and Remote Instrumentation Power | |
    6. 6.6 Industry Value Chain Analysis | |
    7. 6.7 Porter's Five Forces Analysis | |
  7. 7 Regional Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 United States | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 United Kingdom | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of Middle East & Africa | |
  8. 8 Future Outlook & Strategic Recommendations (2026–2035) | |
    1. 8.1 Autonomous Reactor Operation | |
    2. 8.2 Treatment-as-a-Service Platform Economics | |
    3. 8.3 Circular Water and the Energy Balance | |
    4. 8.4 Emissions Accounting and Methane Liability | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Type | | |
      1. 9.1.1 Mediator-Based MFC | | |
      2. 9.1.2 Mediator-Free MFC | |
    2. 9.2 By Design | | |
      1. 9.2.1 Single-Chamber | | |
      2. 9.2.2 Dual-Chamber | | |
      3. 9.2.3 Stacked / Up-Flow | | |
      4. 9.2.4 Others | |
    3. 9.3 By Electrode Material | | |
      1. 9.3.1 Carbon Cloth/Felt | | |
      2. 9.3.2 Graphite & Graphene-Based | | |
      3. 9.3.3 Metal & Metal Oxide | | |
      4. 9.3.4 Composite & Others | |
    4. 9.4 By Substrate Source | | |
      1. 9.4.1 Municipal Wastewater / Industrial Effluents | | |
      2. 9.4.2 Agricultural & Food Waste | | |
      3. 9.4.3 Sediment & Soil Organics | | |
      4. 9.4.4 Synthetic & Other Media | |
    5. 9.5 By Application | | |
      1. 9.5.1 Wastewater Treatment & Energy Recovery | | |
      2. 9.5.2 Biosensing & Environmental Monitoring | | |
      3. 9.5.3 Remote & Off-Grid Power | | |
      4. 9.5.4 Hydrogen & Chemical Recovery | |
    6. 9.6 By End-User | | |
      1. 9.6.1 Industrial | | |
      2. 9.6.2 Research Institutions | | |
      3. 9.6.3 Municipal Utilities | | |
      4. 9.6.4 Defense & Remote Operations | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Share Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 Cambrian Innovation Inc. | | |
      2. 10.3.2 Aquacycl Inc. | | |
      3. 10.3.3 Fluence Corporation (Emefcy) | | |
      4. 10.3.4 ElectroChem Inc. | | |
      5. 10.3.5 Sainergy Tech Inc. | | |
      6. 10.3.6 Triqua International BV | | |
      7. 10.3.7 Prongineer | | |
      8. 10.3.8 Microbial Fuel Cell Technologies LLC | | |
      9. 10.3.9 Angstrom Advanced Inc. | | |
      10. 10.3.10 Plant-e BV | | |
      11. 10.3.11 Protonex / Remote Power Specialists | |
  11. 11 Recent Developments & News | |
  12. 12 Report Scope & Methodology | |
    1. 12.1 Study Period & Base Year | |
    2. 12.2 Data Sources & Citations | |
    3. 12.3 Abbreviations | |
  13. 13 Detailed Sources & Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Global Microbial Fuel Cell Market Size & Forecast, by Revenue (USD Million), 2021–2035 | |
  16. TABLE 2 Global Microbial Fuel Cell Market — Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis — Global Microbial Fuel Cell Market, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis — Global Microbial Fuel Cell Market, 2026–2035 | |
  19. TABLE 5 Global Market Size, by Type, 2021–2035 (USD Million) | |
  20. TABLE 6 Global Market Size, by Design, 2021–2035 (USD Million) | |
  21. TABLE 7 Global Market Size, by Electrode Material, 2021–2035 (USD Million) | |
  22. TABLE 8 Global Market Size, by Substrate Source, 2021–2035 (USD Million) | |
  23. TABLE 9 Global Market Size, by Application, 2021–2035 (USD Million) | |
  24. TABLE 10 Global Market Size, by End-User, 2021–2035 (USD Million) | |
  25. TABLE 11 Global Market Size, by Region, 2021–2035 (USD Million) | |
  26. TABLE 12 North America Market Size, by Country, 2021–2035 (USD Million) | |
  27. TABLE 13 Europe Market Size, by Country, 2021–2035 (USD Million) | |
  28. TABLE 14 Asia-Pacific Market Size, by Country, 2021–2035 (USD Million) | |
  29. TABLE 15 South America Market Size, by Country, 2021–2035 (USD Million) | |
  30. TABLE 16 Middle East & Africa Market Size, by Country, 2021–2035 (USD Million) | |
  31. TABLE 17 North America Market Size, by Type and Design, 2021–2035 (USD Million) | |
  32. TABLE 18 North America Market Size, by Application and End-User, 2021–2035 (USD Million) | |
  33. TABLE 19 Europe Market Size, by Type and Design, 2021–2035 (USD Million) | |
  34. TABLE 20 Europe Market Size, by Application and End-User, 2021–2035 (USD Million) | |
  35. TABLE 21 Asia-Pacific Market Size, by Type and Design, 2021–2035 (USD Million) | |
  36. TABLE 22 Asia-Pacific Market Size, by Application and End-User, 2021–2035 (USD Million) | |
  37. TABLE 23 South America Market Size, by Application and End-User, 2021–2035 (USD Million) | |
  38. TABLE 24 Middle East & Africa Market Size, by Application and End-User, 2021–2035 (USD Million) | |
  39. TABLE 25 Competitive Benchmarking Matrix — Global Microbial Fuel Cell Market, 2026 | |
  40. TABLE 26 Company Profiles — Key Players, Global Microbial Fuel Cell Market | |
  41. TABLE 27 Recent Developments & Strategic Announcements, 2023–2025 | |
  42. TABLE 28 Report Scope & Methodology Summary | |
  43. TABLE 29 Detailed Sources & Citations Index | |
  44. TABLE 30 Segmentation Quick Reference — Dominant and Fastest Growing Segments | | LIST OF FIGURES | |
  45. FIGURE 1 Global Microbial Fuel Cell Market — Market Dynamics Snapshot | |
  46. FIGURE 2 Industry Value Chain Analysis | |
  47. FIGURE 3 Porter's Five Forces Analysis | |
  48. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Million) | |
  49. FIGURE 5 Year-over-Year Growth Trajectory, 2022–2035 | |
  50. FIGURE 6 Market Share by Type, 2025 vs 2035 | |
  51. FIGURE 7 Market Share by Design, 2025 vs 2035 | |
  52. FIGURE 8 Market Share by Electrode Material, 2025 | |
  53. FIGURE 9 Market Share by Substrate Source, 2025 | |
  54. FIGURE 10 Market Share by Application, 2025 vs 2035 | |
  55. FIGURE 11 Market Share by End-User, 2025 | |
  56. FIGURE 12 Regional Market Share Distribution, 2025 | |
  57. FIGURE 13 Regional CAGR Comparison, 2026–2035 | |
  58. FIGURE 14 North America Country-Level Share, 2025 | |
  59. FIGURE 15 Europe Country-Level Share, 2025 | |
  60. FIGURE 16 Asia-Pacific Country-Level Share, 2025 | |
  61. FIGURE 17 South America and Middle East & Africa Country-Level Share, 2025 | |
  62. FIGURE 18 Competitive Landscape — Estimated Revenue Share Bands, 2026 | |
  63. FIGURE 19 Competitive Positioning Matrix — Capability vs Deployment Scale | |
  64. FIGURE 20 Driver and Restraint Impact Weighting Chart

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By TypeMediator-Based MFC; Mediator-Free MFCMediator-Free MFCMediator-Free MFC
By DesignSingle-Chamber; Dual-Chamber; Stacked / Up-Flow; OthersSingle-ChamberDual-Chamber
By Electrode MaterialCarbon Cloth/Felt; Graphite & Graphene-Based; Metal & Metal Oxide; Composite & OthersCarbon Cloth/FeltComposite & Others
By Substrate SourceMunicipal Wastewater / Industrial Effluents; Agricultural & Food Waste; Sediment & Soil Organics; Synthetic & Other MediaMunicipal Wastewater / Industrial EffluentsSediment & Soil Organics
By ApplicationWastewater Treatment & Energy Recovery; Biosensing & Environmental Monitoring; Remote & Off-Grid Power; Hydrogen & Chemical RecoveryWastewater Treatment & Energy RecoveryBiosensing & Environmental Monitoring
By End-UserIndustrial; Research Institutions; Municipal Utilities; Defense & Remote OperationsIndustrialMunicipal Utilities
By GeographyNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaAsia-PacificAsia-Pacific


Market Segmentation Overview

By Type

Sub-SegmentKey Trend
Mediator-Based MFCConfined to controlled research settings where reproducibility outweighs consumable cost
Mediator-Free MFCCommercial default; naturally electroactive biofilms remove recurring chemical expense


Type selection is effectively settled in commercial practice. Synthetic electron shuttles introduce cost, toxicity and disposal obligations that no discharge-regulated operator will accept, leaving mediator-free chemistry to carry virtually all field deployment through 2035.

By Design

Sub-SegmentKey Trend
Single-ChamberLowest capital cost; air cathode removes need for aerated catholyte
Dual-ChamberRising share as separator costs fall and buyers prioritise output consistency
Stacked / Up-FlowPreferred route to industrial throughput via modular series arrangement
OthersHybrid constructed-wetland and tubular configurations in demonstration phase


Design competition is really a debate about how to scale. Single-chamber units win small installations on price, while stacked arrangements are the only architecture with a credible path to plant-scale flows without proportional cost escalation.

By Electrode Material

Sub-SegmentKey Trend
Carbon Cloth/FeltEstablished workhorse with proven biocompatibility and stable supply
Graphite & Graphene-BasedHigher conductivity and surface area at rising material cost
Metal & Metal OxideConcentrated in cathode catalysis where reduction kinetics limit output
Composite & OthersPlatinum-group-metal-free catalyst development targeting cost removal


Materials remain the largest lever on reactor economics. Successful commercialization of catalyst formulations that avoid precious metals would remove a substantial share of bill-of-materials cost and improve payback across every application segment.

By Substrate Source

Sub-SegmentKey Trend
Municipal Wastewater / Industrial EffluentsContinuous organic load supports steady-state operation
Agricultural & Food WasteHigh-strength seasonal streams generate the strongest surcharge savings
Sediment & Soil OrganicsEnables long-duration, low-power deployments in inaccessible locations
Synthetic & Other MediaCalibration and comparative laboratory work


Substrate quality determines commercial viability more than any hardware choice. High-strength, carbohydrate-rich streams from beverage, distillery and confectionery production deliver the shortest payback and account for the majority of installed commercial capacity.

By Application

Sub-SegmentKey Trend
Wastewater Treatment & Energy RecoveryCore commercial application driven by aeration and surcharge avoidance
Biosensing & Environmental MonitoringSelf-powered compliance telemetry at unserviced outfall locations
Remote & Off-Grid PowerTrickle power for oceanographic, riverine and defense sensor networks
Hydrogen & Chemical RecoveryVoltage-assisted reconfiguration unlocks a second revenue stream


Applications divide neatly between volume and margin. Treatment carries the revenue, while sensing and remote power carry higher unit economics and provide vendors with useful engineering exposure to long-duration field operation.

By End-User

Sub-SegmentKey Trend
IndustrialFast procurement cycles anchored to payback period
Research InstitutionsGrant-funded programmes sustaining component and kit demand
Municipal UtilitiesDirective-driven adoption expanding through the 2030s
Defense & Remote OperationsSmall-volume, high-margin specification-led purchasing


End-user behaviour splits along decision-speed lines. Industrial buyers move within a fiscal year on economic grounds; municipal utilities move on statutory deadlines, which is why their contribution grows faster than their present share suggests.



Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.