MICE Market (2026 - 2035)

ID: MRFR/CG/10920-CR 128 Pages Pradeep Nandi Last Updated: September 15, 2026
MICE Market Size, Share, Industry Trend & Analysis Research Report By Connectivity (Wireless (2.4 GHz RF), Bluetooth, Wired (USB), Dual-Mode / Hybrid), By Sensor Technology (Optical, Laser, Trackball, Touch / Gesture), By Application (Office / Commercial, Gaming, Personal / Home, Industrial & Healthcare), By Distribution Channel (Online Retail, Offline Specialty & Electronics, OEM Bundling, Direct Enterprise / B2B), By Region (North America, Europe, Asia-Pacific, South America, Middle East & Africa) - Forecast to 2035
MICE Market
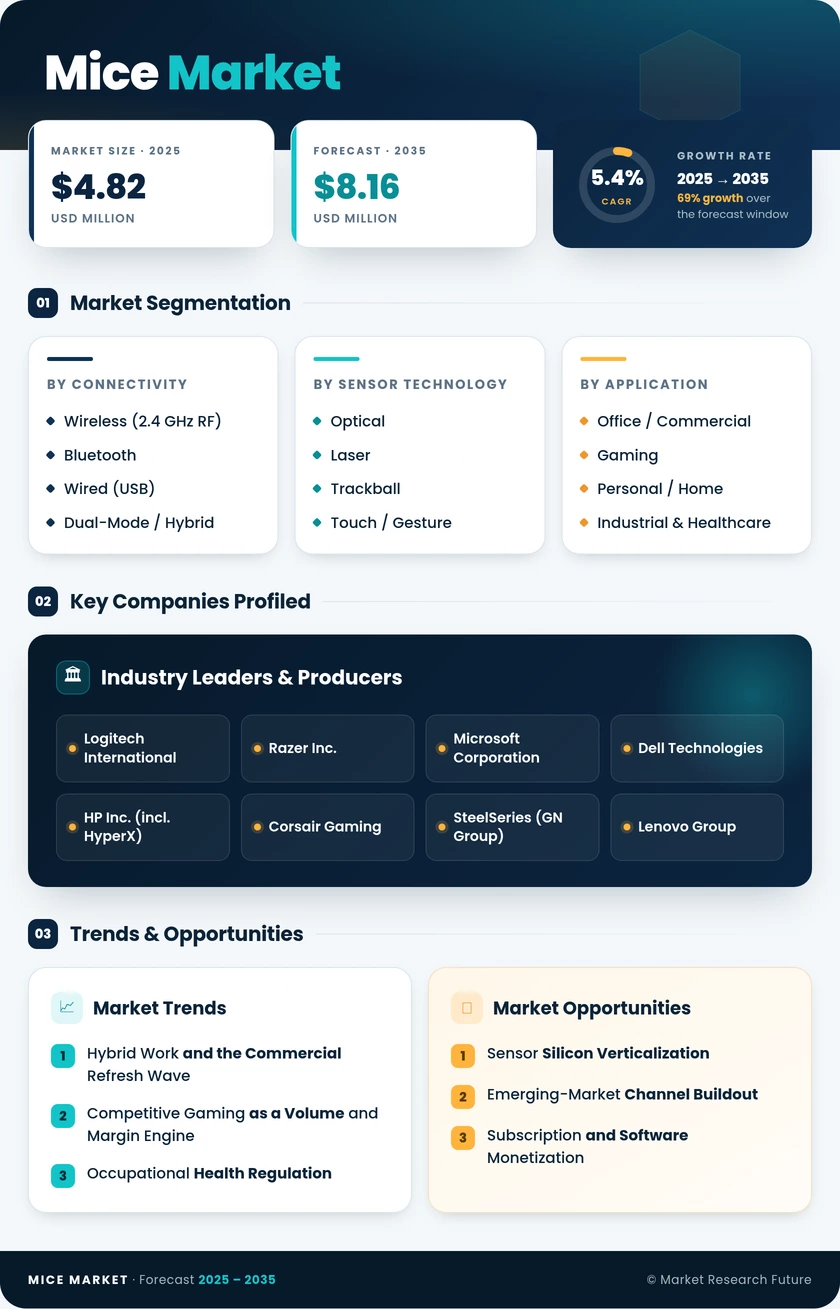
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.4%
2025 Market SizeUSD 4.82 Billion
2035 Market SizeUSD 8.16 Billion
Key Players
Logitech International
Razer Inc.
Microsoft Corporation
Dell Technologies
HP Inc.
Corsair Gaming
Opportunities
  • Sensor Silicon Verticalization
  • Emerging-Market Channel Buildout
  • Subscription and Software Monetization
  1. 1 Market Overview |
    1. 1.1 Study Assumptions & Market Definition |
    2. 1.2 Scope of the Study |
    3. 1.3 Research Methodology
  2. 2 Market Summary & Key Report Takeaways
  3. 3 Global Market Size & Forecast (2021–2035) |
    1. 3.1 Historical Market Size (2021–2025) |
    2. 3.2 Current & Forecast Market Size (2026–2035) |
    3. 3.3 Year-over-Year Growth Analysis
  4. 4 Market Dynamics — Driver Impact Analysis |
    1. 4.1 Hybrid Work and the Commercial Refresh Wave |
    2. 4.2 Competitive Gaming as a Volume and Margin Engine |
    3. 4.3 Occupational Health Regulation |
    4. 4.4 Sensor and Microcontroller Cost Deflation |
    5. 4.5 E-Commerce Channel Penetration
  5. 5 Market Dynamics — Restraints Impact Analysis |
    1. 5.1 Saturation and Lengthening Replacement Cycles |
    2. 5.2 Substitution From Integrated Input Surfaces |
    3. 5.3 Price Erosion in the Entry Tier |
    4. 5.4 E-Waste and Packaging Compliance Costs
  6. 6 Market Opportunity Analysis |
    1. 6.1 Sensor Silicon Verticalization |
    2. 6.2 Emerging-Market Channel Buildout |
    3. 6.3 Subscription and Software Monetization |
    4. 6.4 Sealed and Antimicrobial Devices for Regulated Environments |
    5. 6.5 Circularity and Refurbishment Programs |
    6. 6.6 Industry Value Chain Analysis |
    7. 6.7 Porter's Five Forces Analysis
  7. 7 Regional Analysis |
    1. 7.1 North America | |
      1. 7.1.1 United States | |
      2. 7.1.2 Canada | |
      3. 7.1.3 Mexico |
    2. 7.2 Europe | |
      1. 7.2.1 Germany | |
      2. 7.2.2 United Kingdom | |
      3. 7.2.3 France | |
      4. 7.2.4 Rest of Europe |
    3. 7.3 Asia-Pacific | |
      1. 7.3.1 China | |
      2. 7.3.2 India | |
      3. 7.3.3 Japan | |
      4. 7.3.4 South Korea | |
      5. 7.3.5 Rest of Asia-Pacific |
    4. 7.4 South America | |
      1. 7.4.1 Brazil | |
      2. 7.4.2 Argentina | |
      3. 7.4.3 Rest of South America |
    5. 7.5 Middle East & Africa | |
      1. 7.5.1 UAE | |
      2. 7.5.2 Saudi Arabia | |
      3. 7.5.3 South Africa | |
      4. 7.5.4 Rest of Middle East & Africa
  8. 8 Future Outlook (2026–2035) |
    1. 8.1 Sensor Intelligence and Adaptive Input |
    2. 8.2 Wireless Convergence and Spectrum Efficiency |
    3. 8.3 Sustainability Reporting as Procurement Criteria |
    4. 8.4 Regional Manufacturing Rebalancing
  9. 9 Market Segmentation Analysis |
    1. 9.1 By Connectivity | |
      1. 9.1.1 Wireless (2.4 GHz RF) | |
      2. 9.1.2 Bluetooth | |
      3. 9.1.3 Wired (USB) | |
      4. 9.1.4 Dual-Mode / Hybrid |
    2. 9.2 By Sensor Technology | |
      1. 9.2.1 Optical | |
      2. 9.2.2 Laser | |
      3. 9.2.3 Trackball | |
      4. 9.2.4 Touch / Gesture |
    3. 9.3 By Application | |
      1. 9.3.1 Office / Commercial | |
      2. 9.3.2 Gaming | |
      3. 9.3.3 Personal / Home | |
      4. 9.3.4 Industrial & Healthcare |
    4. 9.4 By Distribution Channel | |
      1. 9.4.1 Online Retail | |
      2. 9.4.2 Offline Specialty & Electronics | |
      3. 9.4.3 OEM Bundling | |
      4. 9.4.4 Direct Enterprise / B2B
  10. 10 Competitive Landscape |
    1. 10.1 Market Share Analysis (2026) |
    2. 10.2 Competitive Benchmarking Matrix |
    3. 10.3 Company Profiles | |
      1. 10.3.1 Logitech International | |
      2. 10.3.2 Razer Inc. | |
      3. 10.3.3 Microsoft Corporation | |
      4. 10.3.4 Dell Technologies | |
      5. 10.3.5 HP Inc. (HyperX) | |
      6. 10.3.6 Corsair Gaming | |
      7. 10.3.7 SteelSeries (GN Group) | |
      8. 10.3.8 Lenovo Group | |
      9. 10.3.9 ASUS (ROG) | |
      10. 10.3.10 Apple Inc.
  11. 11 Recent Developments & News
  12. 12 Report Scope & Methodology |
    1. 12.1 Study Period & Base Year |
    2. 12.2 Data Sources & Citations |
    3. 12.3 Abbreviations
  13. 13 Detailed Sources and Citations
  14. 14 Frequently Asked Questions (FAQs)
  15. 15 LIST OF TABLES |
  16. TABLE 1 Global Mice Market Size & Forecast, by Revenue (USD Billion), 2021–2035 |
  17. TABLE 2 Global Mice Market — Year-over-Year Growth Analysis, 2021–2035 |
  18. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 |
  19. TABLE 4 Restraints Impact Analysis Matrix, 2026–2035 |
  20. TABLE 5 Global Mice Market Size, by Region, 2021–2035 (USD Billion) |
  21. TABLE 6 North America Mice Market Size, by Country, 2021–2035 (USD Billion) |
  22. TABLE 7 Europe Mice Market Size, by Country, 2021–2035 (USD Billion) |
  23. TABLE 8 Asia-Pacific Mice Market Size, by Country, 2021–2035 (USD Billion) |
  24. TABLE 9 South America Mice Market Size, by Country, 2021–2035 (USD Billion) |
  25. TABLE 10 Middle East & Africa Mice Market Size, by Country, 2021–2035 (USD Billion) |
  26. TABLE 11 Global Mice Market Size, by Connectivity, 2021–2035 (USD Billion) |
  27. TABLE 12 Global Mice Market Size, by Sensor Technology, 2021–2035 (USD Billion) |
  28. TABLE 13 Global Mice Market Size, by Application, 2021–2035 (USD Billion) |
  29. TABLE 14 Global Mice Market Size, by Distribution Channel, 2021–2035 (USD Billion) |
  30. TABLE 15 North America Mice Market Size, by Connectivity, 2021–2035 (USD Billion) |
  31. TABLE 16 North America Mice Market Size, by Application, 2021–2035 (USD Billion) |
  32. TABLE 17 Europe Mice Market Size, by Connectivity, 2021–2035 (USD Billion) |
  33. TABLE 18 Europe Mice Market Size, by Application, 2021–2035 (USD Billion) |
  34. TABLE 19 Asia-Pacific Mice Market Size, by Connectivity, 2021–2035 (USD Billion) |
  35. TABLE 20 Asia-Pacific Mice Market Size, by Application, 2021–2035 (USD Billion) |
  36. TABLE 21 South America Mice Market Size, by Application, 2021–2035 (USD Billion) |
  37. TABLE 22 Middle East & Africa Mice Market Size, by Application, 2021–2035 (USD Billion) |
  38. TABLE 23 United States Mice Market Size, by Segment, 2021–2035 (USD Billion) |
  39. TABLE 24 China Mice Market Size, by Segment, 2021–2035 (USD Billion) |
  40. TABLE 25 India Mice Market Size, by Segment, 2021–2035 (USD Billion) |
  41. TABLE 26 Competitive Benchmarking Matrix — Global Mice Market, 2026 |
  42. TABLE 27 Company Profiles — Key Players, Global Mice Market |
  43. TABLE 28 Recent Developments & Strategic Announcements, 2023–2025 |
  44. TABLE 29 Report Scope & Methodology Summary |
  45. TABLE 30 Detailed Sources and Citations Index
  46. 16 LIST OF FIGURES |
  47. FIGURE 1 Global Mice Market — Market Dynamics Overview (Drivers, Restraints, Opportunities) |
  48. FIGURE 2 Industry Value Chain Analysis |
  49. FIGURE 3 Porter's Five Forces Analysis |
  50. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Billion) |
  51. FIGURE 5 Year-over-Year Growth Trend, 2022–2035 (%) |
  52. FIGURE 6 Market Share by Connectivity, 2025 vs 2035 (%) |
  53. FIGURE 7 Market Share by Sensor Technology, 2025 (%) |
  54. FIGURE 8 Market Share by Application, 2025 vs 2035 (%) |
  55. FIGURE 9 Market Share by Distribution Channel, 2025 (%) |
  56. FIGURE 10 Regional Revenue Share, 2025 (%) |
  57. FIGURE 11 Regional CAGR Comparison, 2026–2035 (%) |
  58. FIGURE 12 Country-Level Revenue Contribution, Top 10 Markets, 2025 |
  59. FIGURE 13 Competitive Landscape — Vendor Share Positioning Map, 2026 |
  60. FIGURE 14 Average Selling Price Trend by Application Segment, 2021–2035 |
  61. FIGURE 15 Driver vs Restraint Net Impact on Forecast CAGR

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By ConnectivityWireless (2.4 GHz RF), Bluetooth, Wired (USB), Dual-Mode / HybridWireless (2.4 GHz RF)Dual-Mode / Hybrid
By Sensor TechnologyOptical, Laser, Trackball, Touch / GestureOpticalTouch / Gesture
By ApplicationOffice / Commercial, Gaming, Personal / Home, Industrial & HealthcareOffice / CommercialGaming
By Distribution ChannelOnline Retail, Offline Specialty & Electronics, OEM Bundling, Direct Enterprise / B2BOnline RetailDirect Enterprise / B2B
By RegionNorth America, Europe, Asia-Pacific, South America, Middle East & AfricaNorth AmericaAsia-Pacific


Market Segmentation Overview

By Connectivity

Sub-SegmentKey Trend
Wireless (2.4 GHz RF)Sub-2ms latency now competitive with wired for professional play
BluetoothMulti-host pairing standard across productivity flagships
Wired (USB)Retained by esports and institutional bulk procurement
Dual-Mode / HybridFastest-growing tier; commands 30–40% price premium


Connectivity has become the primary purchase filter for buyers. The wireless-versus-wired debate is effectively settled in favor of radio for mainstream use, and the remaining competitive action sits in how many hosts a single device can serve.

By Sensor Technology

Sub-SegmentKey Trend
Optical26,000+ DPI ceilings now standard in premium tiers
LaserNiche retention on glass and glossy surfaces
TrackballGrowth driven by workplace strain-reduction procurement
Touch / GestureAdoption concentrated in creative and presentation workflows


Sensor differentiation has narrowed to firmware quality rather than raw resolution. Vendors increasingly compete on surface calibration, lift-off distance tuning, and power efficiency per tracked millimetre.

By Application

Sub-SegmentKey Trend
Office / CommercialThree-year refresh schedules replacing five-year cycles
GamingAverage selling prices 3.1x commercial equivalents
Personal / HomeMulti-device households drive repeat purchase
Industrial & HealthcareIP68 and antimicrobial specifications gaining tender mandates


Application mix determines margin structure more than any other dimension. Commercial volume funds scale; gaming and regulated-environment devices supply the profit.

By Distribution Channel

Sub-SegmentKey Trend
Online RetailReview velocity now a leading indicator of SKU success
Offline Specialty & ElectronicsFeel-testing sustains premium conversion rates
OEM BundlingAttach rates rising on managed commercial desktops
Direct Enterprise / B2BContract procurement growing fastest by channel CAGR


Channel strategy diverges sharply by geography. Online dominance in Brazil and India contrasts with the persistence of specialty retail across Japan and Germany, where tactile evaluation still drives premium purchase decisions.

 

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.