Medical Gases and Equipment Market (2026 - 2035)

Medical Gases and Equipment Market Research Report By Type (Medical Gases, Medical Equipment, Integrated Medical Gas Systems), By Medical Gas Type (Oxygen, Nitrous Oxide, Carbon Dioxide, Helium, Air), By End Use (Hospitals, Clinics, Home Healthcare, Emergency Services), By Equipment Type (Cylinders, Pipeline Systems, Manifolds, Regulators) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth & Industry Forecast 2025 To 2035

Forecast Period
2026-2035
CAGR
7.48%
2025 Market Size
USD 19.35 Billion
2035 Market Size
USD 39.38 Billion
Medical Device ● Updated August 24, 2026 Report ID: MRFR/MED/5475-HCR | Pages: 200 | Author: Rahul Gotadki, Snehal Singh

Medical Gases and Equipment Market Summary

The Global Medical Gases and Equipment Market size was valued at USD 19.35 Billion in 2025, and the market is projected to grow from USD 20.58 Billion in 2026 to USD 39.38 Billion by 2035, registering a CAGR of 7.48% during the forecast period 2026–2035. Two catalysts are accelerating this trajectory: the WHO's expanded guidelines on oxygen access for low- and middle-income health facilities [1] and national insurance programs in the U.S., Germany, and Japan that have broadened reimbursement for home-based respiratory therapy devices [2]. The Medical Gases and Equipment Market is no longer a commoditized procurement line item — it sits at the intersection of respiratory care, surgical innovation, and diagnostic imaging infrastructure.

A significant technology transformation is underway across the Medical Gases and Equipment Market. Hospitals are progressively replacing legacy high-pressure cylinder banks with on-site pressure swing adsorption (PSA) oxygen generation plants, a shift accelerated by over USD 1.2 Billion in pandemic-era capital spending across 90+ countries [3]. Portable oxygen concentrators have shrunk from 10 kg units to sub-2 kg wearables, enabling true ambulatory therapy. At the same time, helium-recycling systems for MRI suites are drawing fresh capital as global helium supply remains constrained, with the U.S. Bureau of Land Management's Federal Helium Reserve closure reshaping procurement strategies [4].

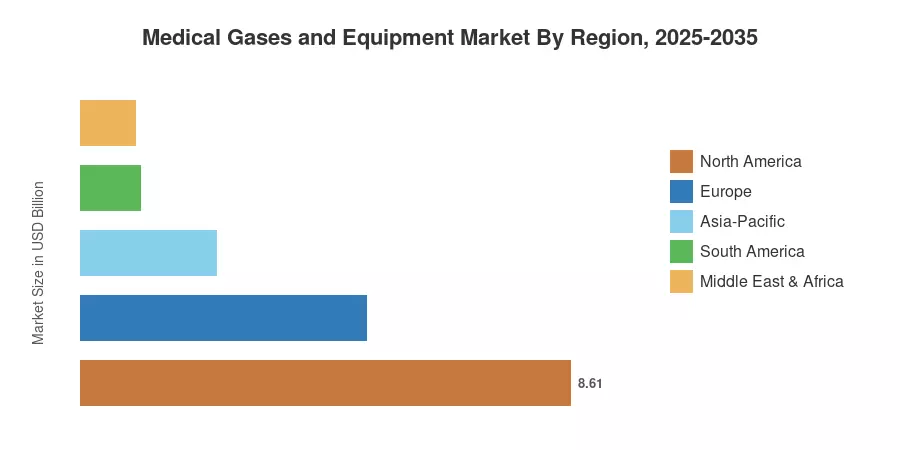
North America commands approximately 44.5% of the Medical Gases and Equipment Market, anchored by the depth of its hospital infrastructure and established home healthcare reimbursement frameworks. Asia-Pacific is the fastest-growing region at a projected 12.35% CAGR through 2035, driven by China's hospital construction wave and India's Ayushman Bharat health coverage expansion. Europe holds the second-largest share at roughly 26%, with tightening EU Medical Device Regulation (MDR) requirements spurring equipment upgrades across member states. The Medical Gases and Equipment Market is poised for a decade of above-trend expansion as respiratory disease burdens grow and surgical volumes rise globally.


Key Report Takeaways

• By Product Type

  • Medical gases captured 59.8% of the Medical Gases and Equipment Market in 2025, reflecting steady demand for oxygen, nitrous oxide, and specialty gas mixtures across therapeutic and diagnostic applications.
  • Medical gas equipment is advancing at a faster pace as hospitals invest in PSA plants, pipeline infrastructure, and digital monitoring systems.

• By Application

  • Therapeutic uses accounted for 51.2% of total demand in the Medical Gases and Equipment Market, driven by long-term oxygen therapy and anesthesia delivery in surgical suites.
  • Diagnostic and imaging applications are the fastest-growing segment, posting a 10.05% CAGR through 2035 as MRI installations and PET-CT adoption rise in emerging markets.

• By Region

  • North America led the Medical Gases and Equipment Market with a 44.5% revenue share in 2025, supported by mature payer systems and high per-capita healthcare expenditure.
  • Asia-Pacific is forecast to expand at a 12.35% CAGR during 2026–2035, the fastest among all regions.


Market Size and Forecast (2021–2035)

Market Research Future's estimates draw on primary interviews with gas suppliers, hospital procurement officers, and regulatory bodies, combined with secondary data from company filings, trade associations, and government health ministry databases. Historical figures reflect actual shipment and revenue data; forecast values apply compound growth modeling calibrated to policy timelines and infrastructure investment cycles.
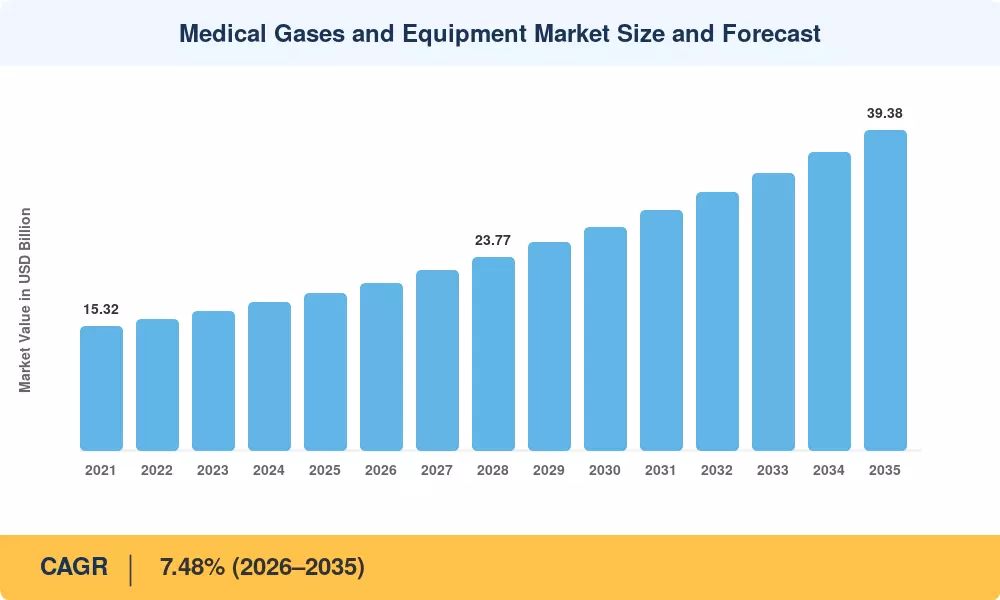
Medical Gases and Equipment Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Rising COPD and respiratory disease prevalence ~22% Global Long-term (≥4 yr)
Hospital PSA plant adoption replacing cylinders ~18% Asia-Pacific, MEA Medium-term (2–4 yr)
Home healthcare oxygen therapy expansion ~16% North America, Europe Long-term (≥4 yr)
MRI and diagnostic imaging infrastructure growth ~14% Asia-Pacific Medium-term (2–4 yr)
Ambulatory surgery center (ASC) volume growth ~12% North America Short-term (≤2 yr)
Helium supply constraints and recycling technology ~10% Global Medium-term (2–4 yr)
Digital gas monitoring and IoT integration ~8% Europe, North America Long-term (≥4 yr)


Rising Chronic Respiratory Disease Burden

According to Global Burden of Disease data, the prevalence of COPD exceeded 600 million diagnosed cases globally by 2025, and patients need oxygen therapy equipment for longer periods of time—typically 5–15 years—due to declining mortality rates [7]. Medical-grade oxygen and the equipment needed to supply it are in constant demand due to the growing patient population. An estimated USD 50 billion is spent on managing COPD in the United States alone each year; the CDC predicts that amount will increase by 3.5% yearly until 2030 [16].


Hospital Transition to On-Site PSA Oxygen Generation

Launched after the COVID-19 crisis, India's national PSA oxygen program pledged an extra USD 800 million to boost capacity across district hospitals and constructed over 4,000 on-site plants by 2024 [9]. Supply security is increased, and logistical expenses are reduced by 30–40% as a result of the switch from cylinder-dependent supply chains to on-site generation. With funding from the World Bank and technical assistance from WHO, similar projects are expanding throughout Latin America, Southeast Asia, and Sub-Saharan Africa [1].


Home Healthcare Expansion

Medicare's competitive bidding program for durable medical equipment reshaped the U.S. home oxygen landscape, consolidating suppliers while expanding patient access to portable concentrators and liquid oxygen systems [2]. Germany's statutory health insurance funds now cover home oxygen therapy for over 500,000 patients, and Japan's Long-Term Care Insurance system includes respiratory equipment coverage for its rapidly aging population [17]. The home healthcare segment of the Medical Gases and Equipment Market is projected to post a 9.05% CAGR through 2035.

Diagnostic Imaging Infrastructure Expansion

Asia-Pacific's installed base of MRI scanners grew 9% annually between 2021 and 2024, with China adding approximately 1,200 new MRI units per year [12]. Each superconducting MRI system requires 1,500–2,000 liters of liquid helium for initial cooling and periodic top-ups, creating consistent demand within the Medical Gases and Equipment Market. The shift toward helium-free magnet designs will alter — but not eliminate — this demand channel over the forecast period [10].


Restraints Impact Analysis

The restraint impact percentages represent directional estimates of headwinds to Medical Gases and Equipment Market growth. These should not be subtracted directly from the CAGR; they indicate relative severity.

Restraint ~% Negative Impact on CAGR Geographic Relevance Impact Timeline
Reimbursement compression and margin pressure ~−25% North America Short-term (≤2 yr)
Helium supply volatility and pricing uncertainty ~−20% Global Medium-term (2–4 yr)
Stringent regulatory approval timelines (EU MDR) ~−18% Europe Medium-term (2–4 yr)
High capital cost of PSA plant installation ~−15% Asia-Pacific, MEA Short-term (≤2 yr)
Cylinder transport safety and logistics complexity ~−12% Global Long-term (≥4 yr)


Reimbursement Compression in the U.S.

Since 2020, CMS bundled payment schemes for ambulatory surgery centers have compressed supplier margins by an estimated 15–20% by combining oxygen and anesthesia supply into a single facility cost [2]. While smaller regional suppliers are facing existential margin pressure, device makers are responding by vertical integration, which involves acquiring gas distribution facilities to capture more of the value chain. In the short term, this dynamic has an impact on the medical gases and equipment market.


Helium Supply Volatility

The United States, Qatar, and Russia account for around 75% of the world's helium production capacity, which is still concentrated [4]. Due to the U.S. Federal Helium Reserve's closure and sporadic interruptions at Qatar's Ras Laffan facility, prices have fluctuated by more than 30% in a single quarter. These changes have an impact on the Medical Gases and Equipment Market, especially on specialty gas mixes used in respiratory diagnostics and MRI cooling operations.


EU MDR Compliance Costs

The EU Medical Device Regulation (2017/745) requires re-certification of legacy gas delivery equipment under stricter clinical evaluation and post-market surveillance standards [8]. Compliance costs for mid-sized manufacturers range from EUR 2–5 Million per product family, delaying new product introductions by 12–18 months and diverting R&D budgets from innovation to regulatory documentation.


Medical Gases and Equipment Market Opportunities

Telehealth-Integrated Home Oxygen Monitoring

Connected oxygen concentrators equipped with pulse oximetry sensors and cloud-based dashboards are enabling remote patient management at scale. Payers in the U.S. and UK are beginning to offer premium reimbursement codes for telemonitored home oxygen therapy, creating a new value layer for the Medical Gases and Equipment Market.

Helium Recycling and Closed-Loop MRI Cooling

With helium prices rising 40% since 2021, MRI manufacturers are investing in closed-loop cryocooler systems that reduce helium consumption by 90% [10]. This creates a parallel equipment opportunity: retrofit kits, reclamation systems, and helium-free magnet platforms represent a potential USD 1.5 Billion incremental addressable market by 2032.

Emerging Market Hospital Infrastructure Build-Out

Sub-Saharan Africa operates fewer than 0.5 MRI units per million population, compared with 40+ in Japan [12]. The African Development Bank's Health Infrastructure Investment Platform targets USD 3 Billion in hospital construction through 2030, each project requiring piped gas systems, manifolds, and monitoring equipment — opening a greenfield channel for the Medical Gases and Equipment Market.

Data Monetization Through Smart Gas Management Platforms

IoT-enabled gas monitoring systems generate real-time consumption, pressure, and purity data that hospitals can use for predictive maintenance and inventory optimization [11]. Equipment suppliers are developing subscription-based analytics platforms — a gas-as-a-service model — that transform one-time equipment sales into recurring revenue streams.

Nitrous Oxide Alternatives and Green Anesthesia Initiatives

The NHS England Greener NHS program targets an 80% reduction in nitrous oxide atmospheric emissions by 2028, spurring demand for capture-and-destroy systems and alternative analgesic delivery platforms [19]. This regulatory push creates equipment upgrade cycles that benefit the Medical Gases and Equipment Market across Europe and Australasia.


Medical Gases and Equipment Market Future Outlook

AI-Enabled Gas Management and Predictive Analytics

Artificial intelligence is entering the Medical Gases and Equipment Market through smart pipeline monitoring systems that predict consumption patterns, detect leaks, and optimize delivery schedules. Early adopters report 15–20% reductions in gas waste, and major suppliers are embedding ML algorithms into manifold control units [11]. By 2030, AI-driven inventory management is expected to become a procurement differentiator in hospital gas contracts.

Decarbonization of Medical Gas Supply Chains

Hospitals account for approximately 4.4% of global net CO₂ emissions, and medical gas production — particularly industrial-scale air separation for oxygen and nitrogen — is energy-intensive [23]. The shift toward green hydrogen-powered cryogenic plants and solar-powered PSA units is gaining traction, with Linde and Air Liquide both announcing net-zero roadmaps for their healthcare gas operations by 2035. The Medical Gases and Equipment Market will increasingly be evaluated through ESG procurement criteria.

Miniaturization and Wearable Respiratory Devices

Portable oxygen concentrators weighing under 1.5 kg are now entering clinical trials, enabled by advances in molecular sieve adsorbents and brushless motor technology [6]. These devices extend the Medical Gases and Equipment Market into consumer wellness and personal health monitoring, blurring the line between medical devices and health wearables. The IEC 80601-2-69 standard update expected in 2027 will define regulatory pathways for this emerging category.

Platform Economics and Gas-as-a-Service Models

Traditional transactional supply agreements — buy cylinders, pay per refill — are giving way to platform-based models where suppliers bundle gas, equipment, monitoring, maintenance, and data analytics into unified service contracts [11]. This shift mirrors trends in industrial gas markets and creates stickier customer relationships. The Medical Gases and Equipment Market's competitive landscape will increasingly favor vertically integrated players capable of delivering end-to-end managed services.


Medical Gases and Equipment Market Segmentation

By Product Type

Segment Key Metric Primary Demand Driver
Medical Gases 59.8% share (2025) Chronic respiratory therapy and surgical anesthesia
Medical Gas Equipment CAGR 8.3% (2026–2035) PSA plant adoption and pipeline infrastructure upgrades


Medical gases dominate the Medical Gases and Equipment Market by revenue, reflecting the consumable nature of oxygen, nitrous oxide, medical air, nitrogen, carbon dioxide, and specialty gas mixtures. Oxygen alone represents over a third of total gas revenue, driven by the sheer volume consumed in respiratory therapy and surgical applications. Equipment, while smaller in absolute terms, is growing faster as hospitals transition from cylinder-based supply to centralized on-site generation with digital monitoring overlays.

By Gas Type

Segment Key Metric Primary Demand Driver
Oxygen 36.5% share (2025) Long-term respiratory therapy and surgical oxygenation
Nitrous Oxide USD 1.94 Billion (2025) Anesthesia and procedural sedation
Medical Air CAGR 7.1% (2026–2035) Ventilator-driven demand in ICUs
Carbon Dioxide (CO₂) USD 0.87 Billion (2025) Laparoscopic surgery insufflation
Nitrogen CAGR 6.9% (2026–2035) Cryotherapy and cryopreservation
Helium & Others CAGR 11.5% (2026–2035) MRI cooling and specialty diagnostic applications


Oxygen remains the volumetric backbone of the Medical Gases and Equipment Market, consumed across virtually every clinical setting. The helium and specialty gas segment is growing fastest, driven by diagnostic imaging expansion in Asia-Pacific — though helium supply constraints inject pricing volatility that alternately boosts revenue and deters procurement.

By Equipment Type

Segment Key Metric Primary Demand Driver
Cylinders & Tanks 42.3% share (2025) Established hospital and ambulance supply infrastructure
Pipelines & Manifolds CAGR 8.1% (2026–2035) New hospital construction with centralized gas delivery
Vacuum & Compressor Systems CAGR 9.75% (2026–2035) Surgical suite and ICU infrastructure modernization
Monitoring Systems USD 1.12 Billion (2025) IoT-enabled compliance and safety requirements


Cylinders and tanks remain the largest equipment category in the Medical Gases and Equipment Market, particularly in regions where piped gas infrastructure has not yet been installed. Vacuum and compressor systems are growing fastest as new surgical suites and ICUs require integrated suction and compressed air capabilities compliant with NFPA 99 and ISO 7396-1 standards [18].

By Application

Segment Key Metric Primary Demand Driver
Therapeutic 51.2% share (2025) COPD, asthma, sleep apnea, and surgical anesthesia
Diagnostic & Imaging CAGR 10.05% (2026–2035) MRI, PET-CT, and pulmonary function testing
Pharmaceutical USD 2.48 Billion (2025) Drug manufacturing, cold chain, and bioprocessing


Therapeutic applications anchor the Medical Gases and Equipment Market, spanning inpatient oxygen delivery, outpatient respiratory therapy, and operating room anesthesia. Diagnostic and imaging is the fastest-growing application category, propelled by MRI fleet expansion and the growing adoption of xenon-enhanced CT imaging for cerebral blood flow studies [12].

By End User

Segment Key Metric Primary Demand Driver
Hospitals 57.6% share (2025) Centralized procurement and high-volume consumption
Ambulatory Surgical Centers CAGR 7.8% (2026–2035) Outpatient procedure volume growth
Home Healthcare CAGR 9.05% (2026–2035) Long-term oxygen therapy and aging demographics
Others (Pharma, Research) USD 1.16 Billion (2025) Biotech manufacturing and clinical research


Hospitals remain the primary revenue channel for the Medical Gases and Equipment Market, given their scale of gas consumption and capital equipment budgets. Home healthcare is the fastest-growing end-user segment, reflecting demographic aging and payer incentives to shift chronic respiratory care from inpatient to outpatient settings [2].


Regional Market Share Analysis

Region Key Metric Primary Investment Themes
North America 44.5% share (2025) Home healthcare expansion, ASC growth, reimbursement reform
Europe 26.0% share (2025) EU MDR compliance, green anesthesia, aging demographics
Asia-Pacific 12.35% CAGR (2026–2035) Hospital construction, PSA adoption, MRI installation
South America USD 1.06 Billion (2025) Public health system modernization, oxygen access programs
Middle East & Africa USD 0.97 Billion (2025) Greenfield hospital builds, medical tourism infrastructure
Total USD 19.35 Billion (2025)

The Medical Gases and Equipment Market exhibits significant regional variation in maturity, growth trajectory, and competitive structure. North America and Europe represent mature, replacement-driven markets, while Asia-Pacific and the Middle East & Africa are in expansionary phases characterized by new hospital construction and first-time equipment procurement.


North America

Country Key Metric Key Driver
US 78% of regional share Medicare/Medicaid oxygen reimbursement coverage
Canada CAGR 6.9% (2026–2035) Provincial health authority equipment procurement cycles
Mexico USD 0.52 Billion (2025) IMSS hospital modernization program


The U.S. dominates North America's Medical Gases and Equipment Market, with its 6,000+ hospitals and 5,800+ ambulatory surgical centers creating dense demand networks for piped gas systems and portable delivery devices. CMS reimbursement policy changes under the DMEPOS competitive bidding program continue to reshape supplier economics, while Veterans Affairs hospitals are upgrading aging pipeline infrastructure under a USD 2.4 Billion capital improvement plan [2][16].

Europe

Country Key Metric Key Driver
Germany 22% of regional share Statutory insurance coverage for home oxygen therapy
UK CAGR 7.2% (2026–2035) NHS green anesthesia and emissions reduction targets
France USD 0.68 Billion (2025) National hospital investment plan (Ségur de la Santé)
Italy 12% of regional share Aging population and chronic respiratory disease load
Spain CAGR 6.8% (2026–2035) Public hospital equipment renewal cycles
Nordic Countries USD 0.34 Billion (2025) Advanced home healthcare delivery models
Russia 5% of regional share Import substitution policies for medical equipment
Rest of Europe CAGR 6.5% (2026–2035) EU cohesion fund healthcare investments


Europe's Medical Gases and Equipment Market is shaped by the EU MDR transition timeline, which requires all legacy gas delivery devices to hold updated CE marking by 2028 [8]. The UK's Greener NHS initiative is creating a distinct demand pocket for nitrous oxide destruction systems, while France's EUR 19 Billion Ségur de la Santé program includes dedicated funding for hospital gas infrastructure upgrades [19][20].

Asia-Pacific

Country Key Metric Key Driver
China 35% of regional share National hospital construction and MRI procurement
India CAGR 13.8% (2026–2035) PM-ABHIM and PSA oxygen plant deployment
Japan USD 0.78 Billion (2025) Aging population, advanced imaging density
South Korea CAGR 8.5% (2026–2035) Medical device export manufacturing hub
ASEAN 15% of regional share Thailand and Vietnam medical tourism infrastructure
Rest of Asia-Pacific CAGR 9.2% (2026–2035) Australia and New Zealand hospital upgrades


Asia-Pacific represents the most dynamic segment of the Medical Gases and Equipment Market. China's 14th Five-Year Plan committed RMB 480 Billion to healthcare infrastructure, including 1,200 new county-level hospitals requiring full piped gas systems [12]. India's Pradhan Mantri Ayushman Bharat Health Infrastructure Mission (PM-ABHIM) allocated INR 64,180 Crore to strengthen primary and tertiary care facilities, with on-site PSA oxygen generation a core component [9].

South America

Country Key Metric Key Driver
Brazil 58% of regional share SUS public health system modernization
Argentina CAGR 7.8% (2026–2035) Hospital equipment replacement demand
Rest of South America USD 0.21 Billion (2025) Colombia and Chile healthcare infrastructure expansion


Brazil's Unified Health System (SUS) serves over 190 million citizens and has prioritized oxygen supply security following pandemic-era shortages in Manaus and other northern cities [21]. The Medical Gases and Equipment Market in South America remains fragmented, with international gas majors competing alongside regional cylinder distributors for hospital contracts.

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 28% of regional share Vision 2030 healthcare megaprojects
UAE CAGR 9.8% (2026–2035) Medical tourism hub development
South Africa USD 0.18 Billion (2025) National Health Insurance pilot programs
Egypt CAGR 8.4% (2026–2035) Universal health coverage expansion
Rest of MEA 22% of regional share AfDB-funded hospital construction


Saudi Arabia's Vision 2030 includes 44 new hospitals and 12 medical cities, each requiring comprehensive gas pipeline networks and centralized monitoring systems [22]. The UAE's healthcare free zones — notably Dubai Healthcare City — attract international equipment suppliers seeking regional distribution hubs for the Medical Gases and Equipment Market.


Medical Gases and Equipment Market By Region, 2025-2035

Competitive Benchmarking

The Medical Gases and Equipment Market exhibits medium concentration, with the top five players holding an estimated 55–62% of global revenue. The Herfindahl-Hirschman Index (HHI) is estimated at 1,200–1,500, indicating moderate market power among leading industrial gas companies and medical device manufacturers. Competition occurs across three dimensions: gas supply contracts, equipment installation and servicing, and emerging digital monitoring platforms.

Company Est. Revenue Share Range Key Offerings for Medical Gases and Equipment Market Strategic Positioning
Linde plc ~14–18% Medical oxygen, nitrogen, helium supply; ENEOS PSA systems Global leader in industrial and medical gas supply with integrated distribution
Air Liquide S.A. ~13–17% Medical gases, home healthcare equipment, telemonitoring Vertically integrated from production to patient-side delivery
Air Products and Chemicals ~8–11% Bulk medical gas supply, on-site generation systems Focus on large-scale hospital and pharma supply contracts
Taiyo Nippon Sanso (Nippon Gases) ~5–8% Medical oxygen, nitrogen, specialty gases Asia-Pacific leader with expanding European presence
Messer Group ~4–6% Medical gases, cylinder management, pipeline installation Strong Central and Eastern European footprint
SOL Group ~3–5% Home care oxygen therapy, hospital gas management Southern European specialist with growing home healthcare division
Atlas Copco (BeaconMedaes) ~3–5% Medical air compressors, vacuum systems, gas pipeline systems Equipment-focused specialist for hospital infrastructure
GCE Group ~2–4% Gas flow control equipment, regulators, manifolds Niche equipment manufacturer with global distribution network
Getinge AB ~2–4% Anesthesia delivery systems, ventilators, surgical workflow Integrated surgical suite solutions provider
Amico Group ~2–3% Medical gas outlets, alarm systems, pipeline components Hospital construction-focused gas infrastructure specialist


Recent News & Developments


  • Atlas Copco (BeaconMedaes) (October 2024): Launched a next-generation digital medical air system with predictive maintenance capabilities and ISO 7396-1 compliance monitoring [Ref: Company Product Announcement].
  • WHO (July 2024): Published updated guidelines for medical oxygen ecosystem strengthening in low-resource settings, recommending on-site PSA generation as the primary supply model for district hospitals [Ref: WHO Technical Guidance Document].
  • Getinge AB (April 2024): Introduced an AI-assisted anesthesia workstation with integrated gas consumption analytics and automated agent delivery optimization [Ref: Company Press Release].
  • NHS England (January 2024): Released the Greener NHS Nitrous Oxide Action Plan, targeting an 80% reduction in atmospheric nitrous oxide releases from surgical facilities by 2028 [Ref: NHS England Policy Document].


  • India Ministry of Health (June 2023): Completed installation of the 5,000th PSA oxygen plant under the PM-ABHIM program, achieving national district-level oxygen self-sufficiency targets [Ref: Government Press Information Bureau].


Medical Gases and Equipment Market Report Scope

Parameter Detail
Market Scope Medical Gases and Equipment Market — global coverage across five regions
Study Period 2021–2035
Historical Period 2021–2024
Base Year 2025
Forecast Period 2026–2035
CAGR 7.48% (2026–2035)
Market Size (2025) USD 19.35 Billion
Market Size (2035) USD 39.38 Billion
Fastest Growing Segment Home Healthcare (End User); Diagnostic & Imaging (Application)
Companies Profiled 10 major players
Valuation Currency USD Billion

FAQs

How do hospital procurement teams typically structure long-term medical gas supply contracts?
Most hospitals use 5–7 year bulk supply agreements with built-in volume-price tiers and annual CPI escalators. Procurement teams increasingly require bundled maintenance and digital monitoring as contract components [5].
What certification standards must medical gas equipment meet before hospital installation?
Equipment must comply with ISO 7396-1 for pipeline systems, NFPA 99 for U.S. facilities, and EU MDR 2017/745 for European markets. Each standard mandates distinct testing and documentation protocols [8][18].
How does the shift to PSA oxygen generation affect cylinder distributors' business models?
PSA adoption reduces recurring cylinder refill revenue by 30–50% for distributors serving adopting hospitals. Many distributors are pivoting to maintenance services and smaller-facility supply where PSA is not cost-effective [3][9].
What role does medical gas purity play in purchasing decisions across the Medical Gases and Equipment Market?
Pharmacopoeia-grade purity (USP, EP, JP) is non-negotiable for patient-contact gases. Purity verification equipment and continuous monitoring systems have become standard procurement requirements [18].
How are emerging helium-free MRI technologies expected to reshape the Medical Gases and Equipment Market?
Helium-free magnets could reduce MRI-related helium demand by 80–90% once commercially scaled, though widespread adoption is unlikely before 2030 [10].
What financing mechanisms support medical gas infrastructure in low-income countries?
World Bank IDA grants and WHO Essential Medicines programs fund PSA installations in district hospitals. Concessional loans from regional development banks cover pipeline and manifold infrastructure [1][21].
How do suppliers in the Medical Gases and Equipment Market differentiate beyond price in competitive tenders?
Leading suppliers differentiate through 24/7 emergency response guarantees, telemetry-based inventory management, and integrated compliance reporting dashboards [5][11].    
Author
Author
Author Profile
Rahul Gotadki LinkedIn Research Manager
He holds an experience of about 9+ years in Market Research and Business Consulting, working under the spectrum of Life Sciences and Healthcare domains. Rahul conceptualizes and implements a scalable business strategy and provides strategic leadership to the clients. His expertise lies in market estimation, competitive intelligence, pipeline analysis, customer assessment, etc.
Co-Author
Co-Author Profile
Snehal Singh LinkedIn Manager - Research
High acumen in analyzing complex macro & micro markets with more than 6 years of work experience in the field of market research. By implementing her analytical skills in forecasting and estimation into market research reports, she has expertise in Packaging, Construction, and Equipment domains. She handles a team size of 20-25 resources and ensures smooth running of the projects, associated marketing activities, and client servicing.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, pharmacopeia standards, peer-reviewed medical journals, and authoritative health organizations. Key sources included the US Food & Drug Administration (FDA) Center for Drug Evaluation and Research (medical gas monographs), European Medicines Agency (EMA) Quality Working Party, United States Pharmacopeia (USP) Chapter 415 (Monograph Gases), European Pharmacopoeia (Ph. Eur.) General Monographs on Medical Gases, Compressed Gas Association (CGA) standards (CGA M-16, CGA P-2.6), European Industrial Gases Association (EIGA) safety standards, World Health Organization (WHO) Model List of Essential Medicines (oxygen, nitrous oxide), American Society of Anesthesiologists (ASA) practice guidelines, American Association for Respiratory Care (AARC) clinical practice guidelines, American Thoracic Society (ATS) respiratory care statements, National Institutes of Health (NIH) National Heart, Lung, and Blood Institute (NHLBI) respiratory disease statistics, Centers for Disease Control and Prevention (CDC) National Center for Health Statistics (chronic respiratory disease data), WHO Global Health Observatory (essential medical gases access data), EU Eurostat Healthcare Database, and national health ministry reports from key markets (China NMPA, Japan PMDA, India Ministry of Health). These sources were utilized to collect medical gas consumption statistics, USP/FDA approval data for medical gas specifications, clinical safety studies on hypoxia management, respiratory therapy procedural trends, and healthcare infrastructure deployment data for oxygen pipeline systems.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. The supply-side sources consisted of CEOs, VPs of Manufacturing Operations, regulatory affairs heads, quality assurance directors, and commercial directors from industrial gas manufacturers (medical grade), medical gas equipment OEMs (cylinder manufacturers, pipeline system integrators, manifold producers), and healthcare gas distribution companies. Demand-side sources included board-certified anesthesiologists, chiefs of respiratory care departments, critical care specialists, biomedical equipment managers, hospital procurement officers, emergency medical services (EMS) medical directors, and respiratory therapists in home healthcare. Primary research has confirmed the cryogenic vs. non-cryogenic technology pipelines, validated market segmentation across bulk oxygen, cylinder gas, and on-site generation systems, and gathered insights on clinical adoption patterns for portable oxygen concentrators, pricing strategies for long-term oxygen therapy (LTOT) contracts, and reimbursement dynamics for home medical gas equipment.

Primary Respondent Breakdown:

By Designation: C-level Primaries (30%), Director Level (35%), Others (35%)

•By Region: North America (32%), Europe (28%), Asia-Pacific (35%), Rest of World (5%)


Market Size Estimation

Global market valuation was derived through revenue mapping and medical gas consumption volume analysis. The methodology included:

Identification of 40+ key manufacturers across North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa

•Product mapping across medical gas categories (pure oxygen, medical air, nitrous oxide, carbon dioxide, helium/oxygen mixtures) and equipment segments (high-pressure cylinders, cryogenic liquid containers, centralized pipeline systems, gas manifolds, pressure regulators, flowmeters)

•Analysis of reported and modeled annual revenues specific to medical gas and equipment portfolios, distinguishing between bulk liquid gas delivery, packaged gas cylinder business, and on-site gas generation systems

•Coverage of manufacturers representing 75-80% of global market share in 2024

•Extrapolation using bottom-up (hospital bed count × average gas consumption per bed × ASP by country; home healthcare patient volumes × oxygen therapy device ASP) and top-down (industrial gas company medical segment revenue validation) approaches to derive segment-specific valuations for therapeutic gases, diagnostic gas mixtures, and anesthesia gases

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















