Medical Device Packaging Market (2026 - 2035)

ID: MRFR/PCM/1402-HCR 111 Pages Snehal Singh Last Updated: November 12, 2026
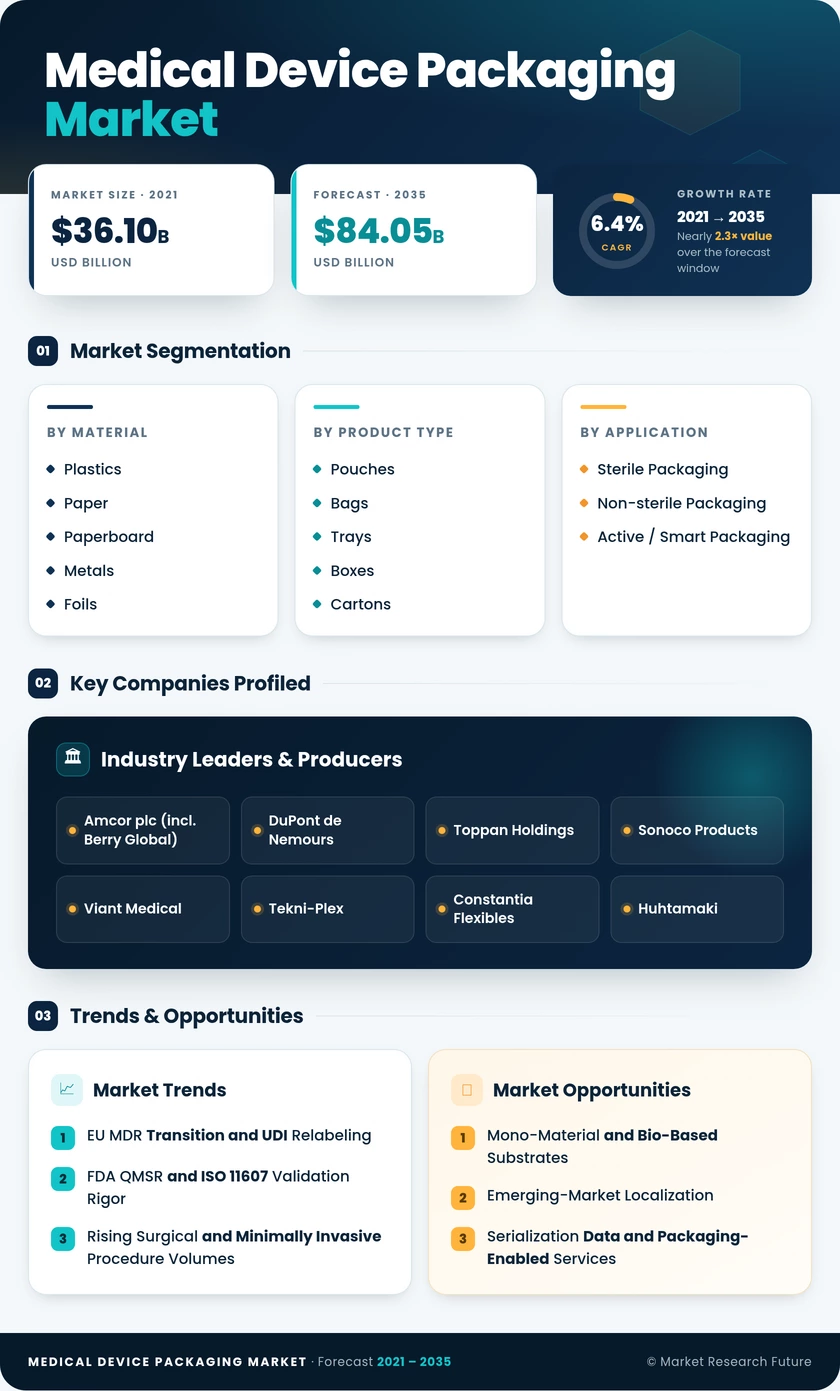
Medical Device Packaging Market Research Report Information By Material (Plastics, Paper and Paperboard, Metals and Foils, Glass, and Bio-Based Plastics), By Product Type (Pouches and Bags, Trays, Boxes and Cartons, Blister Packs, and Other Product Types), By Application (Sterile Packaging, Non-Sterile Packaging, and Active / Smart Packaging), By End User (Hospitals and Clinics, Diagnostic and Imaging Centers, Home Healthcare, and Contract Manufacturing and Sterilization Organizations), By Packaging Level (Primary, Secondary, and Tertiary), And By Region (North America, Europe, Asia-Pacific, and Rest of the World) – Market Forecast Till 2035.
Medical Device Packaging Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.4%
2025 Market SizeUSD 45.38 billion
2035 Market SizeUSD 84.05 billion
Key Players
Amcor plc
DuPont de Nemours
Toppan Holdings
Sonoco Products
Viant Medical
Tekni-Plex
Opportunities
  • Mono-Material and Bio-Based Substrates
  • Emerging-Market Localization
  • Serialization Data and Packaging-Enabled Services
  1. 1 Market Summary | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Material | |
    2. 2.2 By Product Type | |
    3. 2.3 By Application | |
    4. 2.4 By End User | |
    5. 2.5 By Packaging Level | |
    6. 2.6 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 EU MDR Transition and UDI Relabeling | |
    2. 4.2 FDA QMSR and ISO 11607 Validation Rigor | |
    3. 4.3 Rising Surgical and Minimally Invasive Procedure Volumes | |
    4. 4.4 OEM Outsourcing to Contract Manufacturers and Sterilizers | |
    5. 4.5 Smart Labeling, RFID and Traceability Mandates | |
    6. 4.6 Aging Populations and Home-Based Care | |
    7. 4.7 Asia-Pacific Manufacturing Incentives | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 EPA Ethylene Oxide Emission Standards | |
    2. 5.2 Resin and Substrate Price Volatility | |
    3. 5.3 Revalidation Cost and Lead Time for Pack Changes | |
    4. 5.4 Packaging Waste and Recyclability Rules | |
    5. 5.5 Concentrated Supply of Medical-Grade Substrates | |
  6. 6 Opportunities | |
    1. 6.1 Mono-Material and Bio-Based Substrates | |
    2. 6.2 Emerging-Market Localization | |
    3. 6.3 Serialization Data and Packaging-Enabled Services | |
    4. 6.4 Home-Healthcare-Ready Formats | |
    5. 6.5 Turnkey Design-to-Sterilization Programs | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 United States | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 United Kingdom | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Russia | | |
      7. 7.2.7 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 Australia and New Zealand | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 Middle East and Africa | | |
      1. 7.4.1 Middle East | | |
      2. 7.4.2 United Arab Emirates | | |
      3. 7.4.3 Saudi Arabia | | |
      4. 7.4.4 Turkey | | |
      5. 7.4.5 Rest of Middle East | | |
      6. 7.4.6 Africa | | |
      7. 7.4.7 South Africa | | |
      8. 7.4.8 Nigeria | | |
      9. 7.4.9 Egypt | | |
      10. 7.4.10 Rest of Africa | |
    5. 7.5 South America | | |
      1. 7.5.1 Brazil | | |
      2. 7.5.2 Argentina | | |
      3. 7.5.3 Rest of South America | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 AI-Driven Inspection and Digital Validation | |
    2. 8.2 Platform Consolidation and Scale Economics | |
    3. 8.3 Circularity and Sustainability Reporting | |
    4. 8.4 Decentralized Care and Direct-to-Patient Delivery | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Material | | |
      1. 9.1.1 Plastics | | |
      2. 9.1.2 Paper and Paperboard | | |
      3. 9.1.3 Metals and Foils | | |
      4. 9.1.4 Glass | | |
      5. 9.1.5 Bio-based Plastics | |
    2. 9.2 By Product Type | | |
      1. 9.2.1 Pouches and Bags | | |
      2. 9.2.2 Trays | | |
      3. 9.2.3 Boxes and Cartons | | |
      4. 9.2.4 Blister Packs | | |
      5. 9.2.5 Other Product Types | |
    3. 9.3 By Application | | |
      1. 9.3.1 Sterile Packaging | | |
      2. 9.3.2 Non-sterile Packaging | | |
      3. 9.3.3 Active / Smart Packaging | |
    4. 9.4 By End User | | |
      1. 9.4.1 Hospitals and Clinics | | |
      2. 9.4.2 Diagnostic and Imaging Centers | | |
      3. 9.4.3 Home Healthcare | | |
      4. 9.4.4 Contract Manufacturing and Sterilization Orgs | |
    5. 9.5 By Packaging Level | | |
      1. 9.5.1 Primary | | |
      2. 9.5.2 Secondary | | |
      3. 9.5.3 Tertiary | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis | |
    2. 10.2 Competitive Benchmarking Matrix | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Global Market Size and Forecast, by Revenue (USD billion), 2021–2035 | |
  16. TABLE 2 Driver Impact Analysis, 2026–2035 | |
  17. TABLE 3 Restraints Impact Analysis, 2026–2035 | |
  18. TABLE 4 Regional Summary, by Region, 2025 | |
  19. TABLE 5 North America Market, by Country, 2025 | |
  20. TABLE 6 Europe Market, by Country, 2025 | |
  21. TABLE 7 Asia-Pacific Market, by Country, 2025 | |
  22. TABLE 8 Middle East and Africa Market, by Country, 2025 | |
  23. TABLE 9 South America Market, by Country, 2025 | |
  24. TABLE 10 Global Market, by Material, 2025 | |
  25. TABLE 11 Global Market, by Product Type, 2025 | |
  26. TABLE 12 Global Market, by Application, 2025 | |
  27. TABLE 13 Global Market, by End User, 2025 | |
  28. TABLE 14 Global Market, by Packaging Level, 2025 | |
  29. TABLE 15 Competitive Benchmarking Matrix, 2025 | |
  30. TABLE 16 Report Scope and Methodology | |
  31. TABLE 17 Detailed Sources and Citations | |
  32. TABLE 18 Segmentation Quick Reference | | LIST OF FIGURES | |
  33. FIGURE 1 Market Dynamics Overview (Drivers, Restraints, Opportunities) | |
  34. FIGURE 2 Industry Value Chain Analysis | |
  35. FIGURE 3 Porter's Five Forces Analysis | |
  36. FIGURE 4 Global Market Size Trend, 2021–2035 (USD billion) | |
  37. FIGURE 5 Market Share, by Material, 2025 | |
  38. FIGURE 6 Market Share, by Product Type, 2025 | |
  39. FIGURE 7 Market Share, by Application, 2025 | |
  40. FIGURE 8 Market Share, by End User, 2025 | |
  41. FIGURE 9 Market Share, by Packaging Level, 2025 | |
  42. FIGURE 10 Regional Market Share, 2025 | |
  43. FIGURE 11 Competitive Landscape Positioning Matrix, 2025 | |
  44. FIGURE 12 Estimated Revenue Share Ranges of Key Players, 2025

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By MaterialPlastics; Paper and Paperboard; Metals and Foils; Glass; Bio-based PlasticsPlastics (58.6% share)Bio-based Plastics (11.4% CAGR)
By Product TypePouches and Bags; Trays; Boxes and Cartons; Blister Packs; Other Product TypesPouches and Bags (38.4% share)Boxes and Cartons (9.6% CAGR)
By ApplicationSterile Packaging; Non-sterile Packaging; Active / Smart PackagingSterile Packaging (70.3% share)Active / Smart Packaging (12.6% CAGR)
By End UserHospitals and Clinics; Diagnostic and Imaging Centers; Home Healthcare; Contract Manufacturing and Sterilization OrgsHospitals and Clinics (42.8% share)Contract Manufacturing and Sterilization Orgs (10.6% CAGR)
By Packaging LevelPrimary; Secondary; TertiaryPrimary (55.2% share)Tertiary (8.3% CAGR)
By RegionNorth America; Europe; Asia-Pacific; Middle East and Africa; South AmericaNorth America (37.8% share)Asia-Pacific (8.1% CAGR)

Market Segmentation Overview

By Material

Sub-SegmentKey Trend
PlasticsShift to cyclic olefin copolymers and co-extruded multilayer films
Paper and PaperboardBreathable lids and cost-efficient secondary cartons
Metals and FoilsHigh-barrier lidding for moisture-sensitive electronics
GlassGradual retreat from primary device containers
Bio-based PlasticsAdoption driven by hospital carbon scorecards

Plastics lead because engineered polymers survive gamma, electron-beam and steam cycles while allowing thermoformed and flexible designs that glass and metal cannot match. Bio-based Plastics grow fastest as European hospital tenders score embedded carbon and Asia-Pacific scales biopolymer output. Paper and Paperboard hold their place in breathable lids, while Metals and Foils remain the fallback where barrier performance is non-negotiable.

By Product Type

Sub-SegmentKey Trend
Pouches and BagsOptimized peel features for faster operating-room presentation
TraysCustom thermoformed cavities for scopes and implants
Boxes and CartonsRigid kits with breathable liners and inspection windows
Blister PacksCompact formats for strips, sutures and small components
Other Product TypesClamshells and tubes for niche device geometries

Pouches and Bags lead on versatility across catheters, syringes and other single-use disposables. Boxes and Cartons grow fastest because orthopedic and cardiovascular procedure kits need outer rigidity combined with breathable inner protection. Trays and Blister Packs fill specialized protective roles for delicate or very small devices.

By Application

Sub-SegmentKey Trend
Sterile PackagingGrowth in single-procedure kits and validated barrier formats
Non-sterile PackagingDurable equipment and analyzers disinfected on site.
Active / Smart PackagingOxygen scavengers, indicators and embedded sensors

Sterile Packaging leads because every implant and invasive instrument requires a validated microbial barrier through its labeled shelf life. Active / Smart Packaging grows fastest as sensors confirm cold-chain and shock compliance for battery-powered devices, reducing recall exposure. Non-sterile Packaging retains a stable role for hospital durables and diagnostic analyzers.

By End User

Sub-SegmentKey Trend
Hospitals and ClinicsCentralized procurement and high surgical throughput
Diagnostic and Imaging CentersTamper-evident packs for contrast agents and test kits
Home HealthcareEasy-open designs and large-print instructions for lay users
Contract Manufacturing and Sterilization OrgsStandardized formats for multi-customer production loads

Hospitals and Clinics lead on procedure volume and direct purchasing authority. Contract Manufacturing and Sterilization Orgs grow fastest as OEMs outsource capital-intensive packaging lines and focus spending on R&D. Home Healthcare is the next growth frontier, demanding patient-friendly opening features that differ sharply from clinician-oriented formats.

By Packaging Level

Sub-SegmentKey Trend
PrimaryValidated pouches and trays with laser-coded lot data
SecondaryUDI labeling and handling protection for global distribution
TertiaryCertified shippers with shock and temperature tracking

Primary leads because it carries the sterility function and the heaviest validation burden, giving it the highest value per unit. Tertiary grows fastest as OEMs consolidate kit shipments from Vietnam and Costa Rica and add traceability labels to shipper cartons. Secondary packs remain central to meeting UDI and multi-language labeling obligations.


Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.