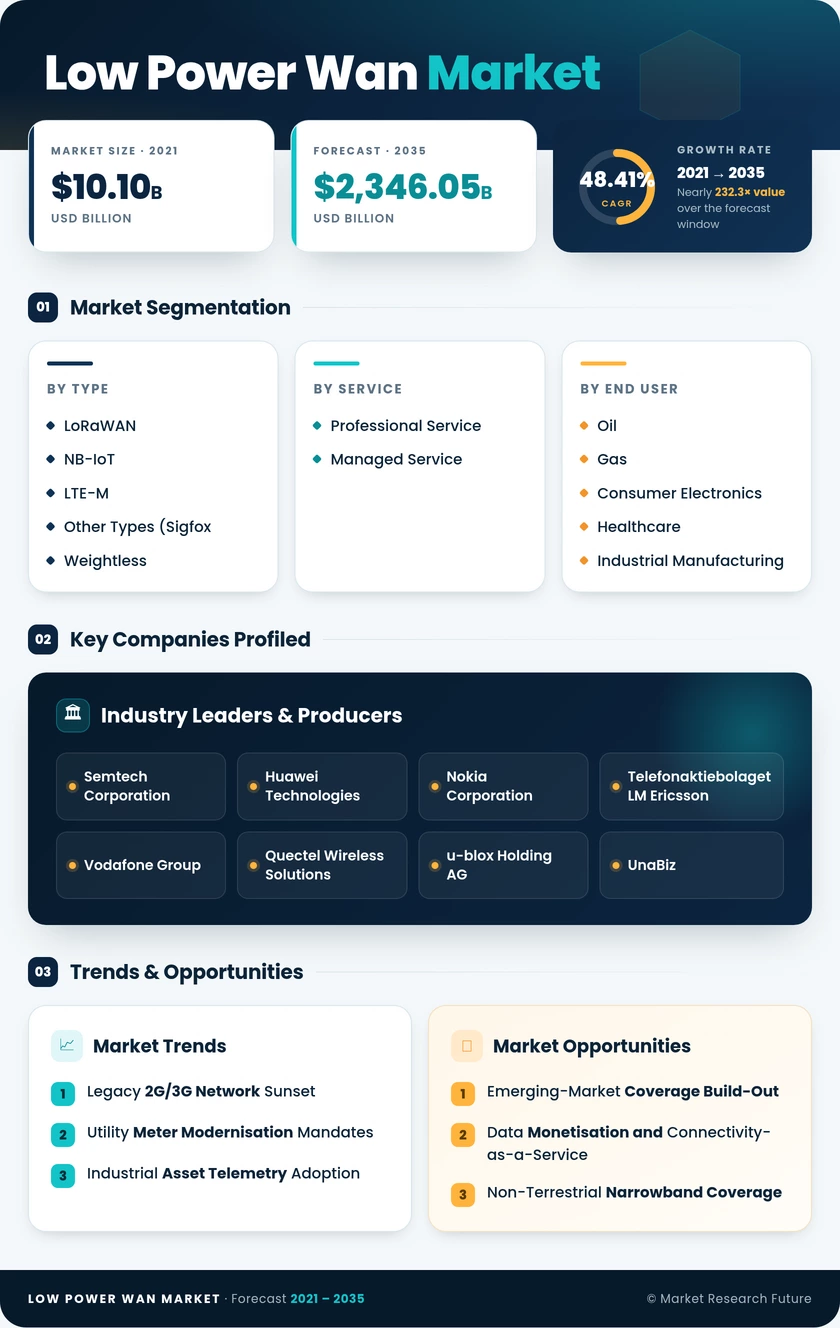
Market Segmentation Analysis
By Type
9.1.1 LoRaWAN
9.1.2 NB-IoT
9.1.3 LTE-M
9.1.4 Other Types (Sigfox, Weightless, etc.)
By Service
9.2.1 Professional Service
9.2.2 Managed Service
By End User
9.3.1 Oil and Gas
9.3.2 Consumer Electronics
9.3.3 Healthcare
9.3.4 Industrial Manufacturing
9.3.5 Logistics and Travelling
9.3.6 Other End Users
By Application
9.4.1 Smart Cities
9.4.2 Smart Homes/Buildings
9.4.3 Smart Agriculture
9.4.4 Other Applications
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Type | LoRaWAN; NB-IoT; LTE-M; Other Types (Sigfox, Weightless, etc.) | NB-IoT — USD 17.38 billion (2025) | LTE-M — 51.4% CAGR (2026–2035) |
| By Service | Professional Service; Managed Service | Professional Service — 57.3% share (2025) | Managed Service — 50.9% CAGR (2026–2035) |
| By End User | Oil and Gas; Consumer Electronics; Healthcare; Industrial Manufacturing; Logistics and Travelling; Other End Users | Industrial Manufacturing — 27.4% share (2025) | Healthcare — 52.6% CAGR (2026–2035) |
| By Application | Smart Cities; Smart Homes/Buildings; Smart Agriculture; Other Applications | Smart Cities — 34.6% share (2025) | Smart Agriculture — 53.8% CAGR (2026–2035) |
Market Segmentation Overview
By Type
| Sub-Segment | Key Trend |
| LoRaWAN | Private campus and municipal ownership models sustain share against carrier alternatives. |
| NB-IoT | Carrier bundling into utility and metering contracts drives the largest revenue pool. |
| LTE-M | Mobility handover and firmware delivery requirements pull tracking workloads upward. |
| Other Types (Sigfox, Weightless, etc.) | Ultra-low-cost tracking endpoints defend a niche on bill-of-materials price. |
NB-IoT leads this dimension because licensed spectrum lets carriers underwrite service levels that utility and municipal buyers require in tender documents, and because access is bundled into existing carrier relationships. LTE-M grows fastest as logistics and asset-tracking fleets need cell handover and over-the-air firmware updates that stationary narrowband profiles handle poorly. LoRaWAN retains a durable position wherever buyers insist on owning infrastructure outright, notably industrial campuses and university estates where recurring carrier fees are politically difficult to approve.
By Service
| Sub-Segment | Key Trend |
| Professional Service | RF planning, certification and backend integration dominate first-time deployment spend. |
| Managed Service | Per-endpoint monthly pricing converts capital requests into operating budgets. |
Professional Service holds the larger share because organisations deploying for the first time lack in-house radio planning and integration capability, and consultants absorb the site survey, gateway siting and application middleware workload. Managed Service is the faster-growing sub-segment as deployment patterns standardise and vendors package devices, network operations and dashboards into a single recurring fee. Mid-size municipalities and manufacturers drive that shift, since an operating expense line clears approval thresholds that a multi-year capital request would not.
By End User
| Sub-Segment | Key Trend |
| Oil and Gas | Wellhead, pipeline and methane monitoring where no alternative connectivity exists |
| Consumer Electronics | Trackers and appliance connectivity constrained by module cost sensitivity |
| Healthcare | Remote monitoring reimbursement and cold-chain custody evidence requirements |
| Industrial Manufacturing | Condition monitoring retrofits underwritten by measurable downtime reduction. |
| Logistics and Travelling | Container, trailer and pallet visibility across multi-carrier journeys |
| Other End Users | Public sector, education and retail estate sensing |
Industrial Manufacturing is the largest vertical because condition-monitoring retrofits produce downtime savings that plant finance teams can quantify and approve without corporate escalation. Healthcare expands fastest, driven by reimbursement changes for continuous patient monitoring and by cold-chain rules that demand temperature evidence at every custody handoff rather than at delivery alone. Oil and Gas remains structurally important because remote wellheads and pipeline segments have no economical wired or broadband alternative, making narrowband telemetry the default rather than a comparative choice.
By Application
| Sub-Segment | Key Trend |
| Smart Cities | Public infrastructure programmes fund streetlight, parking, waste and water telemetry |
| Smart Homes/Buildings | Energy codes drive sub-metering and occupancy analytics adoption. |
| Smart Agriculture | Subsidy-linked eco-schemes reimburse soil, irrigation and livestock monitoring. |
| Other Applications | Structural and environmental monitoring on public assets |
Smart Cities leads because municipal programmes in India, the European Union and the United States finance sensing infrastructure directly, removing the payback debate that private buyers must resolve internally. Smart Agriculture grows fastest from a smaller base, as agricultural policy now reimburses monitoring equipment and dispersed unpowered field sites leave long-range low-bitrate radio as the only workable option. Smart Homes/Buildings convert more steadily, pulled by building energy codes that require sub-metered consumption evidence rather than estimated allocation.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA