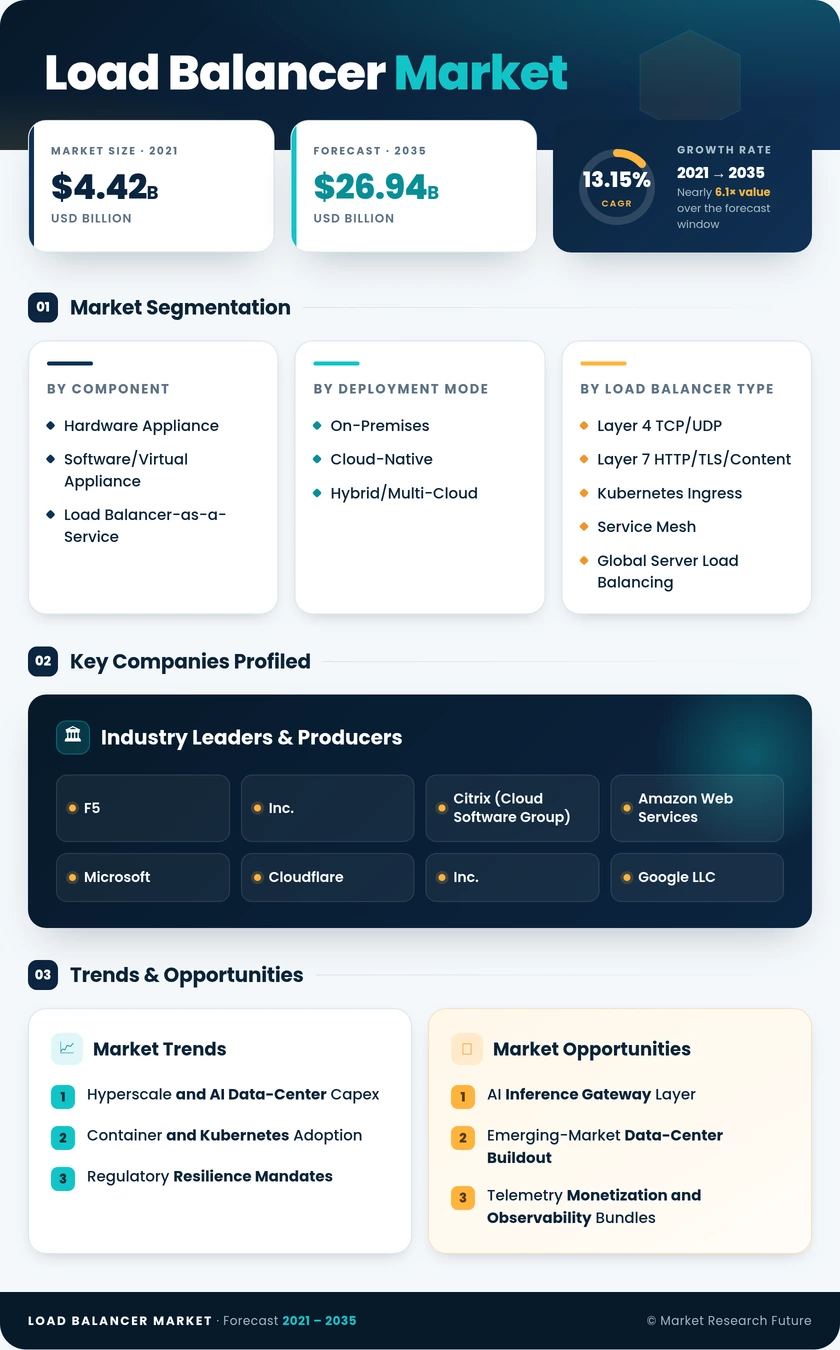
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Component | Hardware Appliance; Software/Virtual Appliance; Load Balancer-as-a-Service | Software/Virtual Appliance (64.8% share, 2025) | Load Balancer-as-a-Service (16.6% CAGR) |
| By Deployment Mode | On-Premises; Cloud-Native; Hybrid/Multi-Cloud | On-Premises (USD 4.13 Billion, 2025) | Cloud-Native (16.3% CAGR) |
| By Load Balancer Type | Layer 4 TCP/UDP; Layer 7 HTTP/TLS/Content; Kubernetes Ingress and Service Mesh; Global Server Load Balancing; DNS-Based Load Balancing | Layer 7 HTTP/TLS/Content (53.5% share, 2025) | Kubernetes Ingress and Service Mesh (15.9% CAGR) |
| By End-User Industry | IT and Telecom; BFSI; Healthcare and Life Sciences; Retail and E-Commerce; Government and Public Sector; Media and Entertainment | IT and Telecom (USD 2.42 Billion, 2025) | Healthcare and Life Sciences (16.8% CAGR) |
Market Segmentation Overview
By Component
| Sub-Segment | Key Trend |
| Hardware Appliance | Retained in exchange colocation and telco packet cores; smart-NIC offload narrowing the determinism advantage |
| Software/Virtual Appliance | Marketplace and container-registry distribution collapsing provisioning from quarters to minutes |
| Load Balancer-as-a-Service | Bundled WAF, bot mitigation, and DDoS scrubbing turning delivery into a security upsell channel |
Software/Virtual Appliance leads this dimension at 64.8% of 2025 revenue because platform teams buy capacity they can resize, not chassis they must forecast three years ahead. Load Balancer-as-a-Service grows fastest at 16.6% CAGR, since consumption billing matches API traffic that no capacity plan can predict. Hardware Appliance holds only where microsecond determinism is contractual — exchange matching engines and carrier packet cores — and that perimeter shrinks each time programmable NICs absorb another offload function.
By Deployment Mode
| Sub-Segment | Key Trend |
| On-Premises | Seven- to nine-year chassis amortization in banking and government delaying replacement |
| Cloud-Native | Managed Kubernetes expansion adding an ingress control point per cluster |
| Hybrid/Multi-Cloud | Portable policy configurations becoming the primary vendor selection criterion |
On-Premises still carries the largest revenue base at USD 4.13 billion because regulated buyers must keep sensitive records in-house and meet deterministic latency floors. Cloud-Native expands fastest at 16.3% CAGR, tracking container orchestration adoption almost one-for-one as each new cluster requires its own ingress path. Hybrid/Multi-Cloud is where selection criteria are actually decided: enterprises pairing sovereign private estates with public endpoints reward vendors whose rule sets migrate between environments without rewriting.
By Load Balancer Type
| Sub-Segment | Key Trend |
| Layer 4 TCP/UDP | Sustained in financial exchanges prioritizing deterministic latency over application awareness |
| Layer 7 HTTP/TLS/Content | Host-header routing, SSL termination, and content rewriting remaining non-negotiable for commerce |
| Kubernetes Ingress and Service Mesh | Envoy-based gateways holding low-latency behavior under bursty microservices traffic |
| Global Server Load Balancing | Sovereign cloud region rollouts widening geographic failover requirements |
| DNS-Based Load Balancing | Simple round-robin distribution persisting for cost-constrained estates |
Layer 7 HTTP/TLS/Content dominates at 53.5% share because e-commerce, streaming, and API monetization all depend on content-aware routing decisions that Layer 4 cannot make. Kubernetes Ingress and Service Mesh grows fastest at 15.9% CAGR as microservices estates multiply control points per application. Layer 4 TCP/UDP is not disappearing — matching engines still buy determinism over inspection — while Global Server Load Balancing gains as SaaS vendors open sovereign regions requiring cross-region health arbitration.
By End-User Industry
| Sub-Segment | Key Trend |
| IT and Telecom | 5G standalone slicing and private campus networks offsetting commoditized traffic steering |
| BFSI | Resilience mandates requiring documented failover evidence at every application boundary |
| Healthcare and Life Sciences | Telehealth and PACS imaging generating bursty, encryption-heavy loads |
| Retail and E-Commerce | Peak-season concurrency driving elastic capacity contracting |
| Government and Public Sector | Cloud-first procurement rules reshaping citizen portal architecture |
| Media and Entertainment | Live streaming concurrency demanding high-fanout distribution |
IT and Telecom remains the largest vertical at USD 2.42 billion, sustained by carrier-grade NAT estates and CDN-adjacent infrastructure, though basic steering has commoditized enough that growth now depends on 5G slicing. Healthcare and Life Sciences accelerates hardest at 16.8% CAGR: HL7/FHIR API traffic and imaging archives create bursty loads that demand audit-ready policy logging and HIPAA-grade encryption at every hop. BFSI sits between them, buying premium configurations because flash-crash exposure makes downtime a regulatory event rather than an operational one.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA