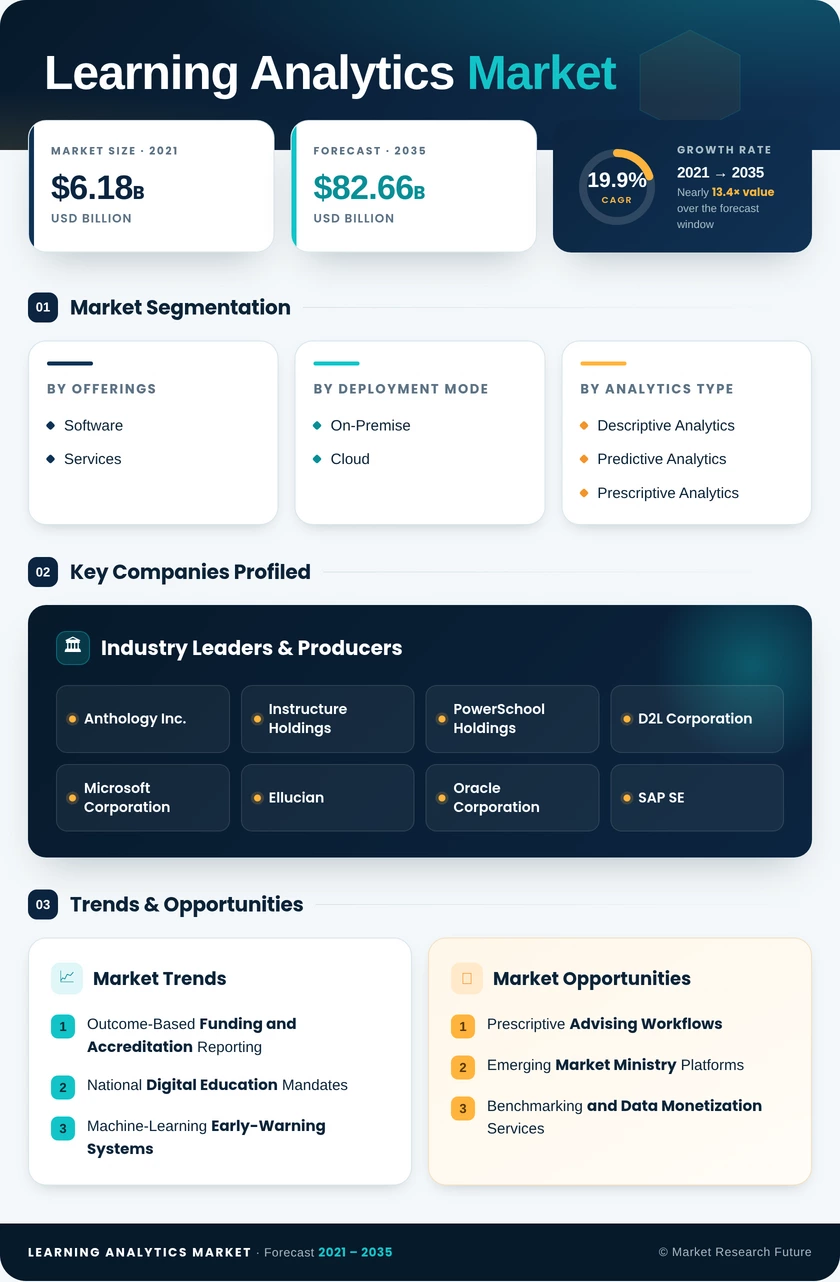
Market Segmentation Analysis
By Offerings
9.1.1 Software
9.1.2 Services
By Deployment Mode
9.2.1 On-Premise
9.2.2 Cloud
By Analytics Type
9.3.1 Descriptive Analytics
9.3.2 Predictive Analytics
9.3.3 Prescriptive Analytics
By Application
9.4.1 Performance Management and Student Success
9.4.2 Curriculum and Course Development
9.4.3 Other Applications
By End User
9.5.1 Academia
9.5.2 Corporate
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Offerings | Software; Services | Software (64.24% share, 2025) | Services (21.4% CAGR) |
| By Deployment Mode | On-Premise; Cloud | On-Premise (66.83% share, 2025) | Cloud (21.8% CAGR) |
| By Analytics Type | Descriptive Analytics; Predictive Analytics; Prescriptive Analytics | Predictive Analytics (USD 7.24 billion, 2025) | Prescriptive Analytics (20.8% CAGR) |
| By Application | Performance Management and Student Success; Curriculum and Course Development; Other Applications | Performance Management and Student Success (46.29% share, 2025) | Curriculum and Course Development (20.2% CAGR) |
| By End User | Academia; Corporate | Academia (63.16% share, 2025) | Corporate (USD 4.92 billion, 2025 base; fastest-expanding end user) |
Market Segmentation Overview
By Offerings
| Sub-Segment | Key Trend |
| Software | Analytics increasingly bundled into core platform licenses rather than sold standalone. |
| Services | Managed model tuning and compliance updates shifting to multi-year outcome contracts |
Software holds the leading position at 64.24% of 2025 revenue because institutions buy analytics inside existing platform agreements, where predictive analytics tools carry the highest per-seat value. Services grow faster at 21.4% because ingesting data from a student information system, a learning platform, and an advising tool exceeds what most campus IT teams can staff. Buyers now expect vendors to guarantee retention outcomes, which converts one-time implementations into recurring managed engagements.
By Deployment Mode
| Sub-Segment | Key Trend |
| On-Premise | Sustained by national data-residency rules governing student records |
| Cloud | Hybrid architectures keeping identifiers local while modeling runs remotely |
On-premise leads with 66.83% share because ministries and public universities in Europe, China, and India frequently mandate domestic hosting of learner records. Cloud grows fastest at 21.8% as subscription pricing removes the capital barrier for community colleges and school districts, and because feature release cycles are measurably shorter. The hybrid compromise now dominates new tenders, letting legal review approve deployments that would otherwise stall for months.
By Analytics Type
| Sub-Segment | Key Trend |
| Descriptive Analytics | Foundational compliance reporting, stable but low-growth |
| Predictive Analytics | Risk scoring refreshed weekly rather than at term end. |
| Prescriptive Analytics | Recommendation engines moving from pilot to production. |
Predictive analytics is the largest pool at USD 7.24 billion in 2025, since early identification of at-risk learners produces the clearest return against completion-linked funding. Prescriptive analytics grows fastest at 20.8% because advisors want recommended tutoring schedules and course substitutions, not additional alerts to triage. Descriptive analytics is neither leader nor laggard in growth terms; it persists as the reporting substrate that regulators require and that the other two layers depend upon.
By Application
| Sub-Segment | Key Trend |
| Performance Management and Student Success | Advisor dashboards tied directly to retention funding formulas |
| Curriculum and Course Development | Course-level outcome data driving program redesign and bottleneck removal |
| Other Applications | Assessment analytics and adaptive testing feeding data back into design loops |
Performance management and student success leads at 46.29% share because graduation and retention metrics carry direct budgetary consequences under performance-based appropriations in North America and quality assurance frameworks in Europe. Curriculum and course development expands fastest at 20.2% as provosts apply completion data to eliminate duplicate offerings and redesign gateway courses. Other applications, principally assessment analytics, supply the granular item-level evidence that makes curriculum decisions defensible to faculty governance.
By End User
| Sub-Segment | Key Trend |
| Academia | Accreditation evidence requirements formalizing analytics as infrastructure |
| Corporate | Training spend increasingly measured against productivity and retention outcomes. |
Academia dominates with 63.16% of 2025 revenue because universities and K-12 schools hold decades of longitudinal records that make cohort modeling viable, and because accreditors require documented improvement cycles. Corporate is the fastest-growing end user, generating USD 4.92 billion in 2025 and rising as chief learning officers face the same return scrutiny as other cost centers. Large enterprises adopt through talent-management suites, while smaller firms enter via cloud subscriptions that were economically out of reach a few years ago.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA