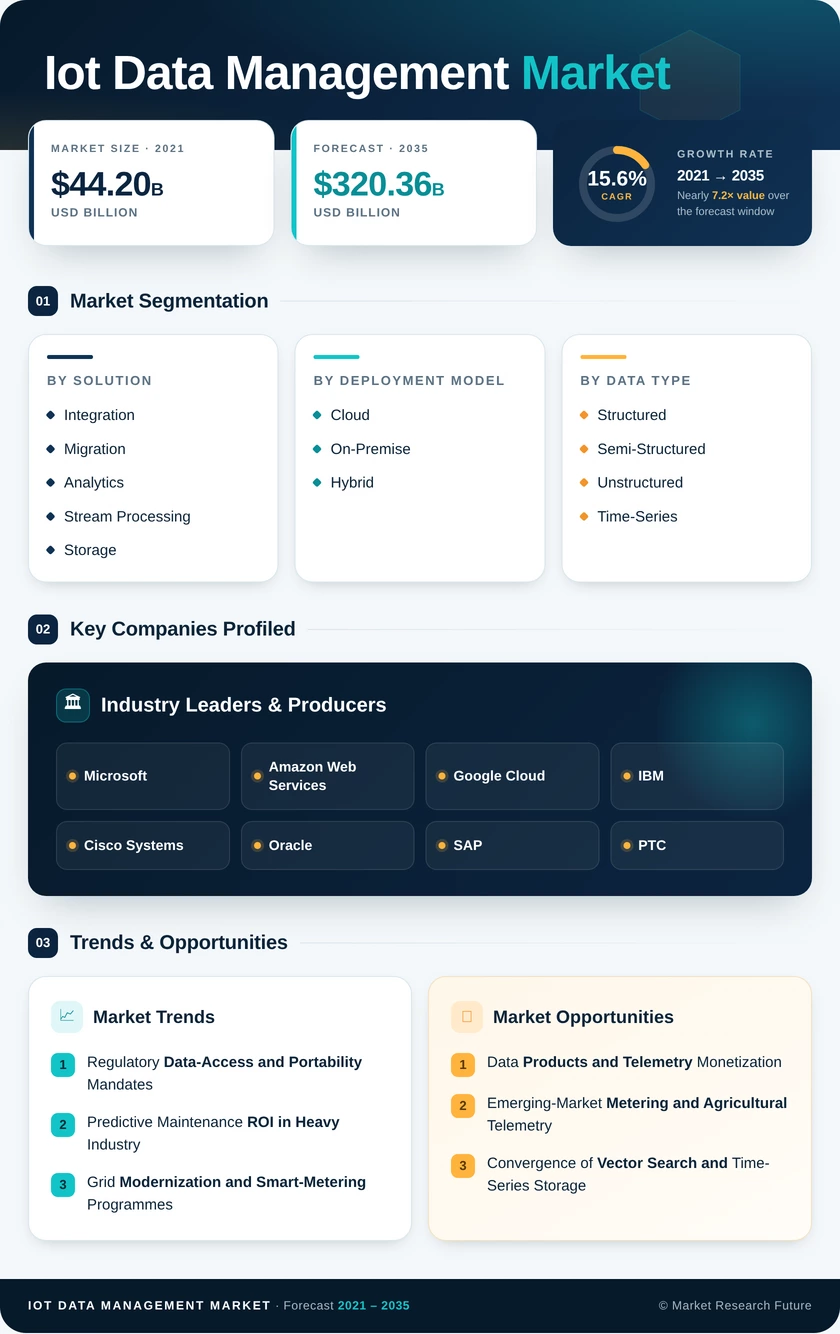
IoT Data Management Market

ID: MRFR/ICT/5817-HCR 100 Pages Kiran Jinkalwad Last Updated: September 08, 2026
IoT Data Management Market Size, Share and Research Report By Solution (Integration, Migration, Analytics, Stream Processing, Storage, and Security), By Deployment Model (Cloud, On-Premise, and Hybrid), By Data Type (Structured, Semi-Structured, Unstructured, and Time-Series), By End-User Industry (Automotive and Transportation, Agriculture, BFSI, Manufacturing and Industrial, Healthcare and Life Sciences, Government and Smart Cities, Energy and Utilities, and Retail), By Application (Predictive Maintenance, Smart Metering, Smart Grid Analytics, Asset Tracking and Fleet Management, and Remote Patient Monitoring) – Industry Forecast Till 2035
IoT Data Management Market
Market Size
CAGR (Growth)15.6%
Key Players
Microsoft
Amazon Web Services
Google Cloud
IBM
Cisco Systems
Oracle
Opportunities
  • Data Products and Telemetry Monetization
  • Emerging-Market Metering and Agricultural Telemetry
  • Convergence of Vector Search and Time-Series Storage
  1. 1 Market Summary | |
    1. 1.1 Study Assumptions and Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Solution | |
    2. 2.2 By Deployment Model | |
    3. 2.3 By Data Type | |
    4. 2.4 By End-User Industry | |
    5. 2.5 By Application | |
    6. 2.6 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2024) | |
    2. 3.2 Base Year Assessment (2025) | |
    3. 3.3 Forecast Market Size (2026–2035) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Regulatory Data-Access and Portability Mandates | |
    2. 4.2 Predictive Maintenance ROI in Heavy Industry | |
    3. 4.3 Grid Modernization and Smart-Metering Programmes | |
    4. 4.4 Generative AI Demand for Governed Training Corpora | |
    5. 4.5 5G and Low-Power Connectivity Expansion | |
    6. 4.6 Healthcare Remote Monitoring Reimbursement | |
    7. 4.7 Sustainability and Emissions Disclosure Rules | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Legacy Protocol and Brownfield Integration Cost | |
    2. 5.2 Data Sovereignty and Cross-Border Residency Limits | |
    3. 5.3 Cybersecurity Exposure Across Distributed Endpoints | |
    4. 5.4 Shortage of Telemetry and Data-Engineering Talent | |
    5. 5.5 Unclear ROI Attribution on Early-Stage Deployments | |
  6. 6 Opportunities | |
    1. 6.1 Data Products and Telemetry Monetization | |
    2. 6.2 Emerging-Market Metering and Agricultural Telemetry | |
    3. 6.3 Convergence of Vector Search and Time-Series Storage | |
    4. 6.4 Sovereign and Regulated-Industry Hybrid Deployments | |
    5. 6.5 Outcome-Priced Managed Services | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 United States | | |
      2. 7.1.2 Canada | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 United Kingdom | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East and Africa | | |
      1. 7.5.1 United Arab Emirates | | |
      2. 7.5.2 Saudi Arabia | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Rest of Middle East and Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Autonomous Operations and Agentic Analytics | |
    2. 8.2 Platform Economics and Consolidation | |
    3. 8.3 Energy Systems and the Distributed Grid | |
    4. 8.4 Audit-Grade Sustainability and Provenance Data | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Solution | | |
      1. 9.1.1 Integration | | |
      2. 9.1.2 Migration | | |
      3. 9.1.3 Analytics | | |
      4. 9.1.4 Stream Processing | | |
      5. 9.1.5 Storage | | |
      6. 9.1.6 Security | |
    2. 9.2 By Deployment Model | | |
      1. 9.2.1 Cloud | | |
      2. 9.2.2 On-Premise | | |
      3. 9.2.3 Hybrid | |
    3. 9.3 By Data Type | | |
      1. 9.3.1 Structured | | |
      2. 9.3.2 Semi-Structured | | |
      3. 9.3.3 Unstructured | | |
      4. 9.3.4 Time-Series | |
    4. 9.4 By End-User Industry | | |
      1. 9.4.1 Automotive and Transportation | | |
      2. 9.4.2 Agriculture | | |
      3. 9.4.3 BFSI | | |
      4. 9.4.4 Manufacturing and Industrial | | |
      5. 9.4.5 Healthcare and Life Sciences | | |
      6. 9.4.6 Government and Smart Cities | | |
      7. 9.4.7 Energy and Utilities | | |
      8. 9.4.8 Retail | |
    5. 9.5 By Application | | |
      1. 9.5.1 Predictive Maintenance | | |
      2. 9.5.2 Smart Metering | | |
      3. 9.5.3 Smart Grid Analytics | | |
      4. 9.5.4 Asset Tracking and Fleet Management | | |
      5. 9.5.5 Remote Patient Monitoring | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis (2025) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | |
  11. 11 Recent News and Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions | | LIST OF TABLES | |
  15. TABLE 1 Global IoT Data Management Market Size and Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Global IoT Data Management Market — Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 | |
  19. TABLE 5 Global IoT Data Management Market Size, by Region, 2021–2035 (USD Billion) | |
  20. TABLE 6 North America Market Size, by Country, 2021–2035 (USD Billion) | |
  21. TABLE 7 Europe Market Size, by Country, 2021–2035 (USD Billion) | |
  22. TABLE 8 Asia-Pacific Market Size, by Country, 2021–2035 (USD Billion) | |
  23. TABLE 9 South America Market Size, by Country, 2021–2035 (USD Billion) | |
  24. TABLE 10 Middle East and Africa Market Size, by Country, 2021–2035 (USD Billion) | |
  25. TABLE 11 Global Market Size, by Solution, 2021–2035 (USD Billion) | |
  26. TABLE 12 Global Market Size, by Deployment Model, 2021–2035 (USD Billion) | |
  27. TABLE 13 Global Market Size, by Data Type, 2021–2035 (USD Billion) | |
  28. TABLE 14 Global Market Size, by End-User Industry, 2021–2035 (USD Billion) | |
  29. TABLE 15 Global Market Size, by Application, 2021–2035 (USD Billion) | |
  30. TABLE 16 Competitive Benchmarking Matrix, 2025 | |
  31. TABLE 17 Company Profiles — Key Players | |
  32. TABLE 18 Recent Developments and Strategic Announcements, 2023–2025 | |
  33. TABLE 19 Report Scope and Methodology Summary | |
  34. TABLE 20 Detailed Sources and Citations Index | | LIST OF FIGURES | |
  35. FIGURE 1 Market Dynamics Overview — Drivers, Restraints, Opportunities | |
  36. FIGURE 2 Industry Value Chain Analysis | |
  37. FIGURE 3 Porter's Five Forces Analysis | |
  38. FIGURE 4 Global Market Size Trend and Forecast, 2021–2035 | |
  39. FIGURE 5 Year-over-Year Growth Trajectory, 2022–2035 | |
  40. FIGURE 6 Revenue Share by Solution, 2025 | |
  41. FIGURE 7 Revenue Share by Deployment Model, 2025 | |
  42. FIGURE 8 Revenue Share by Data Type, 2025 | |
  43. FIGURE 9 Revenue Share by End-User Industry, 2025 | |
  44. FIGURE 10 Revenue Share by Application, 2025 | |
  45. FIGURE 11 Regional Revenue Share, 2025 versus 2035 | |
  46. FIGURE 12 Asia-Pacific Country-Level Growth Comparison, 2026–2035 | |
  47. FIGURE 13 Competitive Landscape Positioning Map, 2025 | |
  48. FIGURE 14 Vendor Revenue Share Distribution, 2025

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By SolutionIntegration, Migration, Analytics, Stream Processing, Storage, SecurityAnalytics (33.9% share, 2025)Stream Processing (15.7% CAGR)
By Deployment ModelCloud, On-Premise, HybridCloud (65.4% share, 2025)Hybrid (15.9% CAGR)
By Data TypeStructured, Semi-Structured, Unstructured, Time-SeriesTime-Series (44.8% share, 2025)Unstructured (15.7% CAGR)
By End-User IndustryAutomotive and Transportation, Agriculture, BFSI, Manufacturing and Industrial, Healthcare and Life Sciences, Government and Smart Cities, Energy and Utilities, RetailManufacturing and Industrial (29.1% share, 2025)Healthcare and Life Sciences (16.0% CAGR)
By ApplicationPredictive Maintenance, Smart Metering, Smart Grid Analytics, Asset Tracking and Fleet Management, Remote Patient MonitoringPredictive Maintenance (26.1% share, 2025)Asset Tracking and Fleet Management (15.8% CAGR)


Market Segmentation Overview

By Solution

Sub-SegmentKey Trend
IntegrationGateway normalization across Modbus, OPC UA, and proprietary industrial buses
MigrationHistorian-to-time-series replacement projects entering second wave
AnalyticsAnomaly and utilization dashboards extended to frontline operators
Stream ProcessingContinuous evaluation replacing scheduled batch review
StorageTiered retention with compression tuned for high-cardinality series
SecurityCertification evidence becoming a procurement gate rather than an add-on


Analytics leads this dimension because insight generation, not retention, is what operations directors can defend in a capital review; dashboards that flag a failing bearing pay for themselves in one avoided outage. Stream Processing grows fastest as line-side quality rejection and fleet rerouting demand sub-second evaluation that scheduled jobs cannot deliver. Integration stays commercially significant despite slower growth, since brownfield estates running decades-old fieldbus protocols still require translation before any other solution in this dimension can function.

By Deployment Model

Sub-SegmentKey Trend
CloudElastic GPU capacity for model training on retained telemetry
On-PremisePersistent demand from air-gapped and latency-critical control loops
HybridEdge filtering paired with centralized governance and reporting


Cloud holds dominant share because opex pricing and elastic compute suit AI-intensive workloads that no single plant can justify buying hardware for. Hybrid grows fastest as residency statutes and control-loop latency make full centralization impossible for utilities, hospitals, and defence contractors. On-Premise does not disappear — it stabilizes as a specialized tier serving facilities where network egress is prohibited outright, which is a smaller but durable buyer base than the cloud-only narrative suggested five years ago.

By Data Type

Sub-SegmentKey Trend
StructuredTelemetry joined against ERP work orders and asset registries
Semi-StructuredJSON gateway payloads with evolving field schemas
UnstructuredMachine vision, acoustic, and clinical narrative capture
Time-SeriesHigh-cardinality numeric series from SCADA and metering estates


Time-Series dominates because industrial instrumentation has emitted periodic numeric readings for decades, and those archives must be retained for condition-based programmes to function. Unstructured data grows fastest as vision inspection and acoustic leak detection generate payloads that numeric engines cannot index, forcing platform buyers to evaluate vector search capability alongside series compression. Semi-Structured payloads complicate both, since gateway firmware updates change field names without warning and schema drift breaks downstream queries silently.

By End-User Industry

Sub-SegmentKey Trend
Automotive and TransportationCellular vehicle fleets migrating to managed control centres
AgricultureSoil moisture and machinery telemetry linked to subsidy verification
BFSIUsage-based insurance pricing drawn from operational telemetry
Manufacturing and IndustrialCondition-based maintenance replacing calendar schedules
Healthcare and Life SciencesRemote physiologic monitoring under recurring reimbursement
Government and Smart CitiesUnified municipal sensor platforms replacing departmental silos
Energy and UtilitiesInterval metering supporting dynamic tariffs and demand response
RetailCold-chain custody documentation and shelf-level inventory sensing


Manufacturing and Industrial leads on share because downtime carries a price that finance teams can verify, making approval routine rather than exceptional. Healthcare and Life Sciences grows fastest as reimbursement policy converts remote monitoring into recurring provider revenue and as decentralized trial designs require continuous, auditable endpoint capture. Automotive and Transportation contributes heavy absolute volume through telematics migrations measured in millions of vehicles, though its data is comparatively uniform and therefore cheaper per record to manage than regulated clinical streams.

By Application

Sub-SegmentKey Trend
Predictive MaintenanceMulti-year vibration and thermal history retained for model training
Smart MeteringMonthly reads replaced by interval data across national grids
Smart Grid AnalyticsFeeder-level visibility for distributed solar and storage integration
Asset Tracking and Fleet ManagementCustody documentation tightening across pharma and food logistics
Remote Patient MonitoringChronic-condition management under value-based care contracts


Predictive Maintenance anchors this dimension because it produces the cleanest measurable comparison available — outage hours before versus after — which is why it remains the entry use case for most first-time buyers. Asset Tracking and Fleet Management grows fastest as pharmaceutical and food shippers face stricter custody evidence requirements and insurers begin pricing directly from movement and temperature records. Smart Metering delivers the largest single volume of new records, though its per-record analytical value is lower than the maintenance and clinical applications competing for the same platform budget.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.