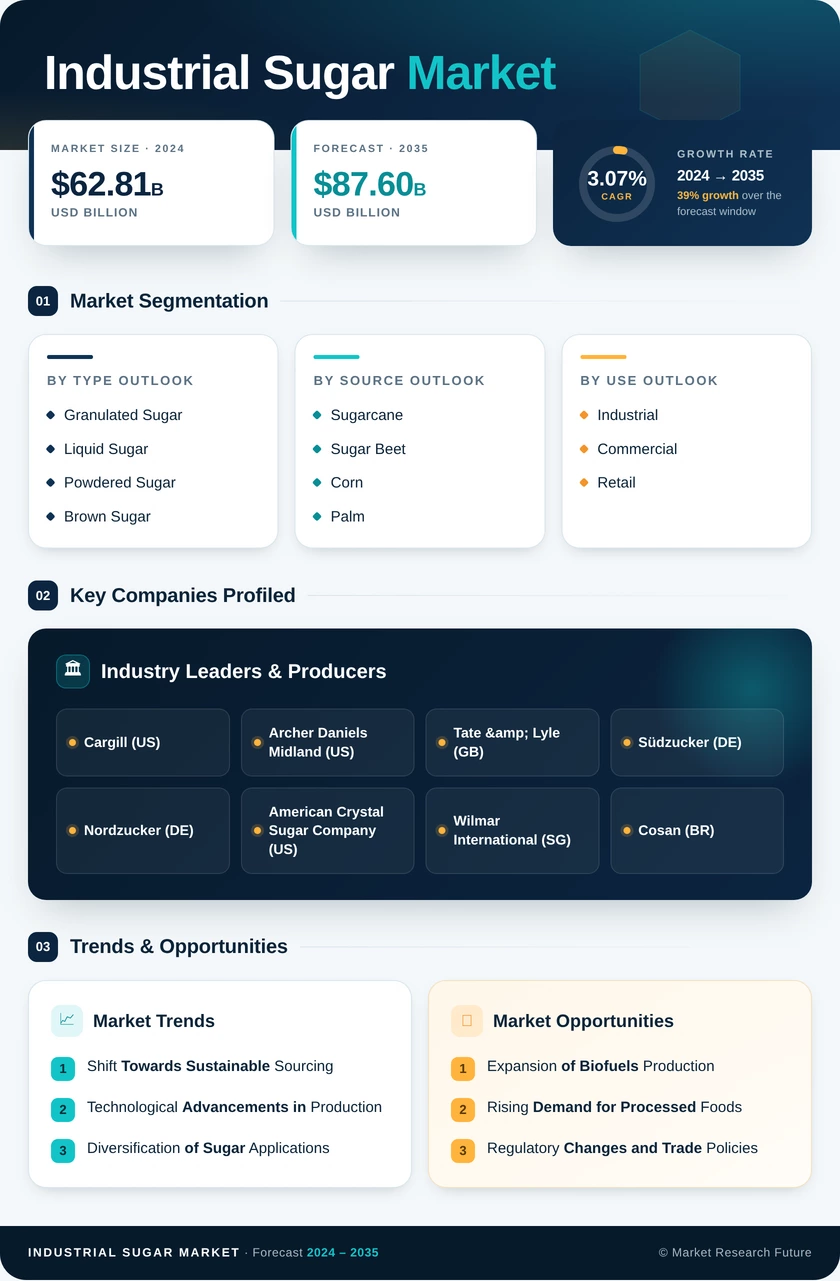
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Product Type | White Refined Sugar, Brown Sugar, Specialty Sugars | White Refined Sugar | Specialty Sugars |
| By Form | Granulated, Powdered/Icing, Syrup | Granulated | Powdered/Icing |
| By Source | Cane Sugar, Beet Sugar | Cane Sugar | Beet Sugar |
| By Application | Bakery and Confectionery, Dairy and Frozen Desserts, Beverages, Pharmaceuticals, Personal Care and Cosmetics, Others | Beverages | Bakery and Confectionery |
| By Geography | North America, Europe, Asia-Pacific, South America, Middle East & Africa | Asia-Pacific | South America |
Market Segmentation Overview
By Product Type
| Sub-Segment | Key Trend |
| White Refined Sugar | Tight ICUMSA colour and ash specifications keep it locked into beverage and confectionery contracts. |
| Brown Sugar | Steady demand from sauces, bakery, and Asian processed-food manufacturing |
| Specialty Sugars | Certification, provenance, and flavour differentiation command 30–60% price premiums |
Product-type economics are diverging rather than converging. White refined competes almost purely on delivered cost per tonne against a futures benchmark, while specialty grades sell on attributes that resist commoditisation — which is why processors are retrofitting multi-grade capability onto existing refining trains rather than adding bulk capacity.
By Form
| Sub-Segment | Key Trend |
| Granulated | Bulk silo and tanker infrastructure sustains its handling advantage at scale. |
| Powdered / Icing | Growth from confectionery coatings, frostings, and dry-mix convenience products |
| Syrup | Beverage bottlers eliminate dissolution steps and improve dosing accuracy. |
Form choice is an engineering decision more than a commercial one. Manufacturers select based on installed handling infrastructure, and switching carries real capital cost — heated tanks and recirculation systems for liquid, dust control and agglomeration management for powdered.
By Source
| Sub-Segment | Key Trend |
| Cane Sugar | Tropical cost advantage and ethanol optionality sustain volume dominance |
| Beet Sugar | Policy support and shorter supply chains drive above-average growth in the EU and North America. |
Beet grows faster despite structurally higher production costs because policy protects it. US loan rates and marketing allotments, alongside EU support frameworks, insulate beet economics from world price levels in ways cane producers do not enjoy.
By Application
| Sub-Segment | Key Trend |
| Bakery and Confectionery | Functional irreplaceability limits reformulation, supporting the fastest application growth. |
| Dairy and Frozen Desserts | Freezing-point depression and texture control keep sucrose specified. |
| Beverages | Largest volume base, but most exposed to taxation and reformulation mandates |
| Pharmaceuticals | Syrup bases, coatings, and excipient use with stringent purity requirements |
| Personal Care and Cosmetics | Exfoliant and humectant formulations in premium skincare |
| Others | Fermentation substrate, pet food, and industrial process applications |
Application-level risk is asymmetric across the portfolio. Beverage demand faces direct policy pressure from levies and labelling rules, while bakery, dairy, and pharmaceutical applications depend on functional properties — browning, water activity control, crystallisation behaviour — that no single substitute replicates, making those volumes considerably more defensible over the forecast decade.
.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA