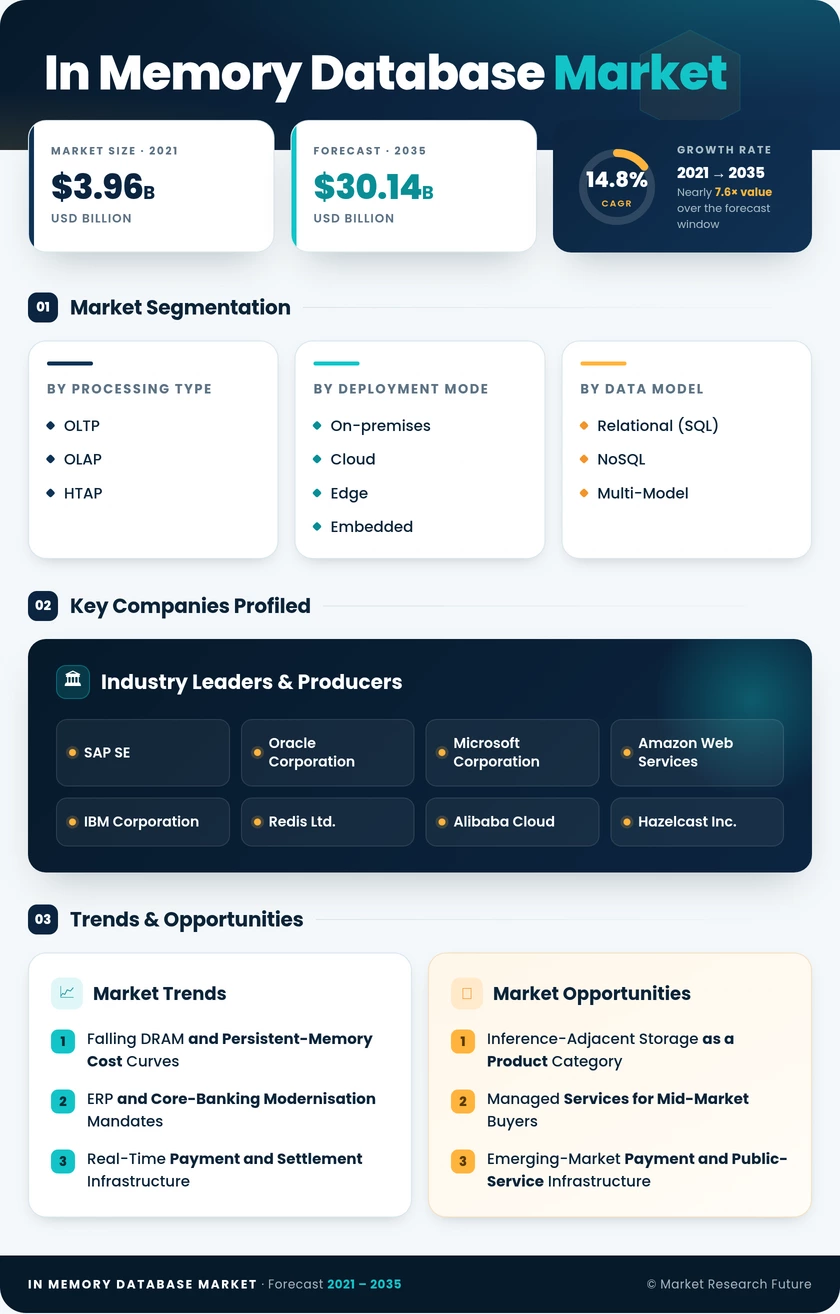
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Processing Type | OLTP, OLAP, HTAP | OLTP — 41.9% share (2025) | HTAP — 19.2% CAGR (2026–2035) |
| By Deployment Mode | On-premises, Cloud, Edge and Embedded | On-premises — USD 3.94 Billion (2025) | Edge and Embedded — 20.9% CAGR (2026–2035) |
| By Data Model | Relational (SQL), NoSQL, Multi-Model | Relational (SQL) — 56.1% share (2025) | Multi-Model — 18.2% CAGR (2026–2035) |
| By Organization Size | Small and Medium Enterprises (SMEs), Large Enterprises | Large Enterprises — 65.7% share (2025) | Small and Medium Enterprises (SMEs) — 16.4% CAGR (2026–2035) |
| By Application | Real-time Transaction Processing, Operational Analytics, Fraud Detection and Risk Management, AI/ML Model Serving | Real-time Transaction Processing — 37.1% share (2025) | AI/ML Model Serving — 21.5% CAGR (2026–2035) |
| By End-user Industry | BFSI, Telecommunications and IT, Retail and E-commerce, Manufacturing, Healthcare and Life Sciences | BFSI — USD 2.06 Billion (2025) | Healthcare and Life Sciences — 17.3% CAGR (2026–2035) |
| By Region | North America, Europe, Asia-Pacific, South America, Middle East & Africa | Asia-Pacific — 36.4% share (2025) | Asia-Pacific — 36.4% share (2025) |
Market Segmentation Overview
By Processing Type
| Sub-Segment | Key Trend |
| OLTP | Sustained demand for ACID-compliant sub-millisecond commits in banking and ERP. |
| OLAP | Stable business-intelligence footprint, losing incremental budget to flexible engines |
| HTAP | Single-platform designs absorbing budget previously split across two estates. |
OLTP leads because payment authorisation and ERP order capture cannot compromise on transactional integrity, and buyers pay a premium for guaranteed commit latency. HTAP grows fastest as risk teams and supply-chain planners demand analytics against live operational state rather than overnight extracts. OLAP sits between them, retaining installed reporting workloads but attracting little new spend as its analytical role migrates into converged engines.
By Deployment Mode
| Sub-Segment | Key Trend |
| On-premise | Residency rules and bespoke high-availability designs keep regulated workloads local. |
| Cloud | Managed services remove patching and scaling burden for digital-native buyers. |
| Edge and Embedded | Vehicle and factory telemetry forces processing to the point of collection |
On-premises holds the largest revenue pool because banks, insurers, and public agencies must demonstrate physical control over regulated records, and their application stacks are wired to local installations. Edge and Embedded grows fastest: connected-vehicle telemetry and production-line defect detection generate volumes that cannot be backhauled economically. Cloud sits in the middle, expanding steadily wherever residency rules permit managed consumption.
By Data Model
| Sub-Segment | Key Trend |
| Relational (SQL) | Entrenched application code and SQL tooling preserve incumbency |
| NoSQL | Key-value, document, and graph workloads serving flexible-schema requirements |
| Multi-Model | Vector, document, and relational storage consolidating into one memory pool. |
Relational (SQL) dominates because rewriting core transactional code is a risk few enterprises accept, and the available developer skill base reinforces that inertia. Multi-Model grows fastest as AI retrieval pipelines require embeddings and source records co-resident, removing cross-system hops. NoSQL retains well-defined territory in session stores and graph traversal but is increasingly absorbed as multi-model engines add equivalent APIs natively.
By Organization Size
| Sub-Segment | Key Trend |
| Small and Medium Enterprises (SMEs) | Entry-tier managed pricing removing the operations skills barrier |
| Large Enterprises | Petabyte-scale clusters with redundant DRAM and strict SLA commitments |
Large Enterprises generate most revenue because only they can absorb the capital intensity of terabyte-scale DRAM clusters with full redundancy, typically in banking, telecom, and aerospace. Small and Medium Enterprises (SMEs) grow faster from a smaller base as cloud providers assume scaling and patching responsibility, and as open-source-compatible engines cut licensing exposure. The skills scarcity that blocks self-hosted mid-market adoption is precisely what managed offerings neutralise.
By Application
| Sub-Segment | Key Trend |
| Real-time Transaction Processing | Instant commits for trading, payments, and inventory allocation |
| Operational Analytics | Manufacturing dashboards and IT observability with live refresh |
| Fraud Detection and Risk Management | Sub-second scoring against in-flight transaction streams. |
| AI/ML Model Serving | Vector indexes and embeddings served directly from the data layer. |
Real-time Transaction Processing leads because payment gateways and exchange matching engines treat queue depth as direct revenue risk. AI/ML Model Serving grows fastest as inference relocates inside the transactional layer, eliminating network hops between model servers and systems of record. Fraud Detection and Risk Management sits close behind, since scoring must complete before authorisation returns. Operational Analytics remains substantial but attracts proportionally less incremental budget.
By End-user Industry
| Sub-Segment | Key Trend |
| BFSI | Settlement latency, live risk exposure, and supervisory monitoring obligations |
| Telecommunications and IT | Real-time charging, 5G core functions, and network analytics |
| Retail and E-commerce | Inventory accuracy and personalisation during peak trading events |
| Manufacturing | Production-line telemetry and predictive maintenance |
| Healthcare and Life Sciences | Genomics pipelines and clinical decision support at the bedside |
BFSI contributes the largest vertical revenue because settlement windows, risk exposure calculation, and resilience regulation all point at the same architecture. Healthcare and Life Sciences grows fastest as variant-calling pipelines and critical-care decision support demand response times batch warehouses cannot meet. Telecommunications and IT remain a dependable second in charging-system requirements, while Manufacturing spend shifts toward edge-resident deployments on the factory floor increasingly.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA