Hydraulic Equipment Market (2026 - 2035)

ID: MRFR/EnP/6594-HCR 188 Pages Priya Nagrale Last Updated: September 15, 2026
Hydraulic Equipment Market Research Report By Equipment Type (Pumps, Valves, Cylinders, Motors, Filters and Accumulators, Transmissions, Others), By Application (Mobile Hydraulics, Industrial Stationary Hydraulics), By End-User Industry (Construction, Agriculture, Material Handling, Mining and Metals, Aerospace and Defense, Oil and Gas, Marine, Others), By Operating-Pressure Range (Low Pressure, Medium Pressure, High Pressure) - Forecast to 2035
Hydraulic Equipment Market
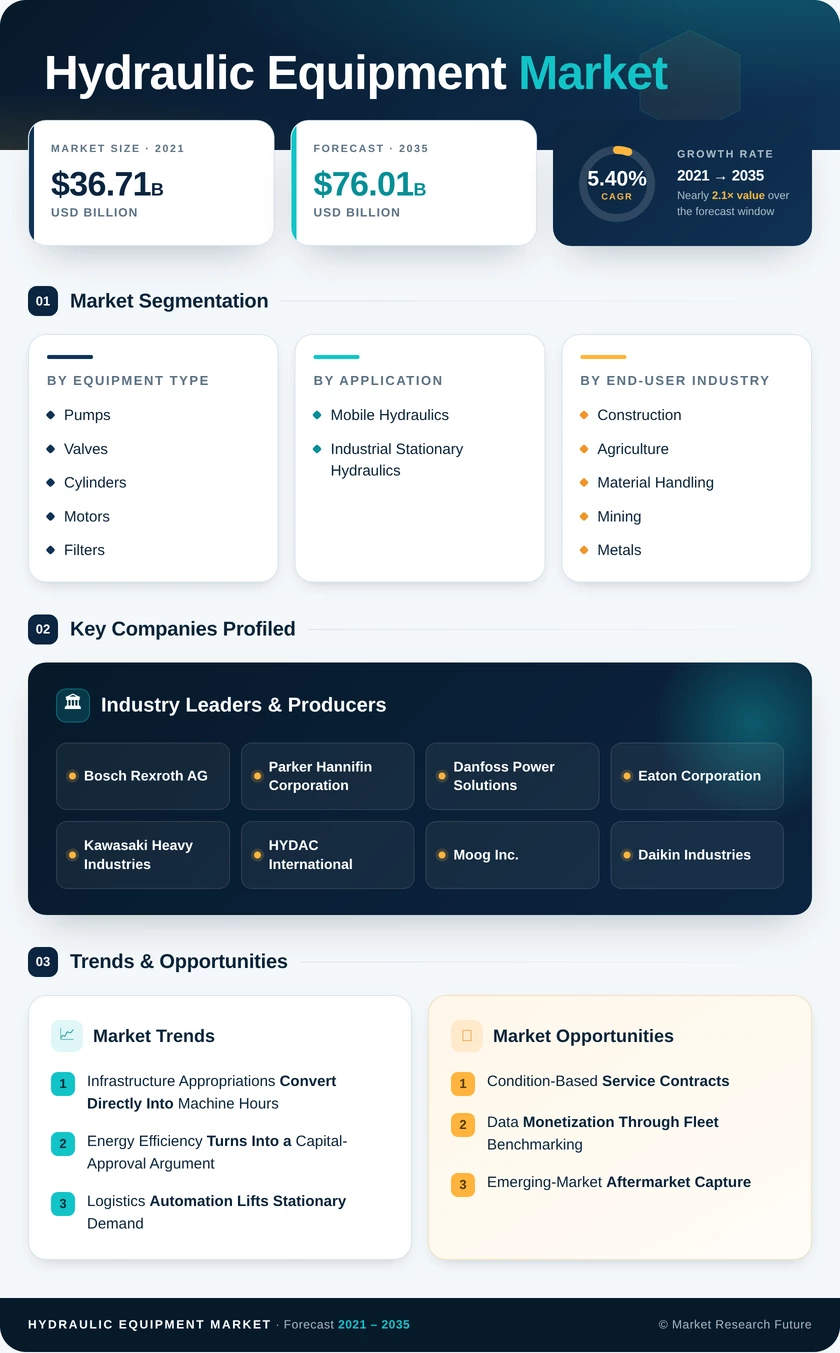
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.40%
2025 Market SizeUSD 44.92 Billion
2035 Market SizeUSD 76.01 Billion
Key Players
Bosch Rexroth AG
Parker Hannifin Corporation
Danfoss Power Solutions
Eaton Corporation
Kawasaki Heavy Industries
HYDAC International
Opportunities
  • Condition-Based Service Contracts
  • Data Monetization Through Fleet Benchmarking
  • Emerging-Market Aftermarket Capture
  1. 1 Market Summary | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Technology | |
    2. 2.2 By Sector | |
    3. 2.3 By Geography | |
  3. 3 Market Size & Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Current & Forecast Market Size (2026–2035) | |
    3. 3.3 Market Size by Revenue (USD Billion) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Infrastructure Appropriations Convert Directly Into Machine Hours | |
    2. 4.2 Energy Efficiency Turns Into a Capital-Approval Argument | |
    3. 4.3 Logistics Automation Lifts Stationary Demand | |
    4. 4.4 Agricultural Mechanization Scales in Emerging Economies | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Electrification Erodes the Low-Force Perimeter | |
    2. 5.2 Input Cost Volatility Compresses Supplier Margins | |
    3. 5.3 Environmental Compliance Adds Lifecycle Cost | |
  6. 6 Opportunities | |
    1. 6.1 Condition-Based Service Contracts | |
    2. 6.2 Data Monetization Through Fleet Benchmarking | |
    3. 6.3 Emerging-Market Aftermarket Capture | |
    4. 6.4 Electro-Hydraulic Hybrid Architectures | |
    5. 6.5 Regulated Water and Wastewater Infrastructure | |
  7. 7 Regional Market Share & Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of Middle East & Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Autonomy Shifts Value Toward the Control Layer | |
    2. 8.2 The Electrification Supercycle Redraws the Boundary | |
    3. 8.3 Service Platforms Displace Transactional Spares | |
    4. 8.4 Sustainability Reporting Reaches the Component Level | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Equipment Type | | |
      1. 9.1.1 Pumps | | |
      2. 9.1.2 Valves | | |
      3. 9.1.3 Cylinders | | |
      4. 9.1.4 Motors | | |
      5. 9.1.5 Filters and Accumulators | | |
      6. 9.1.6 Transmissions | | |
      7. 9.1.7 Others | |
    2. 9.2 By Application | | |
      1. 9.2.1 Mobile Hydraulics | | |
      2. 9.2.2 Industrial Stationary Hydraulics | |
    3. 9.3 By End-User Industry | | |
      1. 9.3.1 Construction | | |
      2. 9.3.2 Agriculture | | |
      3. 9.3.3 Material Handling | | |
      4. 9.3.4 Mining and Metals | | |
      5. 9.3.5 Aerospace and Defense | | |
      6. 9.3.6 Oil and Gas | | |
      7. 9.3.7 Marine | | |
      8. 9.3.8 Others | |
    4. 9.4 By Operating-Pressure Range | | |
      1. 9.4.1 Low Pressure | | |
      2. 9.4.2 Medium Pressure | | |
      3. 9.4.3 High Pressure | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 Bosch Rexroth AG | | |
      2. 10.3.2 Parker Hannifin Corporation | | |
      3. 10.3.3 Danfoss Power Solutions | | |
      4. 10.3.4 Eaton Corporation | | |
      5. 10.3.5 Kawasaki Heavy Industries | | |
      6. 10.3.6 HYDAC International | | |
      7. 10.3.7 Moog Inc. | | |
      8. 10.3.8 Daikin Industries | | |
      9. 10.3.9 KYB Corporation | | |
      10. 10.3.10 Bucher Hydraulics | | |
      11. 10.3.11 Enerpac Tool Group | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope & Methodology | |
    1. 12.1 Study Period & Base Year | |
    2. 12.2 Data Sources & Citations | |
    3. 12.3 Abbreviations | |
  13. 13 Detailed Sources & Citations | |
  14. 14 Frequently Asked Questions | | LIST OF TABLES | | Source: Market Research Future (MRFR) Analysis | | LIST OF FIGURES | | Source: Market Research Future (MRFR) Analysis

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Equipment TypePumps; Valves; Cylinders; Motors; Filters and Accumulators; Transmissions; OthersPumpsFilters and Accumulators
By ApplicationMobile Hydraulics; Industrial Stationary HydraulicsMobile HydraulicsMobile Hydraulics
By End-User IndustryConstruction; Agriculture; Material Handling; Mining and Metals; Aerospace and Defense; Oil and Gas; Marine; OthersConstructionAerospace and Defense
By Operating-Pressure RangeLow; Medium; HighMedium PressureHigh Pressure
By GeographyNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaNorth AmericaAsia-Pacific


Market Segmentation Overview

By Equipment Type

Sub-SegmentKey Trend
PumpsMix shift toward variable-displacement axial piston designs
ValvesRising function count per machine drives independent metering.
CylindersLightweight materials and integrated position sensing
MotorsHydrostatic travel drives standardize on compact radial units.
Filters and AccumulatorsContamination-control mandates lift replacement frequency.
TransmissionsHydrostatic adoption in compact construction equipment
OthersHose and fitting standardization around leak-free designs


Hardware demand is bifurcating. Commodity components face relentless price pressure from Asian producers, while engineered pumps, valves and filtration units carry rising software and sensor content that protects margin.

By Application

Sub-SegmentKey Trend
Mobile HydraulicsElectrified prime movers paired with on-demand pump circuits
Industrial Stationary HydraulicsVariable-speed power units replacing fixed-flow installations


Mobile equipment continues to outgrow stationary installations because off-highway machines have no viable substitute for high-force actuation. Stationary demand grows more slowly but converts faster to retrofit revenue.

By End-User Industry

Sub-SegmentKey Trend
ConstructionPublic infrastructure appropriations sustain multi-year demand
AgricultureMechanization subsidies raise hydraulic content per tractor.
Material HandlingWarehouse and port automation expands compact power unit use.
Mining and MetalsFleet renewal and larger-bore cylinder specifications
Aerospace and DefenseActuation content per airframe and sustainment budgets
Oil and GasPressure-control and drilling equipment replacement cycles
MarineDeck machinery, steering gear and emissions-driven refits
OthersEnergy storage, waste handling and stage machinery niches


End-user concentration in construction creates cyclical exposure that suppliers actively hedge by expanding into aerospace, defense and regulated water infrastructure, where procurement follows multi-year schedules rather than credit conditions.

By Operating-Pressure Range

Sub-SegmentKey Trend
Low Pressure (<70 bar)Most exposed to electromechanical substitution
Medium Pressure (70–210 bar)Volume backbone across mobile and stationary platforms
High Pressure (>210 bar)Power density gains enable smaller, lighter machine envelopes


Pressure class is becoming the clearest proxy for competitive defensibility. The higher the operating pressure, the weaker the substitution threat and the stronger the engineering barrier to entry.

By Geography

Sub-SegmentKey Trend
North AmericaFederal water and transport appropriations peak 2027–2030
EuropeMachinery Regulation compliance forces platform redesign
Asia-PacificTransport stimulus and agricultural mechanization drive volume
South AmericaAgribusiness credit and mining fleet renewal
Middle East & AfricaGiga-project construction and desalination capacity


Regional demand tracks fixed-asset formation rather than manufacturing location. North America leads on committed public capital, while Asia-Pacific converts stimulus into unit volume faster than any other bloc.



Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.