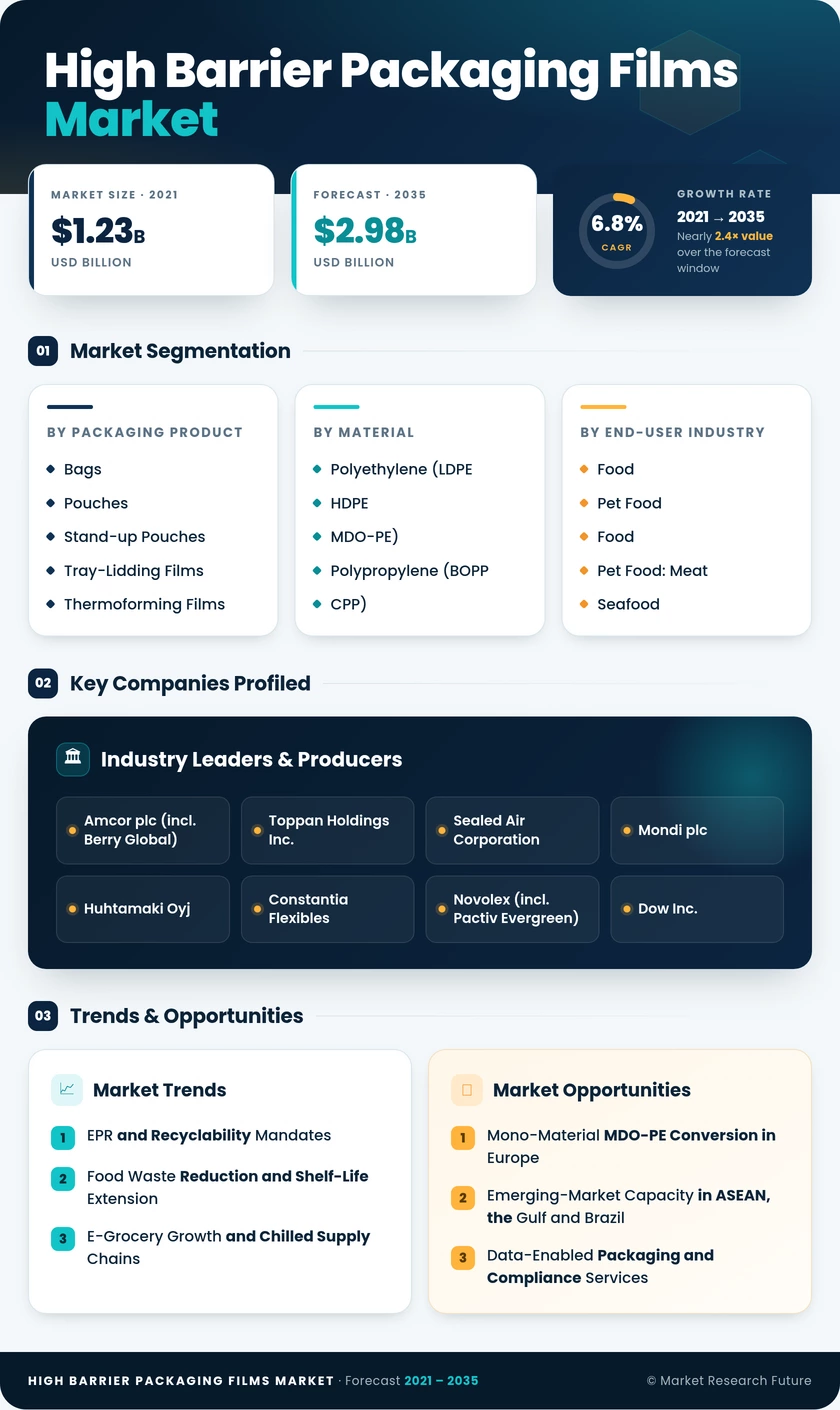
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|
| By Packaging Product | Bags and Pouches, Stand-up Pouches, Tray-Lidding Films, Thermoforming Films, Stretch and Shrink Wrap, Blister Base Film, Flow-wrap and Sachets, Vacuum Skin Packs | Bags and Pouches | Stand-up Pouches |
| By Material | Polyethylene (LDPE, HDPE, MDO-PE), Polypropylene (BOPP, CPP), Biaxially Oriented Polyethylene Terephthalate (BOPET), Ethylene Vinyl Alcohol Copolymer (EVOH), Polyamide, Aluminium Foil, Polyvinylidene Chloride (PVDC), Biopolymers (PLA, PHA), Other Material | Polyethylene (LDPE, HDPE, MDO-PE) | Polypropylene (BOPP, CPP) |
| By End-user Industry | Food and Pet Food, Food and Pet Food: Meat and Seafood, Food and Pet Food: Dairy and Cheese, Food and Pet Food: Snacks and Confectionery, Beverages, Pharmaceutical and Medical, Personal Care and Cosmetics, Electronics, Agriculture and Chemicals | Food and Pet Food | Food and Pet Food: Meat and Seafood |
| By Barrier Type | Metallized Films, Clear High-Barrier Films, Organic-coated Films, Inorganic Oxide Films | Metallized Films | Clear High-Barrier Films |
| By Technology | Multilayer Co-extrusion (≤7 layers), High-layer (>7) Co-extrusion, Mono-material Barrier Films, Other Technology | Multilayer Co-extrusion (≤7 layers) | High-layer (>7) Co-extrusion |
| By Region | North America, Europe, Asia-Pacific, Middle East and Africa, South America | Asia-Pacific | Middle East and Africa |
Market Segmentation Overview
| Sub-Segment | Key Trend |
|---|
| Bags and Pouches | Snacks, coffee and dry pet food |
| Stand-up Pouches | Replacement of glass jars in sauces and baby food |
| Tray-Lidding Films | Peelable, microwavable ready meals |
| Thermoforming Films | Processed meat and pharmaceutical forming webs |
| Stretch and Shrink Wrap | Primal meat cuts and cheese blocks |
| Blister Base Film | Moisture-sensitive tablets |
| Flow-wrap and Sachets | Single-serve condiments and confectionery |
| Vacuum Skin Packs | Premium fresh meat and seafood |
Within the High Barrier Packaging Films Market, Bags and Pouches lead with a 32.8% share across snacks, coffee, cheese and dry pet food. Stand-up Pouches keep replacing glass jars because they weigh less to ship and stack flat. Vacuum Skin Packs are the fastest-growing format at an 8.8% CAGR, as meat and seafood brands seek longer chilled shelf life. Tray-Lidding Films benefit from microwavable ready meals. Thermoforming Films, Stretch and Shrink Wrap, and Blister Base Film serve protein and pharmaceutical niches. Flow-wrap and Sachets face regulatory pressure.
| Sub-Segment | Key Trend |
|---|
| Polyethylene (LDPE, HDPE, MDO-PE) | Sealability and mono-material designs |
| Polypropylene (BOPP, CPP) | Hot-fill and high-clarity packs |
| Biaxially Oriented Polyethylene Terephthalate (BOPET) | Print stability and metallisation substrate |
| Ethylene Vinyl Alcohol Copolymer (EVOH) | Premium oxygen barrier layers |
| Polyamide | Puncture resistance in meat packs |
| Aluminium Foil | Retort pouches and coffee |
| Polyvinylidene Chloride (PVDC) | Coffee and seasoning sachets |
| Biopolymers (PLA, PHA) | Compost-ready retailer specifications |
| Other Material | Specialty tie resins and sealants |
Material choice in the High Barrier Packaging Films Market still centres on Polyethylene (LDPE, HDPE, MDO-PE), which holds a 30.1% share thanks to its sealability and its role in mono-material designs. Polypropylene (BOPP, CPP) serves hot-fill packs, and Biaxially Oriented Polyethylene Terephthalate (BOPET) provides print stability. Ethylene Vinyl Alcohol Copolymer (EVOH) remains the premium oxygen barrier. Biopolymers (PLA, PHA) are the fastest-growing material at a 9.3% CAGR. Aluminium Foil and Polyvinylidene Chloride (PVDC) are losing ground, while Polyamide and other materials fill specialty roles.
| Sub-Segment | Key Trend |
|---|
| Food and Pet Food | Shelf-life extension and waste reduction |
| Food and Pet Food: Meat and Seafood | Vacuum skin and shrink formats |
| Food and Pet Food: Dairy and Cheese | EVOH pouches and lidding |
| Food and Pet Food: Snacks and Confectionery | Metallized and coated films |
| Beverages | Ready-to-drink coffee and nutrition powders |
| Pharmaceutical and Medical | Biologics and moisture-sensitive generics |
| Personal Care and Cosmetics | Aluminium-free laminated tubes |
| Electronics | Moisture-sensitive component packaging |
| Agriculture and Chemicals | Multi-wall barrier sacks for agrochemicals |
End-use demand across the High Barrier Packaging Films Market is dominated by Food and Pet Food, which holds a 61.0% share. Within food, Meat and Seafood packs grow on vacuum skin and shrink formats, Dairy and Cheese rely on EVOH pouches and lidding, and Snacks and Confectionery use metallized and coated films. Pharmaceutical and Medical is the fastest-growing end use at a 7.6% CAGR, driven by biologics. Beverages, Personal Care and Cosmetics, Electronics, and Agriculture and Chemicals account for the remaining demand.
| Sub-Segment | Key Trend |
|---|
| Metallized Films | Low-cost light and oxygen protection |
| Clear High-Barrier Films | Product visibility in fresh food |
| Organic-coated Films | Recycling-compatible water-based coatings |
| Inorganic Oxide Films | Transparent, microwavable near-foil barrier |
Barrier technology in the High Barrier Packaging Films Market is led by Metallized Films with a 38.5% share, valued for low-cost light and oxygen protection in coffee and snacks. Clear High-Barrier Films support product visibility in fresh food and ready meals. Organic-coated Films are the fastest-growing barrier type at a 7.8% CAGR, because their water-based dispersions do not interfere with polyolefin recycling. Inorganic Oxide Films, which use aluminium or silicon oxide coatings, deliver near-foil barrier while keeping packs transparent and microwavable.
| Sub-Segment | Key Trend |
|---|
| Multilayer Co-extrusion (≤7 layers) | EVOH-core food packaging |
| High-layer (>7) Co-extrusion | Pharmaceutical and retort applications |
| Mono-material Barrier Films | PPWR and EPR fee structures |
| Other Technology | Lamination and extrusion coating |
Process technology shapes the cost and recyclability profile of the High Barrier Packaging Films Market. Multilayer Co-extrusion (≤7 layers) holds a 47.5% share as the standard platform for EVOH-core food packaging. High-layer (>7) Co-extrusion serves demanding pharmaceutical and retort applications, where thinner and more numerous layers improve barrier per gram. Mono-material Barrier Films are the fastest-growing technology at a 9.1% CAGR, driven by PPWR and EPR fee structures. Other Technology, including lamination and extrusion coating, covers legacy and specialty formats.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA