Graph Database Market (2026 - 2035)

ID: MRFR/ICT/19847-HCR 200 Pages Kiran Jinkalwad Last Updated: September 10, 2026
Graph Database Market Size, Share and Research Report By Component (Solutions and Services), By Deployment (Cloud and On-Premises), By End-User Enterprise Size (SMEs and Large Enterprises), By End-User Industry (BFSI, Healthcare and Life Sciences, Retail and E-Commerce, IT and Telecommunications, Media and Entertainment, Transportation and Logistics, and Others), And By Region (North America, Europe, Asia-Pacific, And Rest Of The World) – Industry Forecast Till 2035.
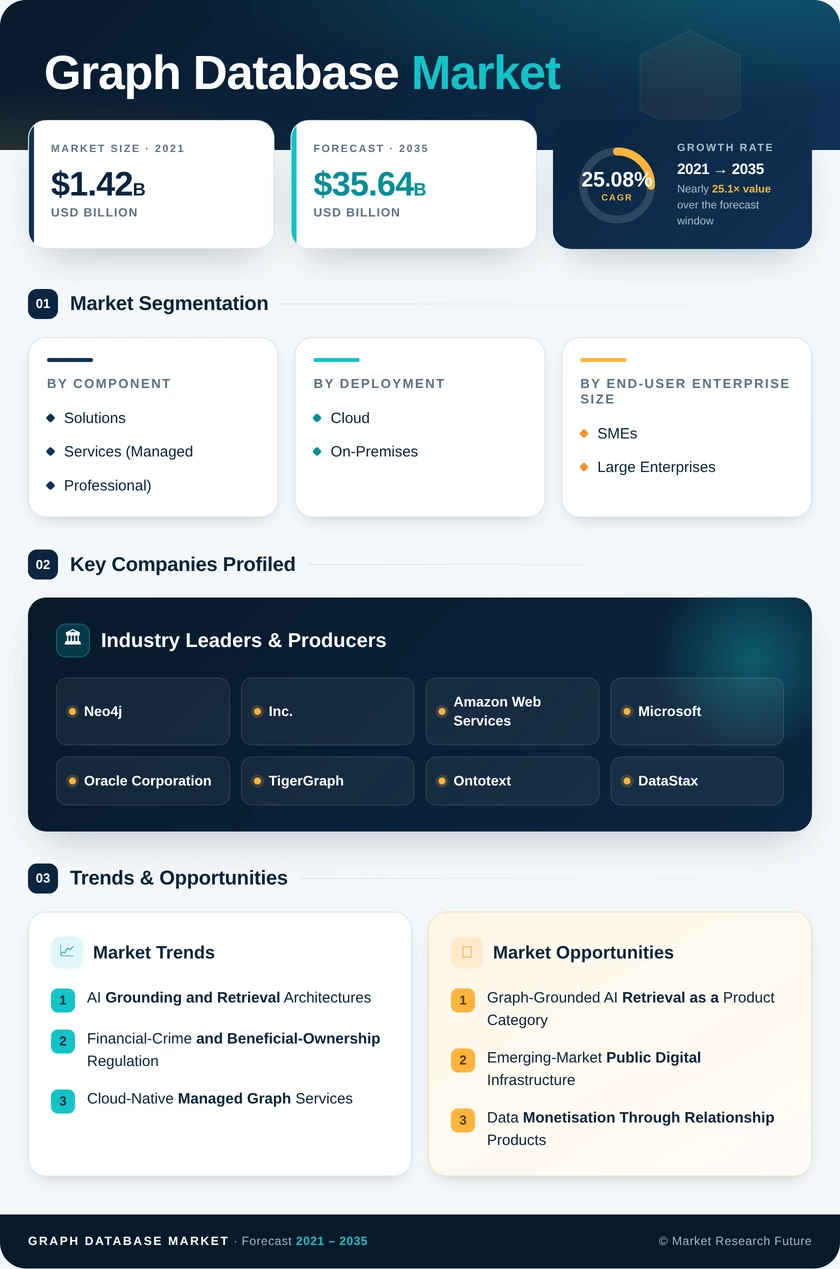
Graph Database Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)25.08%
2025 Market SizeUSD 3.52 Billion
2035 Market SizeUSD 35.64 Billion
Key Players
Neo4j, Inc.
Amazon Web Services
Microsoft
Oracle Corporation
TigerGraph
Ontotext
Opportunities
  • Graph-Grounded AI Retrieval as a Product Category
  • Emerging-Market Public Digital Infrastructure
  • Data Monetisation Through Relationship Products
  1. 1 Market Summary | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Component | |
    2. 2.2 By Deployment | |
    3. 2.3 By End-User Enterprise Size | |
    4. 2.4 By End-User Industry | |
    5. 2.5 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Current & Forecast Market Size (2026–2035) | |
    3. 3.3 Market Size by Revenue (USD Billion) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 AI Grounding and Retrieval Architectures | |
    2. 4.2 Financial-Crime and Beneficial-Ownership Regulation | |
    3. 4.3 Cloud-Native Managed Graph Services | |
    4. 4.4 Supply-Chain Traceability Mandates | |
    5. 4.5 Healthcare Interoperability and Precision Medicine | |
    6. 4.6 Cybersecurity Attack-Path Modelling | |
    7. 4.7 Master Data and Customer-360 Consolidation | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Scarcity of Graph Modelling Expertise | |
    2. 5.2 Query Language Fragmentation | |
    3. 5.3 Migration Cost from Relational Estates | |
    4. 5.4 Scale-Out Performance Ceilings | |
    5. 5.5 Data Residency and Egress Economics | |
  6. 6 Opportunities | |
    1. 6.1 Graph-Grounded AI Retrieval as a Product Category | |
    2. 6.2 Emerging-Market Public Digital Infrastructure | |
    3. 6.3 Data Monetisation Through Relationship Products | |
    4. 6.4 Vertical Reference Ontologies | |
    5. 6.5 Mid-Market Serverless Delivery | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of MEA | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Autonomous Agents and Machine-Readable Context | |
    2. 8.2 Consumption Economics and Platform Consolidation | |
    3. 8.3 Standardisation Under GQL | |
    4. 8.4 Regulatory Traceability as Permanent Demand | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Component | | |
      1. 9.1.1 Solutions | | |
      2. 9.1.2 Services | |
    2. 9.2 By Deployment | | |
      1. 9.2.1 Cloud | | |
      2. 9.2.2 On-Premises | |
    3. 9.3 By End-User Enterprise Size | | |
      1. 9.3.1 SMEs | | |
      2. 9.3.2 Large Enterprises | |
    4. 9.4 By End-User Industry | | |
      1. 9.4.1 BFSI | | |
      2. 9.4.2 Healthcare and Life Sciences | | |
      3. 9.4.3 Retail and E-Commerce | | |
      4. 9.4.4 IT and Telecommunications | | |
      5. 9.4.5 Media and Entertainment | | |
      6. 9.4.6 Transportation and Logistics | | |
      7. 9.4.7 Others | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Share Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 Neo4j, Inc. | | |
      2. 10.3.2 Amazon Web Services | | |
      3. 10.3.3 Microsoft | | |
      4. 10.3.4 Oracle Corporation | | |
      5. 10.3.5 TigerGraph | | |
      6. 10.3.6 Ontotext | | |
      7. 10.3.7 DataStax | | |
      8. 10.3.8 Google Cloud | | |
      9. 10.3.9 Stardog | | |
      10. 10.3.10 ArangoDB | | |
      11. 10.3.11 Memgraph | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
    1. 12.1 Study Period & Base Year | |
    2. 12.2 Data Sources & Citations | |
    3. 12.3 Abbreviations | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Global Graph Database Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Global Graph Database Market – Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis – Global Graph Database Market, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis – Global Graph Database Market, 2026–2035 | |
  19. TABLE 5 Global Graph Database Market Size, by Component, 2021–2035 (USD Billion) | |
  20. TABLE 6 Global Graph Database Market Size, by Deployment, 2021–2035 (USD Billion) | |
  21. TABLE 7 Global Graph Database Market Size, by End-User Enterprise Size, 2021–2035 (USD Billion) | |
  22. TABLE 8 Global Graph Database Market Size, by End-User Industry, 2021–2035 (USD Billion) | |
  23. TABLE 9 Global Graph Database Market Size, by Region, 2021–2035 (USD Billion) | |
  24. TABLE 10 North America Graph Database Market Size, by Country, 2021–2035 (USD Billion) | |
  25. TABLE 11 Europe Graph Database Market Size, by Country, 2021–2035 (USD Billion) | |
  26. TABLE 12 Asia-Pacific Graph Database Market Size, by Country, 2021–2035 (USD Billion) | |
  27. TABLE 13 South America Graph Database Market Size, by Country, 2021–2035 (USD Billion) | |
  28. TABLE 14 Middle East & Africa Graph Database Market Size, by Country, 2021–2035 (USD Billion) | |
  29. TABLE 15 North America Graph Database Market Size, by Component, 2021–2035 (USD Billion) | |
  30. TABLE 16 North America Graph Database Market Size, by Deployment, 2021–2035 (USD Billion) | |
  31. TABLE 17 North America Graph Database Market Size, by End-User Industry, 2021–2035 (USD Billion) | |
  32. TABLE 18 Europe Graph Database Market Size, by Component, 2021–2035 (USD Billion) | |
  33. TABLE 19 Europe Graph Database Market Size, by Deployment, 2021–2035 (USD Billion) | |
  34. TABLE 20 Europe Graph Database Market Size, by End-User Industry, 2021–2035 (USD Billion) | |
  35. TABLE 21 Asia-Pacific Graph Database Market Size, by Component, 2021–2035 (USD Billion) | |
  36. TABLE 22 Asia-Pacific Graph Database Market Size, by Deployment, 2021–2035 (USD Billion) | |
  37. TABLE 23 Asia-Pacific Graph Database Market Size, by End-User Industry, 2021–2035 (USD Billion) | |
  38. TABLE 24 South America Graph Database Market Size, by Component, 2021–2035 (USD Billion) | |
  39. TABLE 25 South America Graph Database Market Size, by End-User Industry, 2021–2035 (USD Billion) | |
  40. TABLE 26 Middle East & Africa Graph Database Market Size, by Component, 2021–2035 (USD Billion) | |
  41. TABLE 27 Middle East & Africa Graph Database Market Size, by End-User Industry, 2021–2035 (USD Billion) | |
  42. TABLE 28 Competitive Benchmarking Matrix – Global Graph Database Market, 2026 | |
  43. TABLE 29 Company Profiles – Key Players, Global Graph Database Market | |
  44. TABLE 30 Recent Developments & Strategic Announcements, 2023–2025 | |
  45. TABLE 31 Report Scope & Methodology Summary | |
  46. TABLE 32 Detailed Sources and Citations Index | | LIST OF FIGURES | |
  47. FIGURE 1 Global Graph Database Market – Market Dynamics Overview | |
  48. FIGURE 2 Industry Value Chain Analysis – Graph Database Market | |
  49. FIGURE 3 Porter's Five Forces Analysis – Graph Database Market | |
  50. FIGURE 4 Global Graph Database Market Size Trend, 2021–2035 (USD Billion) | |
  51. FIGURE 5 Year-over-Year Growth Rate Trend, 2022–2035 (%) | |
  52. FIGURE 6 Market Share by Component, 2025 vs 2035 (%) | |
  53. FIGURE 7 Market Share by Deployment, 2025 vs 2035 (%) | |
  54. FIGURE 8 Market Share by End-User Enterprise Size, 2025 (%) | |
  55. FIGURE 9 Market Share by End-User Industry, 2025 (%) | |
  56. FIGURE 10 Regional Market Share Distribution, 2025 (%) | |
  57. FIGURE 11 Regional CAGR Comparison, 2026–2035 (%) | |
  58. FIGURE 12 North America Country-Level Share Distribution, 2025 (%) | |
  59. FIGURE 13 Europe Country-Level Share Distribution, 2025 (%) | |
  60. FIGURE 14 Asia-Pacific Country-Level Share Distribution, 2025 (%) | |
  61. FIGURE 15 Competitive Landscape – Vendor Positioning Matrix, 2026 | |
  62. FIGURE 16 Estimated Revenue Share Ranges of Leading Vendors, 2026 (%)

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By ComponentSolutions; Services (Managed, Professional)Solutions — 58.4% share (2025)Services — 24.6% CAGR (2026–2035)
By DeploymentCloud; On-PremisesCloud — USD 2.31 Billion (2025)Cloud — USD 2.31 Billion (2025)
By End-User Enterprise SizeSMEs; Large EnterprisesLarge Enterprises — 54.5% share (2025)SMEs — 26.9% CAGR (2026–2035)
By End-User IndustryBFSI; Healthcare and Life Sciences; Retail and E-Commerce; IT and Telecommunications; Media and Entertainment; Transportation and Logistics; OthersBFSI — 23.8% share (2025)Healthcare and Life Sciences — 27.4% CAGR (2026–2035)


Market Segmentation Overview

By Component

Sub-SegmentKey Trend
SolutionsNative vector indexing added alongside traversal engines for AI retrieval workloads
Services — ManagedOperational outsourcing rises as deployment counts outpace internal staffing
Services — ProfessionalOntology design and schema consulting command premium rates


Solutions hold the larger share because the engine subscription anchors every contract, but Services expand faster as buyers confront the expertise gap described in Section 9.1. Within Services, Professional engagements arrive first — schema and ontology design determine whether a deployment performs — while Managed contracts follow production go-live and convert project revenue into recurring streams. Vendors increasingly bundle reference architectures with Solutions licences to shorten the Professional phase, which paradoxically increases total service attach rates by making more projects viable.

By Deployment

Sub-SegmentKey Trend
CloudHyperscaler-managed engines with autoscaling and integrated backup dominate new workloads
On-PremisesHybrid blueprints keep sensitive stores local while analytics runs externally


Cloud leads and grows fastest, driven by managed services that eliminate cluster administration and let engineering teams provision capacity in minutes rather than quarters. On-Premises retains a meaningful base in defence, national health systems, and central banking, where residency rules prohibit external hosting outright. The dominant architectural pattern is neither pure — regulated buyers increasingly split workloads, keeping the authoritative store on site while running inference and analytical traversals in cloud environments, which sustains modest On-Premises growth even as its share declines.

By End-User Enterprise Size

Sub-SegmentKey Trend
SMEsServerless query-unit billing and low-code modelling remove capital barriers
Large EnterprisesMulti-workload consolidation onto shared graph platforms


Large Enterprises dominate spending because their fraud, supply-chain, and customer-consolidation workloads run at volumes that justify dedicated platform teams. SMEs grow faster from a smaller base, enabled by consumption pricing that scales with query volume rather than requiring cluster licences upfront. Templates for recommendation and supplier-risk screening let smaller firms reach production without hiring the specialists that Section 9.3 identifies as scarce, and this cohort shows strong expansion behaviour once a first workload succeeds.

By End-User Industry

Sub-SegmentKey Trend
BFSIBeneficial-ownership tracing under new anti-money-laundering regimes
Healthcare and Life SciencesIntegration of genomic, chemical, and clinical records for target discovery
Retail and E-CommerceReal-time recommendation and cross-channel identity resolution
IT and TelecommunicationsNetwork topology, dependency, and service-impact mapping
Media and EntertainmentContent personalisation and rights-chain management
Transportation and LogisticsMulti-tier supplier visibility and dynamic route optimisation
OthersGovernment entity resolution, energy asset hierarchies, education records


BFSI leads because regulation dictates the architecture rather than preference — tracing ownership chains and transaction rings across arbitrary depth is a traversal problem relational schemas handle badly. Healthcare and Life Sciences grows fastest as sponsors link biomedical datasets to compress target identification timelines, consistent with Section 9.4. Transportation and Logistics accelerates on due-diligence rules requiring visibility past first-tier suppliers, while IT and Telecommunications sustains steady demand from dependency mapping in increasingly distributed network estates.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.