Gas Insulated Transformer Market (2026 - 2035)

ID: MRFR/EnP/5148-HCR 111 Pages Anshula Mandaokar Last Updated: September 15, 2026
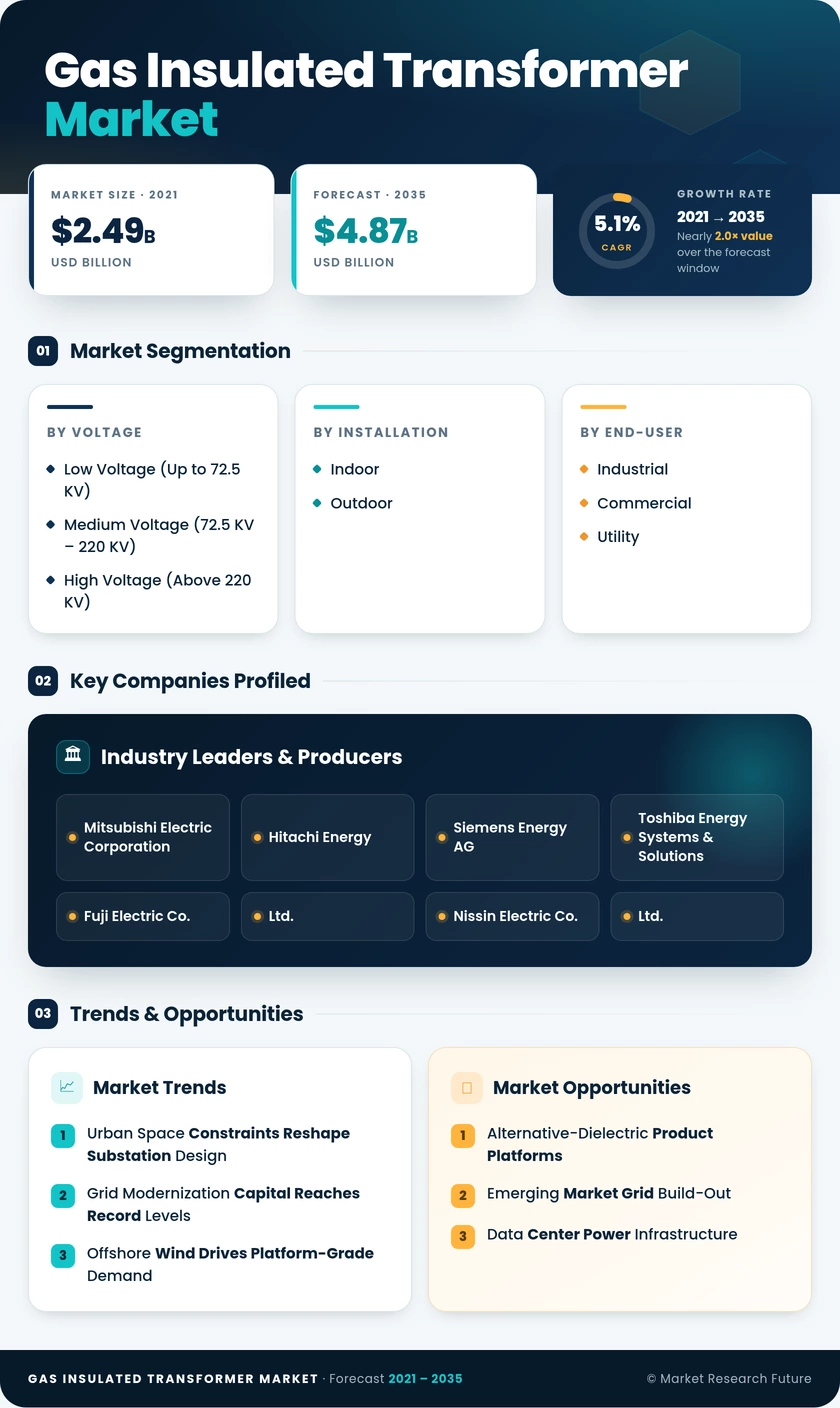
Gas Insulated Transformer Market Research Report By Voltage (Low Voltage (Up to 72.5 kV), Medium Voltage (72.5 kV–220 kV), High Voltage (Above 220 kV)), By Installation (Indoor, Outdoor), By End-User (Industrial, Commercial, Utility) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth & Industry Forecast to 2035
Gas Insulated Transformer Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.1%
2025 Market SizeUSD 2.96 Billion
2035 Market SizeUSD 4.87 Billion
Key Players
Mitsubishi Electric Corporation
Hitachi Energy
Siemens Energy AG
Toshiba Energy Systems & Solutions
Fuji Electric Co., Ltd.
Nissin Electric Co., Ltd.
Opportunities
  • Alternative-Dielectric Product Platforms
  • Emerging Market Grid Build-Out
  • Data Center Power Infrastructure
  1. 1 Market Summary |
    1. 1.1 Study Assumptions & Market Definition |
    2. 1.2 Scope of the Study |
    3. 1.3 Research Methodology
  2. 2 Key Report Takeaways |
    1. 2.1 By Voltage |
    2. 2.2 By Installation |
    3. 2.3 By End-User |
    4. 2.4 By Geography
  3. 3 Market Size & Forecast (2021–2035) |
    1. 3.1 Historical Market Size (2021–2025) |
    2. 3.2 Current & Forecast Market Size (2026–2035) |
    3. 3.3 Market Size by Revenue (USD Billion) |
    4. 3.4 Year-over-Year Growth Analysis
  4. 4 Driver Impact Analysis |
    1. 4.1 Urban Space Constraints Reshape Substation Design |
    2. 4.2 Grid Modernization Capital Reaches Record Levels |
    3. 4.3 Offshore Wind Drives Platform-Grade Demand |
    4. 4.4 Fire Codes and Insurance Economics
  5. 5 Restraints Impact Analysis |
    1. 5.1 The Capital Cost Premium |
    2. 5.2 Regulatory Pressure on Insulating Media |
    3. 5.3 Skills and Handling Infrastructure
  6. 6 Opportunity Analysis |
    1. 6.1 Alternative-Dielectric Product Platforms |
    2. 6.2 Emerging Market Grid Build-Out |
    3. 6.3 Data Center Power Infrastructure |
    4. 6.4 Condition-Monitoring Services and Digital Twins |
    5. 6.5 Retrofit-in-Place Programs |
    6. 6.6 Industry Value Chain Analysis |
    7. 6.7 Porter's Five Forces Analysis
  7. 7 Regional Market Share & Country-Level Analysis |
    1. 7.1 North America | |
      1. 7.1.1 US | |
      2. 7.1.2 Canada | |
      3. 7.1.3 Mexico |
    2. 7.2 Europe | |
      1. 7.2.1 Germany | |
      2. 7.2.2 UK | |
      3. 7.2.3 France | |
      4. 7.2.4 Italy | |
      5. 7.2.5 Spain | |
      6. 7.2.6 Nordic Countries | |
      7. 7.2.7 Russia | |
      8. 7.2.8 Rest of Europe |
    3. 7.3 Asia-Pacific | |
      1. 7.3.1 China | |
      2. 7.3.2 India | |
      3. 7.3.3 Japan | |
      4. 7.3.4 South Korea | |
      5. 7.3.5 ASEAN | |
      6. 7.3.6 Rest of Asia-Pacific |
    4. 7.4 South America | |
      1. 7.4.1 Brazil | |
      2. 7.4.2 Argentina | |
      3. 7.4.3 Rest of South America |
    5. 7.5 Middle East & Africa | |
      1. 7.5.1 Saudi Arabia | |
      2. 7.5.2 UAE | |
      3. 7.5.3 South Africa | |
      4. 7.5.4 Egypt | |
      5. 7.5.5 Rest of Middle East & Africa
  8. 8 Future Outlook (2026–2035) |
    1. 8.1 The Electrification Supercycle |
    2. 8.2 Digital Twins and Predictive Asset Management |
    3. 8.3 Dielectric Chemistry Becomes a Competitive Moat |
    4. 8.4 ESG Disclosure Reaches Equipment Procurement
  9. 9 Market Segmentation Analysis |
    1. 9.1 By Voltage | |
      1. 9.1.1 Low Voltage (Up to
    2. 72.5 KV) | |
      1. 9.1.2 Medium Voltage (72.5 KV – 220 KV) | |
      2. 9.1.3 High Voltage (Above 220 KV) |
    3. 9.2 By Installation | |
      1. 9.2.1 Indoor | |
      2. 9.2.2 Outdoor |
    4. 9.3 By End-User | |
      1. 9.3.1 Industrial | |
      2. 9.3.2 Commercial | |
      3. 9.3.3 Utility
  10. 10 Competitive Landscape |
    1. 10.1 Market Share Analysis (2026) |
    2. 10.2 Competitive Benchmarking Matrix |
    3. 10.3 Company Profiles | |
      1. 10.3.1 Mitsubishi Electric Corporation | |
      2. 10.3.2 Hitachi Energy | |
      3. 10.3.3 Siemens Energy AG | |
      4. 10.3.4 Toshiba Energy Systems & Solutions | |
      5. 10.3.5 Fuji Electric Co., Ltd. | |
      6. 10.3.6 Nissin Electric Co., Ltd. | |
      7. 10.3.7 Meidensha Corporation | |
      8. 10.3.8 Hyundai Electric & Energy Systems | |
      9. 10.3.9 TBEA Co., Ltd. | |
      10. 10.3.10 CG Power and Industrial Solutions | |
      11. 10.3.11 Schneider Electric SE | |
      12. 10.3.12 Takaoka Toko Co., Ltd.
  11. 11 Recent News & Developments
  12. 12 Report Scope & Methodology |
    1. 12.1 Study Period & Base Year |
    2. 12.2 Valuation Currency & Assumptions |
    3. 12.3 Abbreviations
  13. 13 Detailed Sources & Citations
  14. 14 Frequently Asked Questions (FAQs)
  15. 15 LIST OF TABLES |
  16. TABLE 1 Global Gas Insulated Transformer Market Size & Forecast, by Revenue (USD Billion), 2021–2035 |
  17. TABLE 2 Global Market – Year-over-Year Growth Analysis, 2021–2035 |
  18. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 |
  19. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 |
  20. TABLE 5 Global Market Size, by Region, 2021–2035 (USD Billion) |
  21. TABLE 6 North America Market Size, by Country, 2021–2035 (USD Billion) |
  22. TABLE 7 Europe Market Size, by Country, 2021–2035 (USD Billion) |
  23. TABLE 8 Asia-Pacific Market Size, by Country, 2021–2035 (USD Billion) |
  24. TABLE 9 South America Market Size, by Country, 2021–2035 (USD Billion) |
  25. TABLE 10 Middle East & Africa Market Size, by Country, 2021–2035 (USD Billion) |
  26. TABLE 11 Global Market Size, by Voltage, 2021–2035 (USD Billion) |
  27. TABLE 12 Global Market Size, by Installation, 2021–2035 (USD Billion) |
  28. TABLE 13 Global Market Size, by End-User, 2021–2035 (USD Billion) |
  29. TABLE 14 North America Market Size, by Voltage, 2021–2035 (USD Billion) |
  30. TABLE 15 North America Market Size, by Installation, 2021–2035 (USD Billion) |
  31. TABLE 16 North America Market Size, by End-User, 2021–2035 (USD Billion) |
  32. TABLE 17 Europe Market Size, by Voltage, 2021–2035 (USD Billion) |
  33. TABLE 18 Europe Market Size, by Installation, 2021–2035 (USD Billion) |
  34. TABLE 19 Europe Market Size, by End-User, 2021–2035 (USD Billion) |
  35. TABLE 20 Asia-Pacific Market Size, by Voltage, 2021–2035 (USD Billion) |
  36. TABLE 21 Asia-Pacific Market Size, by Installation, 2021–2035 (USD Billion) |
  37. TABLE 22 Asia-Pacific Market Size, by End-User, 2021–2035 (USD Billion) |
  38. TABLE 23 South America Market Size, by Voltage, 2021–2035 (USD Billion) |
  39. TABLE 24 South America Market Size, by Installation, 2021–2035 (USD Billion) |
  40. TABLE 25 South America Market Size, by End-User, 2021–2035 (USD Billion) |
  41. TABLE 26 Middle East & Africa Market Size, by Voltage, 2021–2035 (USD Billion) |
  42. TABLE 27 Middle East & Africa Market Size, by Installation, 2021–2035 (USD Billion) |
  43. TABLE 28 Middle East & Africa Market Size, by End-User, 2021–2035 (USD Billion) |
  44. TABLE 29 Competitive Benchmarking Matrix, 2026 |
  45. TABLE 30 Company Profiles – Key Players |
  46. TABLE 31 Recent Developments & Strategic Announcements, 2023–2025 |
  47. TABLE 32 Report Scope & Methodology Summary |
  48. TABLE 33 Detailed Sources & Citations Index |
  49. TABLE 34 Segmentation Quick Reference Matrix
  50. 16 LIST OF FIGURES |
  51. FIGURE 1 Market Dynamics – Drivers, Restraints & Opportunities Framework |
  52. FIGURE 2 Industry Value Chain Analysis |
  53. FIGURE 3 Porter's Five Forces Analysis |
  54. FIGURE 4 Global Market Size Trend & Forecast, 2021–2035 (USD Billion) |
  55. FIGURE 5 Year-over-Year Growth Trajectory, 2022–2035 (%) |
  56. FIGURE 6 Market Share by Voltage Class, 2026 vs 2035 (%) |
  57. FIGURE 7 Market Share by Installation Type, 2026 vs 2035 (%) |
  58. FIGURE 8 Market Share by End-User, 2026 vs 2035 (%) |
  59. FIGURE 9 Regional Market Share Distribution, 2026 (%) |
  60. FIGURE 10 Regional Market Share Distribution, 2035 (%) |
  61. FIGURE 11 Regional CAGR Comparison, 2026–2035 (%) |
  62. FIGURE 12 North America Country-Level Share Breakdown, 2026 (%) |
  63. FIGURE 13 Europe Country-Level Share Breakdown, 2026 (%) |
  64. FIGURE 14 Asia-Pacific Country-Level Share Breakdown, 2026 (%) |
  65. FIGURE 15 Competitive Landscape – Estimated Revenue Share Positioning, 2026 |
  66. FIGURE 16 Competitive Positioning Quadrant – Capability vs Geographic Reach |
  67. FIGURE 17 Driver Impact Weighting Chart |
  68. FIGURE 18 Restraint Impact Weighting Chart

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By VoltageLow Voltage (Up to 72.5 KV); Medium Voltage (72.5 KV – 220 KV); High Voltage (Above 220 KV)Medium Voltage (72.5 KV – 220 KV)High Voltage (Above 220 KV)
By InstallationIndoor; OutdoorIndoorOutdoor
By End-UserIndustrial; Commercial; UtilityUtilityCommercial
By GeographyNorth America; Europe; Asia-Pacific; South America; Middle East and AfricaAsia-PacificAsia-Pacific


Market Segmentation Overview

By Voltage

Sub-SegmentKey Trend
Low Voltage (Up to 72.5 KV)Steady demand from commercial buildings and distribution-tier substations in dense urban blocks
Medium Voltage (72.5 KV – 220 KV)Core replacement tier for utility urban substations; largest tender volumes globally
High Voltage (Above 220 KV)Fastest expansion on offshore platform specifications and ultra-high-voltage interconnection nodes


Voltage class determines both the buyer and the sales cycle. Medium-voltage tenders repeat frequently and reward manufacturing scale, while high-voltage awards are lumpy, engineering-intensive, and heavily weighted toward suppliers with long type-test histories.

By Installation

Sub-SegmentKey Trend
IndoorDominant deployment mode; driven by fire codes, basement and tunnel siting, and land cost economics
OutdoorGrowing on environmental severity — coastal salt exposure, desert dust, and extreme ambient temperatures


Installation environment effectively settles the specification debate before commercial evaluation begins. Where an enclosed vault is the only viable location, non-flammable sealed equipment is not a preference but a code requirement.

By End-User

Sub-SegmentKey Trend
IndustrialUptime-driven procurement across mining, petrochemical, steel, and semiconductor facilities
CommercialFastest-growing cohort, propelled by data centers, airports, and high-rise mixed-use developments
UtilityLargest buyer group; volume tenders shaped by regulatory mandates and asset replacement schedules


Utilities supply the baseline volume, but commercial buyers set the pace of innovation. Data center developers in particular compress schedules aggressively and will pay for factory-tested modular substations that shave months off energization timelines.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.