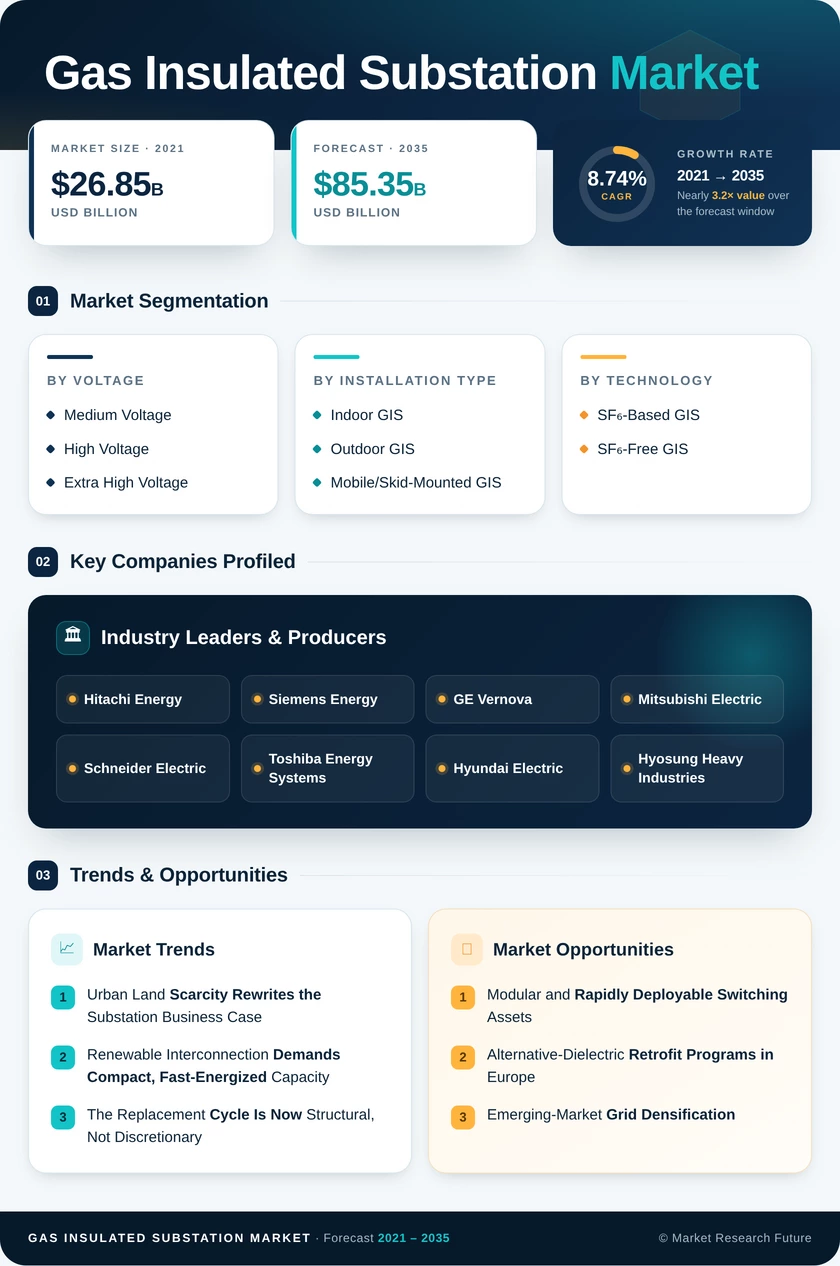
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Voltage | Medium Voltage; High Voltage; Extra High Voltage | High Voltage | Extra High Voltage |
| By Installation Type | Indoor GIS; Outdoor GIS; Mobile/Skid-Mounted GIS | Indoor GIS | Mobile/Skid-Mounted GIS |
| By Technology | SF₆-Based GIS; SF₆-Free GIS | SF₆-Based GIS | SF₆-Free GIS |
| By End-User | Power Transmission Utilities; Power Distribution Utilities; Renewable Generators and IPPs; Industrial; Others | Power Transmission Utilities | Renewable Generators and IPPs |
| By Geography | North America; Europe; Asia-Pacific; South America; Middle East & Africa | Asia-Pacific | Asia-Pacific |
Market Segmentation Overview
By Voltage
| Sub-Segment | Key Trend |
| Medium Voltage | Migration toward clean-air designs in urban distribution rooms |
| High Voltage | Standardised bay architectures shortening delivery cycles |
| Extra High Voltage | Corridor projects driving 400 kV and 765 kV bay demand |
Voltage mix is drifting upward as transmission distances lengthen. Extra-high-voltage bays carry substantially higher unit value, so even modest share gains translate into outsized revenue contribution over the forecast decade.
By Installation Type
| Sub-Segment | Key Trend |
| Indoor GIS | Underground and multi-storey urban configurations expanding |
| Outdoor GIS | Preferred route for brownfield conversion of existing yards |
| Mobile / Skid-Mounted GIS | Emergency restoration and staged-expansion deployments rising |
Installation preference tracks site constraint. Enclosed indoor halls dominate value, while transportable units capture the growth premium because utilities increasingly value energization speed over lowest installed cost.
By Technology
| Sub-Segment | Key Trend |
| SF₆-Based GIS | Continued dominance at EHV pending alternative qualification |
| SF₆-Free GIS | Fluoronitrile and clean-air series reaching commercial scale |
The dielectric transition is the decade's defining structural change. Regulatory deadlines, not cost curves, set the pace, and suppliers with completed type-test portfolios will hold pricing power through the early 2030s.
By End-User
| Sub-Segment | Key Trend |
| Power Transmission Utilities | Replacement cycles overlapping with expansion capex |
| Power Distribution Utilities | Urban substation compaction under land pressure |
| Renewable Generators and IPPs | Direct ownership of grid connection assets |
| Industrial | Data centre and mining campus loads driving captive builds |
| Others | Rail traction, ports and airport electrification projects |
Buyer composition is broadening beyond traditional utilities. Independent developers and industrial campuses now procure directly, compressing decision cycles and rewarding suppliers who compete on schedule certainty rather than unit price alone.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA